
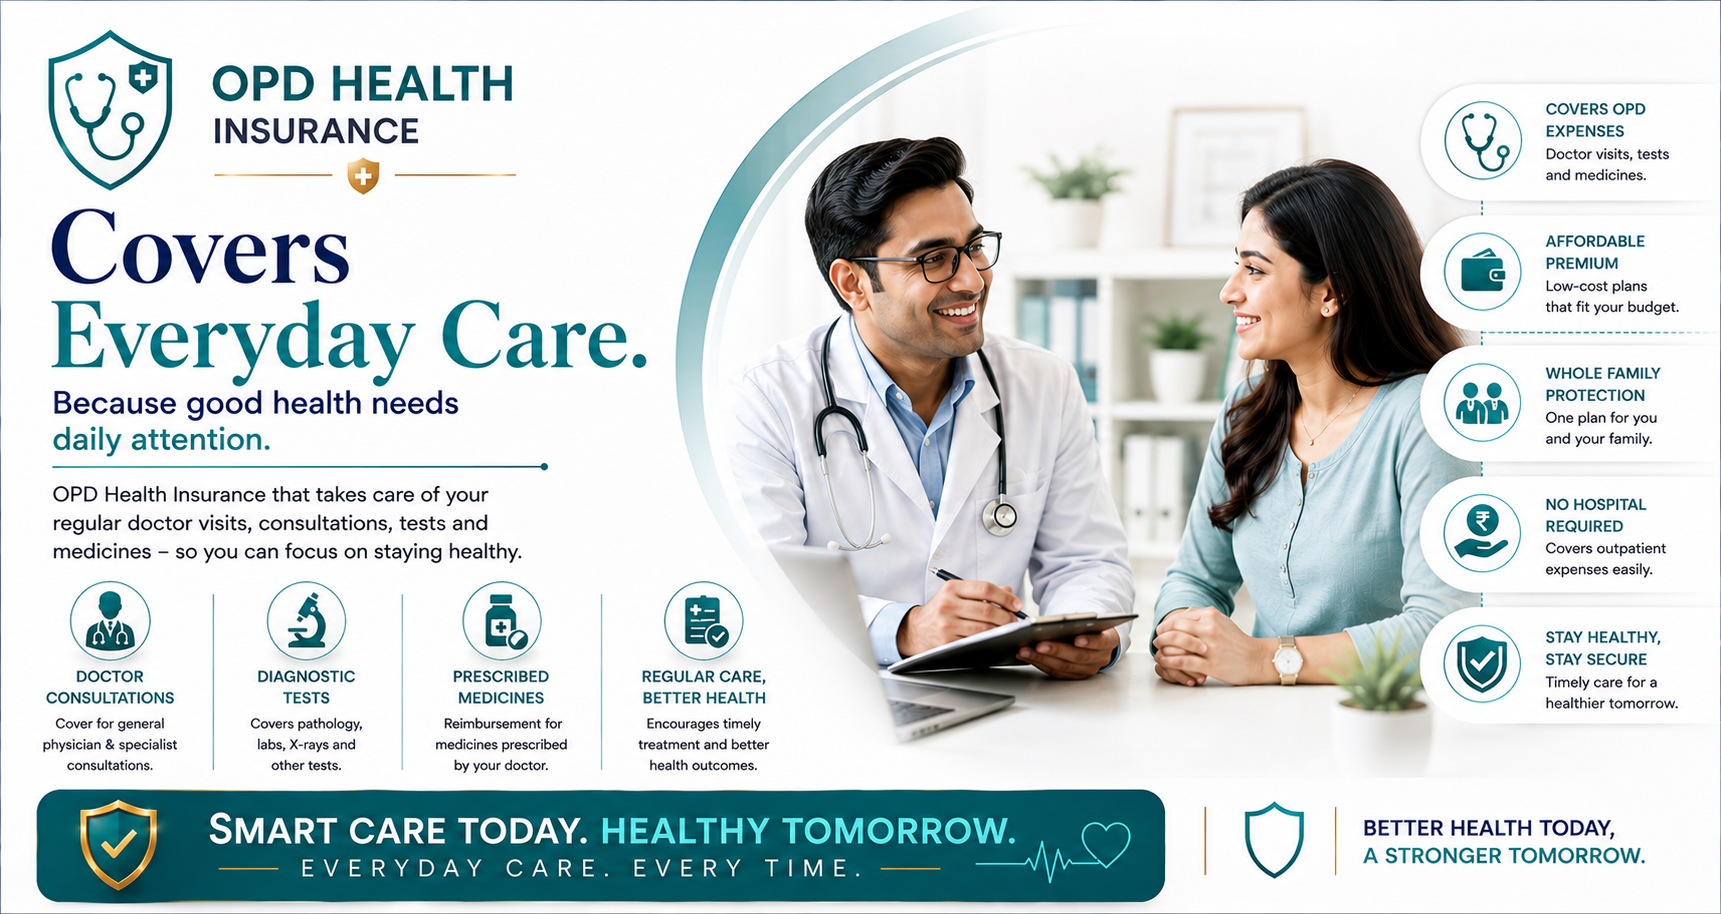
Get Expert Guidance
What Our Plans Cover
-
In-clinic consultations with regis...
-
Teleconsultations
-
Prescribed pathology and radiology
-
Pharmacy against prescription
-
Routine dental treatment
-
Eye examination and prescription l...
-
Physiotherapy on referral
-
Annual preventive health check-up
Who Can Consider This Plan?
- Indian resident, typically aged 18 to 65 at entry
- Children can usually be covered from 91 days, subject to insurer rules
- Medical tests may be required above a threshold age or sum insured
- Full and accurate disclosure of existing conditions, medication and family history
- Tobacco and alcohol use must be declared — non-disclosure is the leading cause of rejected claims
What May Not Be Covered?
- Anything above the annual out-patient limit
- Over-the-counter purchases without a prescription
- Cosmetic and aesthetic treatment
- Nutritional supplements and wellness products on most plans
- Treatment outside the insurer's network, on network-restricted plans
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
Out-patient cover pays for medicine you receive without being admitted: doctor consultations, prescribed diagnostics, pharmacy bills and, on many plans, dental and vision care. A standard health policy covers almost none of this, because it responds only to hospitalisation.
For most households, out-patient spending is small per event and relentless over a year. Four consultations, two rounds of tests and a quarter of pharmacy bills add up quietly, and none of it is claimable under the policy people believe covers their health.
OPD cover is therefore a budgeting product rather than a catastrophe product. It is usually capped at a modest annual limit, and the honest test is whether the limit exceeds the premium by enough to be worth the administration.
Who should consider it
Families with young children, where consultations are frequent by definition. Anyone managing a chronic condition that requires regular review and repeat prescriptions. Households that already spend predictably on routine care and would rather budget for it once.
It is poor value for someone who rarely sees a doctor. If your realistic annual out-patient spend is below the premium, this is a cost, not a cover — and the money is better placed in a larger hospitalisation sum insured.
Benefits
- Doctor consultations covered up to the annual limit
- Prescribed diagnostics and laboratory tests covered
- Pharmacy bills against a valid prescription
- Dental and vision care included on many plans
- Teleconsultation frequently unlimited and outside the cash limit
- Premium qualifies under Section 80D like other health premiums
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- In-clinic consultations with registered practitioners
- Teleconsultations, often unlimited
- Prescribed pathology and radiology
- Pharmacy against prescription
- Routine dental treatment, where the plan provides it
- Eye examination and prescription lenses, where provided
- Physiotherapy on referral, on some plans
- Annual preventive health check-up
Typically not covered
- Anything above the annual out-patient limit
- Over-the-counter purchases without a prescription
- Cosmetic and aesthetic treatment
- Nutritional supplements and wellness products on most plans
- Treatment outside the insurer's network, on network-restricted plans
- Spectacle frames beyond a stated cap, where lenses are covered
- Alternative therapies not named in the policy
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 Tell us who is being covered Age, city, existing conditions and any cover you already hold. Two minutes, and it decides everything downstream.
- 2 We shortlist on structure, not price Room rent, co-payment, sub-limits and pre-existing waiting periods — the four things that decide what you actually get paid.
- 3 You see two or three options, with the trade-offs named Including what each one gives up. If your existing policy is already the right answer, we will tell you that.
- 4 Proposal and medicals We help you complete disclosure properly. A medical test, where required, is usually arranged at home.
- 5 Policy issued, and we stay on the file At claim time you call us, not a helpline. We prepare the file, submit it and chase the insurer until it settles.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Do the arithmetic before buying. If the premium is close to the annual limit, you are pre-paying your own routine expenses with an insurer in the middle.
- Never trade hospitalisation cover for out-patient cover. A ₹50,000 OPD limit does not help with an ₹8 lakh admission.
- Check whether the plan restricts you to a network. Out-of-network reimbursement is where these policies most often disappoint.
- Per-visit caps matter as much as the annual limit. A ₹1,000 consultation cap against a ₹1,500 specialist fee leaves you paying every time.
- Keep every prescription. Out-patient claims are refused for missing paperwork far more often than for anything substantive.
Documents required
- Completed proposal form with full medical disclosure
- Identity proof — Aadhaar, passport, voter ID or driving licence
- Address proof
- PAN card
- Recent passport-size photograph
- Medical reports, where the insurer requires them at your age or sum insured
- Existing policy copy, if you are porting
Frequently Asked Questions
Does my regular health policy already cover consultations?
Almost certainly not. A standard health policy responds to hospitalisation of 24 hours or more, plus defined pre and post-hospitalisation windows around an admission. Routine consultations, tests and pharmacy outside those windows fall outside it entirely — which is the gap this product addresses.
Is it worth the premium?
Only if your realistic annual out-patient spending comfortably exceeds it. Families with young children and people managing chronic conditions usually clear that bar; someone who sees a doctor twice a year usually does not.
How are claims settled?
Cashless at network clinics, labs and pharmacies, and by reimbursement elsewhere if the plan allows it. Reimbursement needs the prescription, the bill and the report — keep all three from the start rather than assembling them later.
Is teleconsultation included?
On most modern plans, yes, and frequently without counting against the cash limit. It is often the most-used feature of the cover.
Can I buy it without a hospitalisation policy?
A few insurers sell it standalone, but it is usually offered as a rider. Either way, treat hospitalisation cover as the priority and out-patient cover as the addition — never the other way round.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.