
Plan your investment
What Our Plans Cover
-
Fixed periodic redemption paid to...
-
Monthly
-
The remaining corpus stays investe...
-
Ability to modify or stop the plan...
-
Full redemption of the balance at...
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, subject to the fund house accepting the country of residence
- Completed KYC with a registered KYC registration agency
- PAN, which is mandatory for all mutual fund investments
- A bank account in the investor's own name for transactions
What May Not Be Covered?
- Any guarantee that the corpus will last a given period
- Any guaranteed income amount
- Protection against market falls reducing the corpus
- Exit load on withdrawals inside the stated period
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
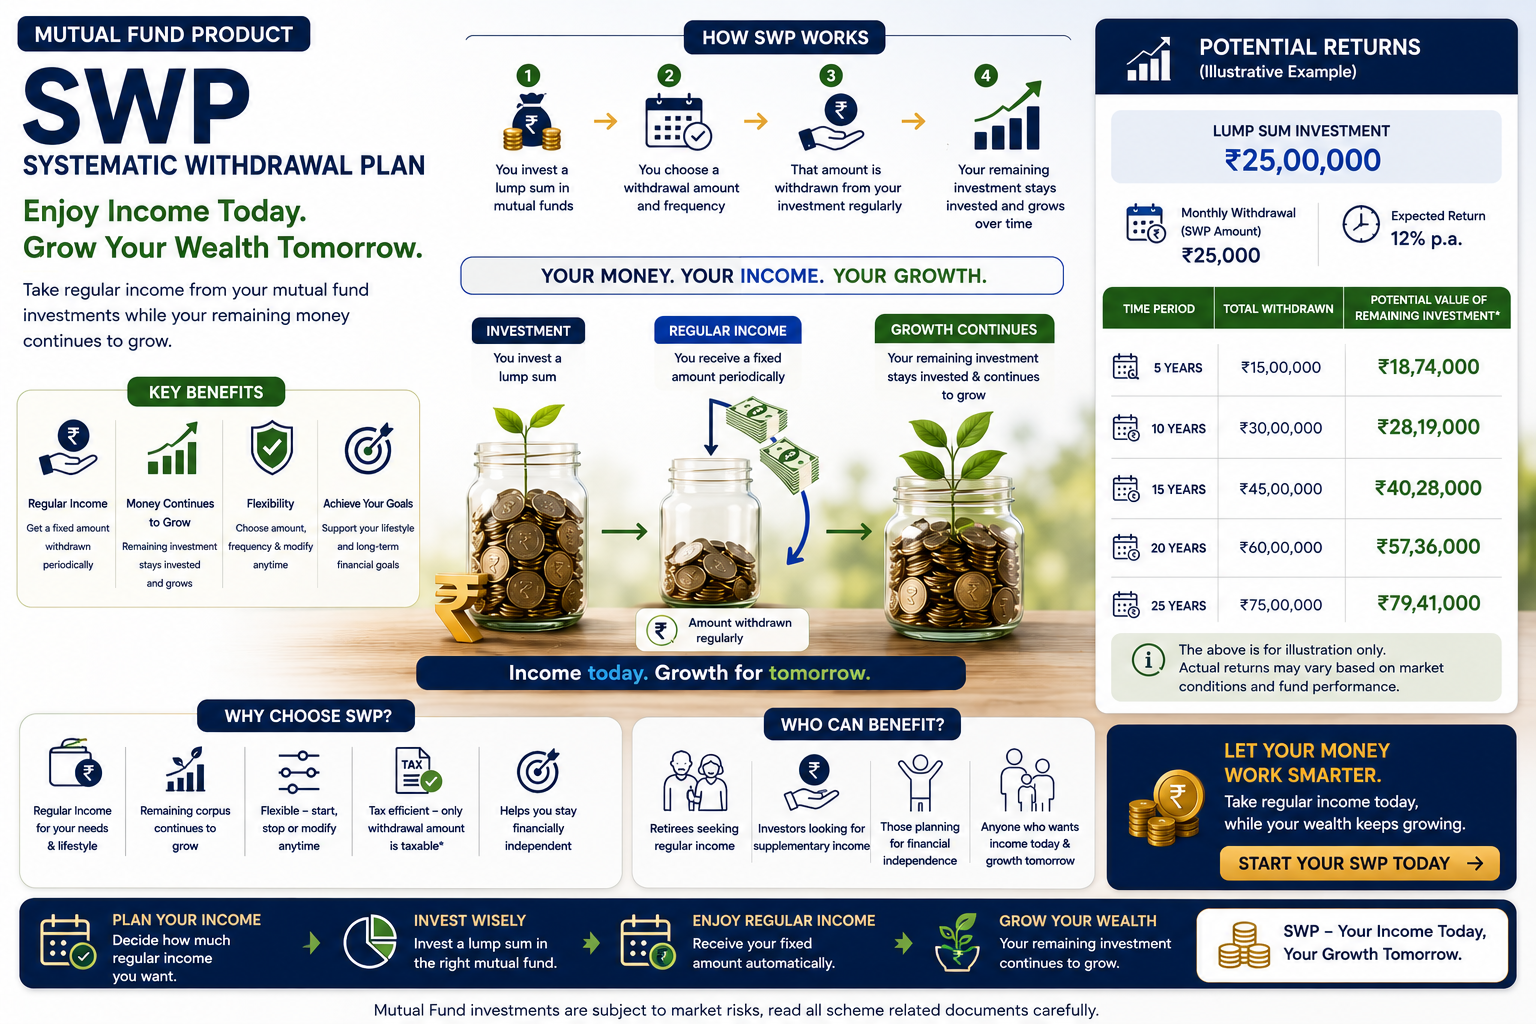
A systematic withdrawal plan redeems a fixed amount from your fund holding at a fixed interval, paying it into your bank account. The rest of the corpus stays invested and continues to be exposed to the market.
It is most commonly used to generate retirement income. Rather than moving an entire corpus into a fixed deposit, an investor keeps it in a balanced or debt-oriented fund and draws a monthly amount, allowing the remaining capital to keep working.
The tax treatment is the technical advantage. Each withdrawal is a redemption, so only the capital gains component is taxed rather than the whole amount — which is different from interest income, where the entire receipt is taxable. For a retiree in a higher bracket, that difference is meaningful.
Who should consider it
Retirees converting a corpus into monthly income. Investors needing a regular draw without exhausting capital. Anyone comparing this against an annuity or a monthly income plan.
It requires more attention than an annuity. The corpus is exposed to markets and can be depleted faster than expected if the withdrawal rate is too high or returns disappoint.
Benefits
- Regular income while the balance stays invested
- Only the gains component of each withdrawal is taxed
- The withdrawal amount and frequency can be changed at any time
- You retain full access to the remaining corpus
- Nothing is locked in, unlike an annuity
- Can be combined with a debt or hybrid fund to reduce volatility
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Fixed periodic redemption paid to your bank account
- Monthly, quarterly or annual frequency
- The remaining corpus stays invested in the chosen scheme
- Ability to modify or stop the plan at any time
- Full redemption of the balance at any point
Not included
- Any guarantee that the corpus will last a given period
- Any guaranteed income amount
- Protection against market falls reducing the corpus
- Exit load on withdrawals inside the stated period
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 Goal and horizon before fund selection What the money is for and when you need it decides the asset class. The fund name is the last decision, not the first.
- 2 Risk profiling that is honest rather than flattering Capacity to take risk and willingness to sit through a fall are different things. We assess both, because the second is what breaks plans.
- 3 Shortlist built on process, not last year's return Mandate, expense ratio, fund manager tenure and how the fund behaved in a bad year. Past performance is not a forecast.
- 4 KYC, onboarding and the first investment One-time KYC, then the folio and the mandate. We set up the SIP so it runs without depending on you remembering.
- 5 Review annually, rebalance deliberately A yearly review against the goal, not a monthly reaction to markets. Most damage in investing is self-inflicted.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Set the withdrawal rate conservatively. Drawing more than the corpus can sustain depletes it faster than most people expect, and the effect compounds.
- A fall early in the drawdown period does disproportionate damage, because you are selling units at low prices. Holding one to two years of withdrawals in a liquid fund cushions that.
- Use debt or hybrid funds for the income portion. Drawing a fixed amount from a volatile equity fund forces selling at bad moments.
- Unlike an annuity, nothing here is guaranteed and nothing is locked. That flexibility is the advantage; the absence of a floor is the cost.
- Mutual fund investments are subject to market risk. The corpus can fall in value and there is no assurance the withdrawals can be sustained indefinitely.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Cancelled cheque or bank account details
- Recent passport-size photograph
- Completed KYC, or KYC documents to complete it
- FATCA and nominee declaration
Frequently Asked Questions
How is this better than a fixed deposit for income?
The corpus stays invested and can grow, and the tax treatment differs — only the gains component of each withdrawal is taxed, rather than the whole receipt as with deposit interest. The trade is that nothing is guaranteed and the corpus carries market risk.
How much can I safely withdraw?
Conservatively. A rate that exceeds what the corpus can sustain depletes it faster than intuition suggests, and the damage compounds. The right figure depends on the asset mix and your horizon, which is a calculation worth doing properly rather than estimating.
What is sequence risk?
The risk that a market fall early in your drawdown does lasting damage, because you are redeeming units at depressed prices and there is less capital left to recover. Holding one to two years of planned withdrawals in a liquid fund is the usual defence.
How is an SWP different from an annuity?
An annuity guarantees an income for life and takes your capital permanently. An SWP guarantees nothing, keeps the capital accessible, and can be stopped or changed at any time. Many retirees use both — an annuity floor for essential expenses and an SWP for the rest.
Which funds suit an SWP?
Debt and hybrid schemes generally, because drawing a fixed amount from a volatile equity fund forces redemptions at bad moments. The asset mix should reflect that you are now a seller of units, not only a buyer.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.