
Plan your investment
What Our Plans Cover
-
Units in an InvIT holding transmis...
-
Distributions from contracted reve...
-
Exposure across multiple assets an...
-
Quarterly operational and financia...
-
Holding in your demat account
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, subject to the applicable investment routes
- A demat account and a trading account
- PAN and completed KYC
- Minimum investment as per the exchange lot size
What May Not Be Covered?
- Protection against counterparty payment delays
- Protection against regulatory tariff changes
- Perpetual asset life; contracts and concessions expire
- Any guarantee of distribution
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
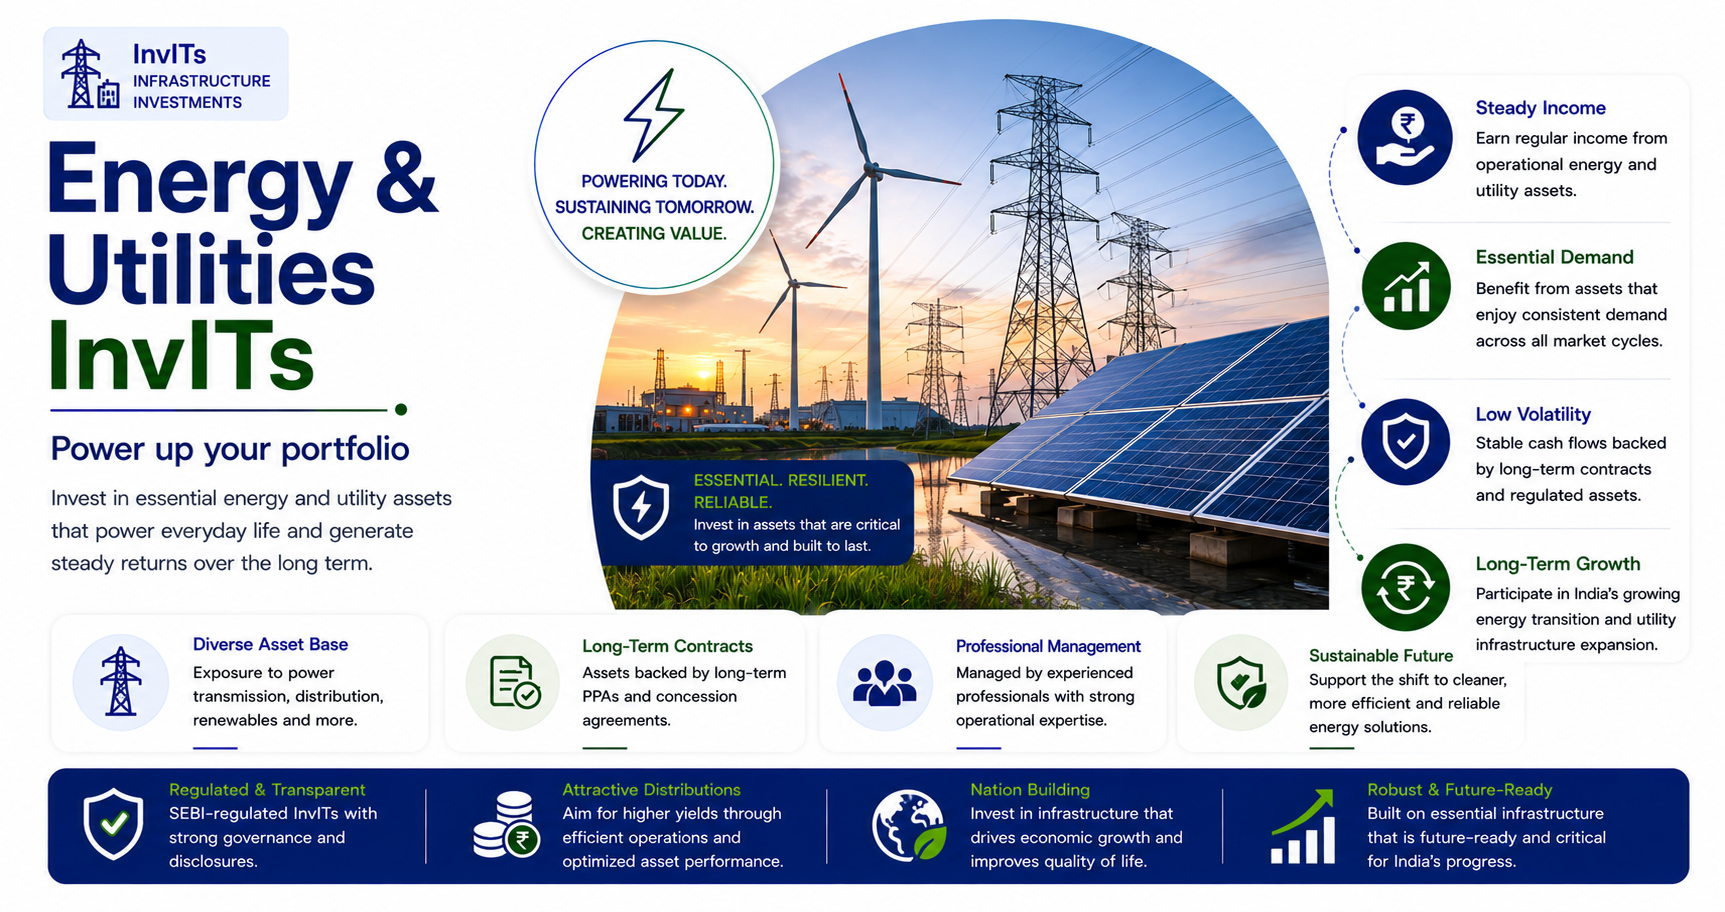
Energy and utilities InvITs hold power transmission lines, renewable generation assets and related infrastructure. Revenue typically comes under long-term contracts — transmission service agreements or power purchase agreements — rather than from variable usage.
That contractual structure is the category's main attraction. A transmission line earning an availability-based charge is paid for being available rather than for how much power flows through it, which removes volume risk almost entirely.
It replaces it with counterparty risk. The payer is usually a state distribution utility, and the financial health of those utilities varies considerably. Payment delays are a recurring feature of the Indian power sector, and they affect distributions directly.
Who should consider it
Income-focused investors wanting contracted rather than volume-based revenue. Investors seeking exposure to renewable energy through operating assets. Anyone comfortable assessing distribution utility counterparties.
Benefits
- Revenue under long-term contracts rather than variable usage
- Availability-based transmission charges remove volume risk
- Exposure to renewable generation through operating assets
- Long contract tenures providing visibility
- Regulated tariff frameworks in transmission
- Listed liquidity
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Units in an InvIT holding transmission and generation assets
- Distributions from contracted revenue
- Exposure across multiple assets and states
- Quarterly operational and financial disclosure
- Holding in your demat account
Not included
- Protection against counterparty payment delays
- Protection against regulatory tariff changes
- Perpetual asset life; contracts and concessions expire
- Any guarantee of distribution
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 We explain the finite-life point first Most InvIT assets have a concession period. Part of the yield is your own capital returning, and that changes how to read it.
- 2 Distribution quality examined, not just the number How much is genuinely surplus cash and how much is capital return, and what happens to it as the concession runs down.
- 3 Counterparty and concession terms read carefully Who pays the revenue, under what contract, and for how long. That is where the real risk in an InvIT sits.
- 4 Purchase through the exchange Listed InvIT units trade like shares and settle into your demat account.
- 5 Distributions tracked and taxed by component Interest, dividend and return of capital are taxed differently. Reporting them correctly is part of holding these.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Counterparty quality is the central question. State distribution utilities vary considerably in financial health, and payment delays in the sector are a recurring feature rather than an exception.
- Availability-based revenue removes volume risk, which is a genuine structural advantage over toll roads. Understand which of your assets are on that basis.
- Renewable generation under a power purchase agreement carries generation risk — wind and solar output varies — even when the offtake is contracted.
- Regulatory tariff determinations affect transmission revenue. Policy risk is real in this sector.
- Check receivable ageing in the disclosures. Delayed payments from utilities show up there before they show up in distributions.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Demat account details
- Bank account proof for distribution credit
- Completed KYC with the broker
Frequently Asked Questions
What makes transmission revenue predictable?
Availability-based charges. A transmission line earns for being available to carry power rather than for how much actually flows, which removes volume risk almost entirely. That is a genuine structural advantage over assets whose revenue depends on usage.
Who actually pays?
Usually state distribution utilities, and their financial health varies considerably. Payment delays in the Indian power sector are a recurring feature rather than an exception, and they feed directly into distributions. Receivable ageing in the disclosures is worth watching.
Is renewable generation as predictable as transmission?
Less so. Even with a contracted offtake under a power purchase agreement, generation depends on wind and solar resource, which varies year to year. The offtake is contracted; the output is not.
What about regulatory risk?
It is real. Transmission tariffs are determined under regulatory frameworks that can change, and policy shifts in the power sector have affected asset economics before. This is a sector where regulatory developments matter to returns.
What happens when contracts expire?
Assets either secure renewed contracts, often at different terms, or revert under concession arrangements. The weighted average remaining contract life across the portfolio is one of the more useful metrics to look at.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.