
Get Expert Guidance
What Our Plans Cover
-
Death benefit at the increased sum...
-
Automatic annual escalation
-
Escalation continuing to a stated...
-
Terminal illness acceleration on m...
-
Optional critical illness and acci...
-
Optional waiver of premium on disa...
Who Can Consider This Plan?
- Entry age typically 18 to 65, with cover ceasing between 60 and 85
- Demonstrable income — the sum assured must be justified by earnings
- Full disclosure of health, smoking, alcohol use and family medical history
- Medical examination, usually required above a threshold age or sum assured
- Indian resident or NRI, subject to the insurer's country rules
What May Not Be Covered?
- Suicide within the first twelve months
- Increases beyond the stated ceiling, after which cover is level
- Any maturity or survival benefit — this remains pure protection
- Death from concealed material facts
- Undeclared hazardous activities
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
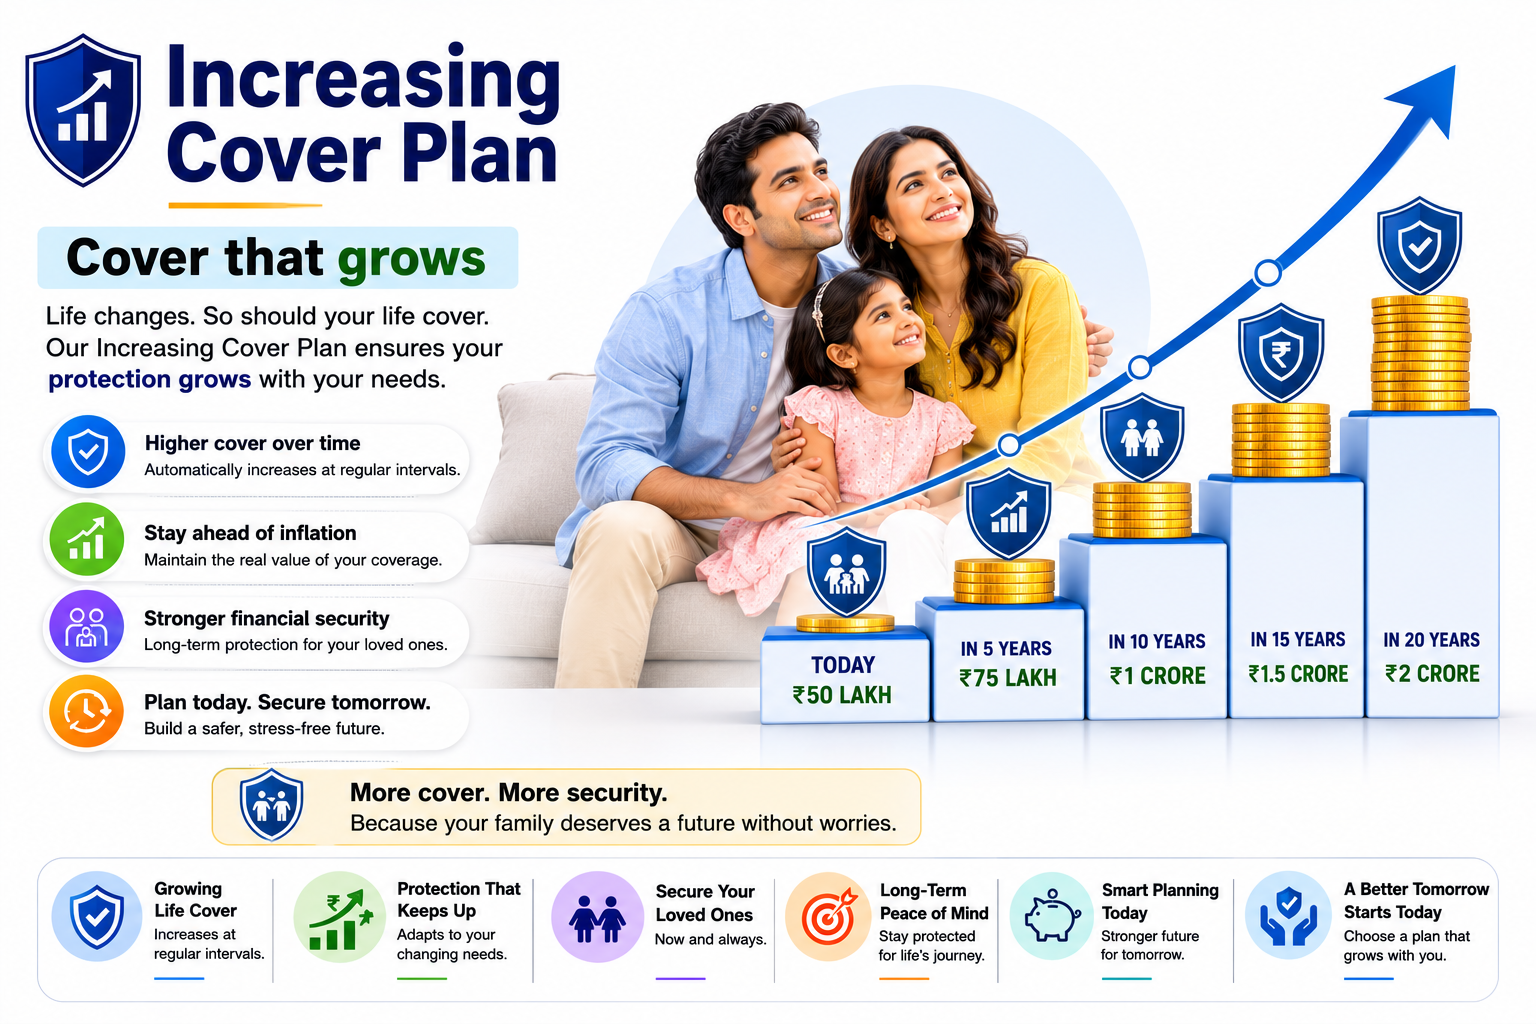
An increasing cover term plan raises the sum assured by a fixed percentage each year — commonly five or ten per cent — while the premium stays level or rises on a defined schedule. Cover bought at fifty lakh can be well past a crore by the time it is most likely to be needed.
The problem it solves is real and widely ignored. A sum assured fixed in 2026 is worth substantially less in 2046, while the responsibilities it was bought for tend to grow: a larger home, a second child, an ageing parent, school fees that rise faster than general inflation.
The alternative is to review your cover every few years and buy additional policies as needs change. That works, but it depends on your health remaining insurable and on you actually doing the reviews. An increasing plan makes the escalation automatic and locks the underwriting in today.
Who should consider it
Young professionals early in a career with a rising income trajectory. Anyone whose responsibilities are clearly going to grow — recently married, planning children, planning a property purchase.
It is also the right answer for anyone with a health history that makes future underwriting uncertain. Locking in an escalating sum assured now removes the need to be insurable again later.
Benefits
- Sum assured rises automatically each year without fresh underwriting
- Cover keeps pace with inflation instead of quietly eroding
- Health is underwritten once, at today's age and today's health
- Removes the need to remember to review and top up your cover
- Cheaper in total than buying a series of separate policies later
- Section 80C on premium, Section 10(10D) on the death benefit
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Death benefit at the increased sum assured applicable in the year of death
- Automatic annual escalation, commonly 5% or 10%
- Escalation continuing to a stated ceiling, often double the original cover
- Terminal illness acceleration on most plans
- Optional critical illness and accidental death riders
- Optional waiver of premium on disability
Typically not covered
- Suicide within the first twelve months
- Increases beyond the stated ceiling, after which cover is level
- Any maturity or survival benefit — this remains pure protection
- Death from concealed material facts
- Undeclared hazardous activities
- Escalation during a lapse, since the policy has no force at all
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 We work out the cover, before the plan Income, liabilities, dependants and the years they need supporting. The sum assured is the decision; the brand is a detail.
- 2 Underwriting reality check Health, occupation, smoking and family history decide who will accept you and at what price. Better to know now than after a rejection.
- 3 Two or three quotes with the claim record attached Premium matters, but so does the insurer's claim settlement history and how it treats early claims.
- 4 Proposal, medicals and financial underwriting Medicals are arranged at home. For larger cover the insurer will also want income proof — we prepare that file properly.
- 5 Policy issued, and your family knows where it is A term plan nobody can find is a term plan that does not pay. We make sure the nominee has the details.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Establish whether the escalation is simple or compounding, and where the ceiling sits. Two plans described identically can differ substantially over thirty years.
- Check whether the premium is level or escalating. A level premium on rising cover is the better structure and is not universal.
- Compare the total cost against a level plan at the higher sum assured from the start. Sometimes buying the larger cover immediately is simply cheaper.
- Once escalation stops at the ceiling, the cover is level again and begins to erode. Know when that happens rather than discovering it at sixty.
- The strongest argument for this plan is medical, not financial: it removes the need to be insurable again in fifteen years.
Documents required
- Completed proposal form with full health and lifestyle disclosure
- Identity proof — Aadhaar, passport or PAN
- Address proof
- PAN card, mandatory for life insurance
- Income proof — salary slips, Form 16 or filed returns
- Bank statements, for larger sums assured
- Medical reports, arranged by the insurer
- Recent passport-size photograph
Frequently Asked Questions
How much does the cover actually increase?
Commonly five or ten per cent of the original sum assured each year, up to a ceiling that is often double the starting cover. Whether the increase is simple or compounding matters a great deal over a long term, and plans differ — read the specific wording.
Does the premium go up as well?
On the better plans, no — the premium is level and only the cover rises. Some plans escalate both. This is one of the clearest differentiators between contracts and is worth confirming before comparing prices.
Is this better than buying more cover later?
It is more certain. Buying later depends on you remembering to do it and on remaining insurable at that time. A diagnosis in your forties can make additional cover expensive or unavailable, and this plan removes that risk by underwriting you once.
What happens when the escalation stops?
The sum assured stays level at the ceiling for the remainder of the term. From that point it erodes with inflation like any level plan — so know the ceiling year and plan around it.
Should I take this or a larger level plan now?
Price both. If you can comfortably afford the larger level cover today, it is often the simpler and cheaper route. The increasing plan wins where affordability now is a constraint but income is clearly rising.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.