
Wealth & Covers
Search products, guides, calculators
+919990003062

Health Insurance

Care when it counts

  • Unbiased Advice
  • Claims Assistance
  • Competitive Premiums
  • End-to-End Support
Health Insurance

What are you looking to insure?

Choose the right cover

Personal Health

Most Popular

A health policy in your own name — portable across jobs, priced on your age today, and renewable for life.

  • The policy is yours — a job change, redundancy or retirement does not touch it
  • Premium is fixed by your entry age, so buying earlier costs less for the same cover
  • Waiting periods for pre-existing conditions start running from day one of the policy
View Details

Family Floater

One sum insured shared across the household — efficient when risk is even, dangerous when it is not.

  • One premium, one renewal date and one policy document for the whole household
  • Priced largely on the eldest member, which is efficient when ages are close together
  • A large sum insured becomes affordable — cover no single member could justify alone
View Details

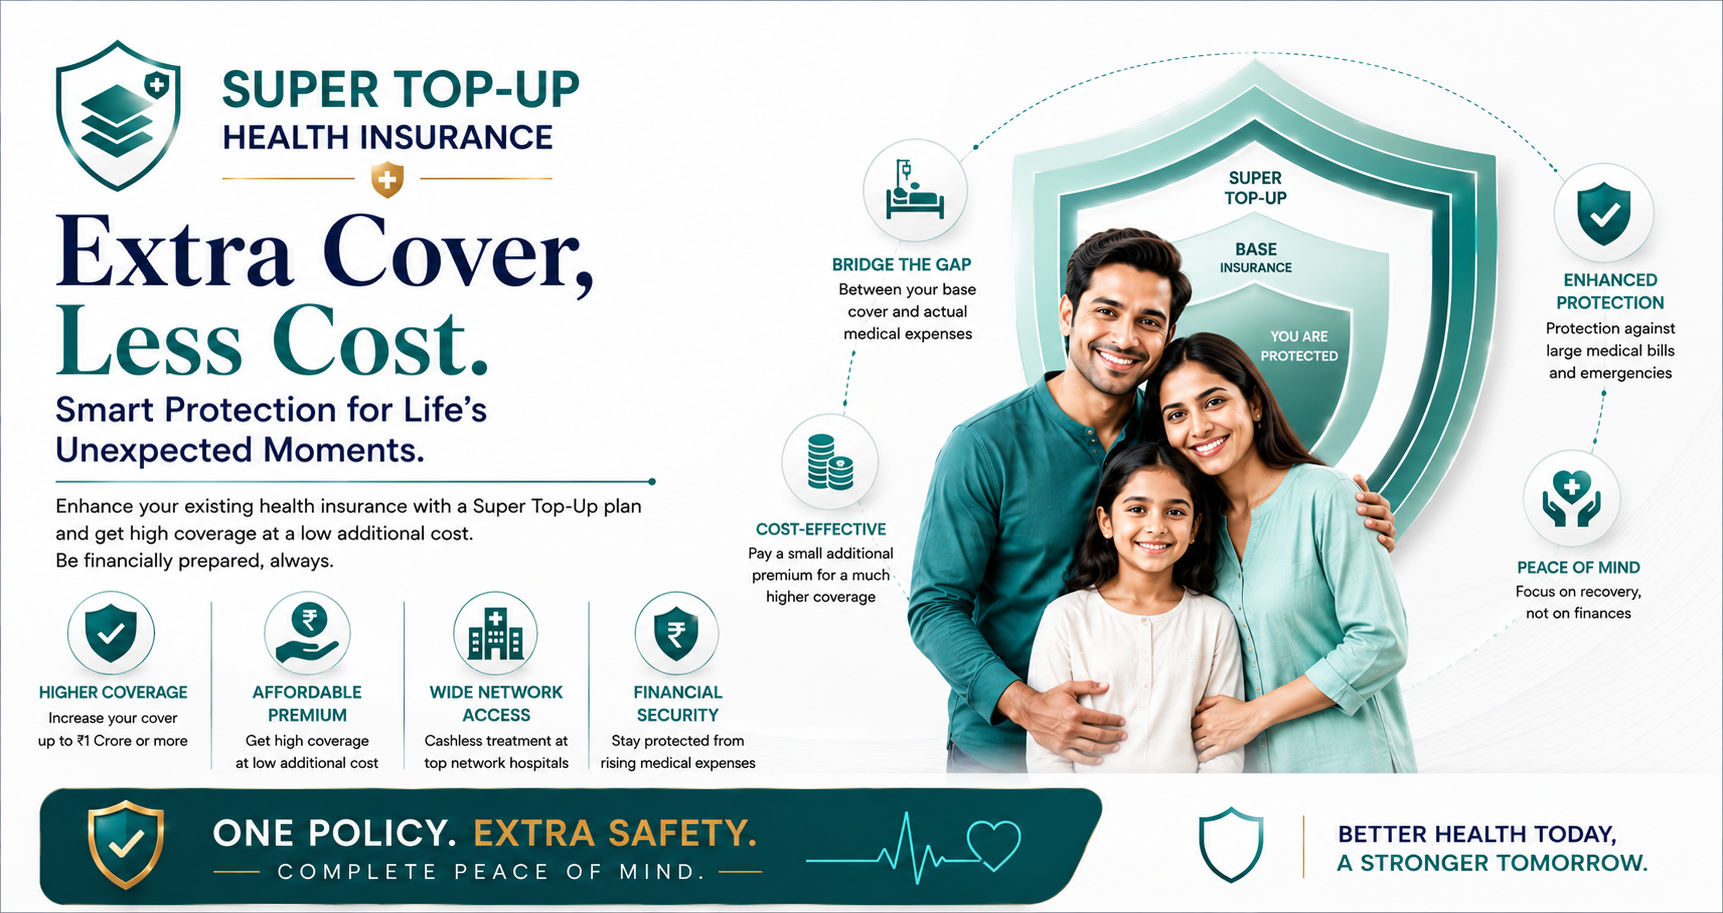
Super Top-Up

Large cover above a deductible — the cheapest way to add a second layer over an existing policy.

  • A very large sum insured for a fraction of what the same cover costs on a base policy
  • Aggregates every claim in the policy year against a single deductible
  • Sits over any existing cover — your own policy, an employer group policy, or both
View Details

Today Protected. Tomorrow Stronger.

Why Health Insurance?

  • The policy is yours — a job change, redundancy or retirement does not touch it
  • Premium is fixed by your entry age, so buying earlier costs less for the same cover
  • Waiting periods for pre-existing conditions start running from day one of the policy
  • Cashless treatment at network hospitals, so you are not funding a deposit in a crisis
  • Premium qualifies for deduction under Section 80D of the Income Tax Act

More than Policies A Partner for Life

What's Covered?

  • Hospitalisation for 24 hours or more — room, nursing, doctors, drugs and diagnostics
  • Pre-hospitalisation expenses, typically the 30 to 60 days before admission
  • Post-hospitalisation expenses, typically 60 to 90 days after discharge
  • Day-care procedures that modern medicine completes in under 24 hours
  • ICU and intensive care charges, subject to any stated limit
  • Ambulance charges up to the policy limit
View complete coverage

What's Not Covered?

  • Pre-existing conditions during the waiting period, commonly two to four years
  • The initial waiting period, usually the first 30 days except for accidents
  • Named ailments with their own waiting period — hernia, cataract, joint replacement and similar
  • Maternity and childbirth unless a maternity benefit is specifically included
  • Cosmetic, aesthetic and elective procedures with no medical necessity
  • Dental and optical treatment unless it follows an accident
View all details

Compare Popular Plans

Plan Personal Health Family Floater Super Top-Up Senior Citizen
Best for Protect yourself. One cover for all Extra cover, less cost Care for their years.
Premium from* ₹6,500 ₹11,000 ₹4,200 ₹22,000
Rating 4.6 4.5 4.7 4.4
Details View View View View

*Indicative starting figures; the final terms depend on your profile.

Compare Plans

Already have insurance?

Review your existing policies and ensure you're truly protected.

  • Find coverage gaps
  • Avoid duplications
  • Check renewal dates
  • Get expert recommendations

Get your current cover reviewed

Share it with an advisor — no cost, no obligation

We're Here After You Buy Too.

Frequently Asked Questions

View All FAQs
Is an individual policy better than a family floater?

Neither is universally better. A floater shares one sum insured across the family and is efficient when everyone's risk is broadly similar. An individual policy is better where one person's health profile differs sharply from the rest, because in a floater that person can consume the cover the whole family depends on. Many households end up with a sensible hybrid: a floater over the family plus a separate individual policy on the member with the higher risk.

I already have health cover through my employer. Do I need this?

Almost certainly yes. Employer cover ends with the employment, and it ends at exactly the moment a new policy is hardest to buy — after a diagnosis, at an older age, or during a job search. Holding a policy in your own name alongside the group cover means you never have to buy protection under pressure.

What is a waiting period and why does it matter so much?

A waiting period is a window at the start of the policy during which certain claims are not payable. There is usually a 30-day initial period, a longer one for named ailments, and a longer one still for pre-existing conditions. They matter because they run from the date the policy begins — so the cost of delaying a purchase is not just a higher premium, it is a later date on which your existing conditions become claimable.

How much sum insured is enough?

It depends on your city and your family history far more than on any rule of thumb. In a metro, a single serious hospitalisation can run past ₹8 to ₹10 lakh. Rather than buying one very large policy, most people are better served by a base policy topped by a super top-up above a deductible, which buys substantially more total cover for a similar premium.

What is cashless treatment, and is it guaranteed?

At a network hospital the insurer settles the bill directly, so you are not funding a large deposit during an emergency. It is not a guarantee: the hospital raises a pre-authorisation request and the insurer approves an amount, which can be partial and can be revised. Outside the network you pay and claim reimbursement afterwards. Either way, intimate the claim early.

Not sure what health insurance you need?

Tell us about your needs. Our experts will help you find the right cover.

Talk to an Expert

Speak to an advisor

Good decisions begin with clarity.

Tell us where you are today. We’ll help you understand what matters, what may be missing, and what you can do next.

See the full picture
Understand what you already have and where it stands.
Find what's missing
Identify the gaps that could affect your family, wealth or business.
Know what to do next
Get practical guidance built around your priorities — not a product pitch.

No pressure. No obligation. Just a thoughtful conversation.

Let's Connect

Your details are safe & confidential. We'll contact you only regarding your enquiry.