
Wealth & Covers
Search products, guides, calculators
+919990003062

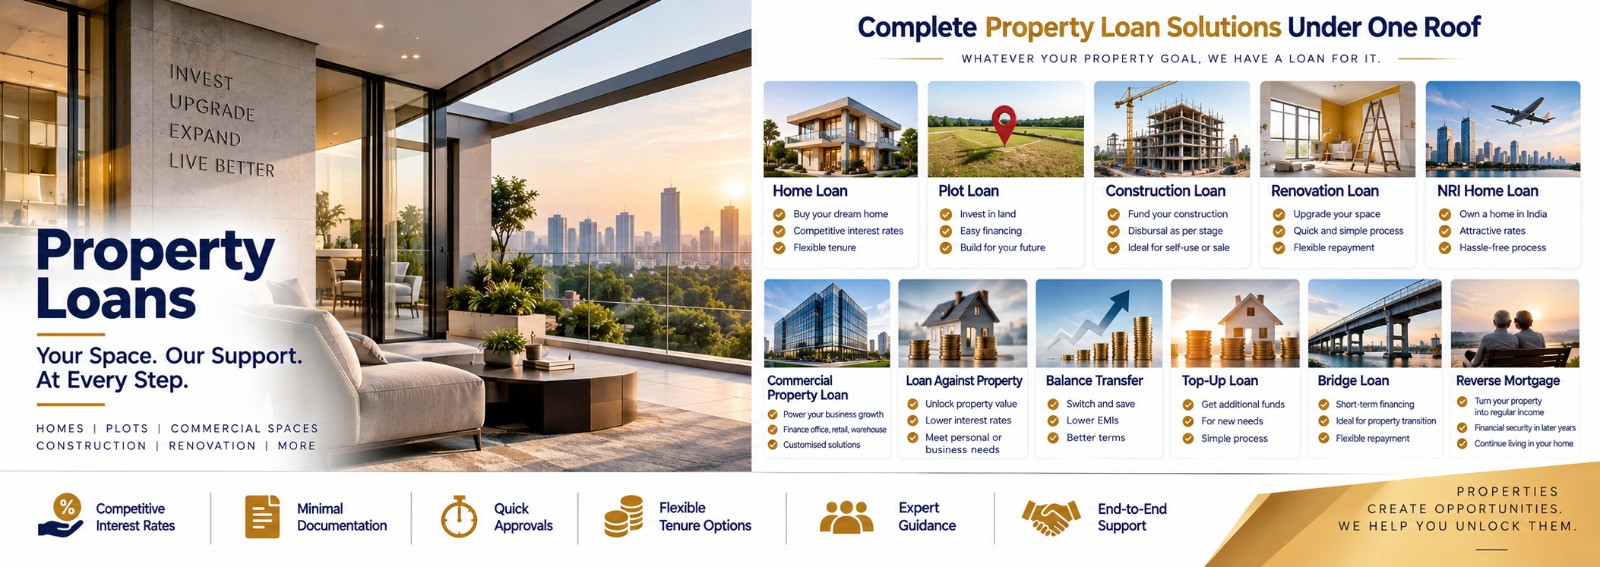
Property Loan

Own your address

  • Multiple Lenders
  • Eligibility Check
  • Competitive Rates
  • End-to-End Support
Property Loan

What are you looking to fund?

Choose the right loan

Home Loan

Most Popular

The cheapest long-term borrowing available to an individual — and the one where small differences compound most.

  • The lowest interest rate available on any retail borrowing
  • Tenure up to thirty years, which keeps the EMI manageable
  • Section 80C on principal and Section 24(b) on interest, under the old regime
View Details

Home Renovation Loan

Funding repairs and improvements at property-loan rates rather than personal-loan rates.

  • Rates far below an unsecured personal loan for the same work
  • Tenure up to fifteen years, keeping the EMI modest
  • Interest deductible under Section 24(b) for a self-occupied property, within limits
View Details

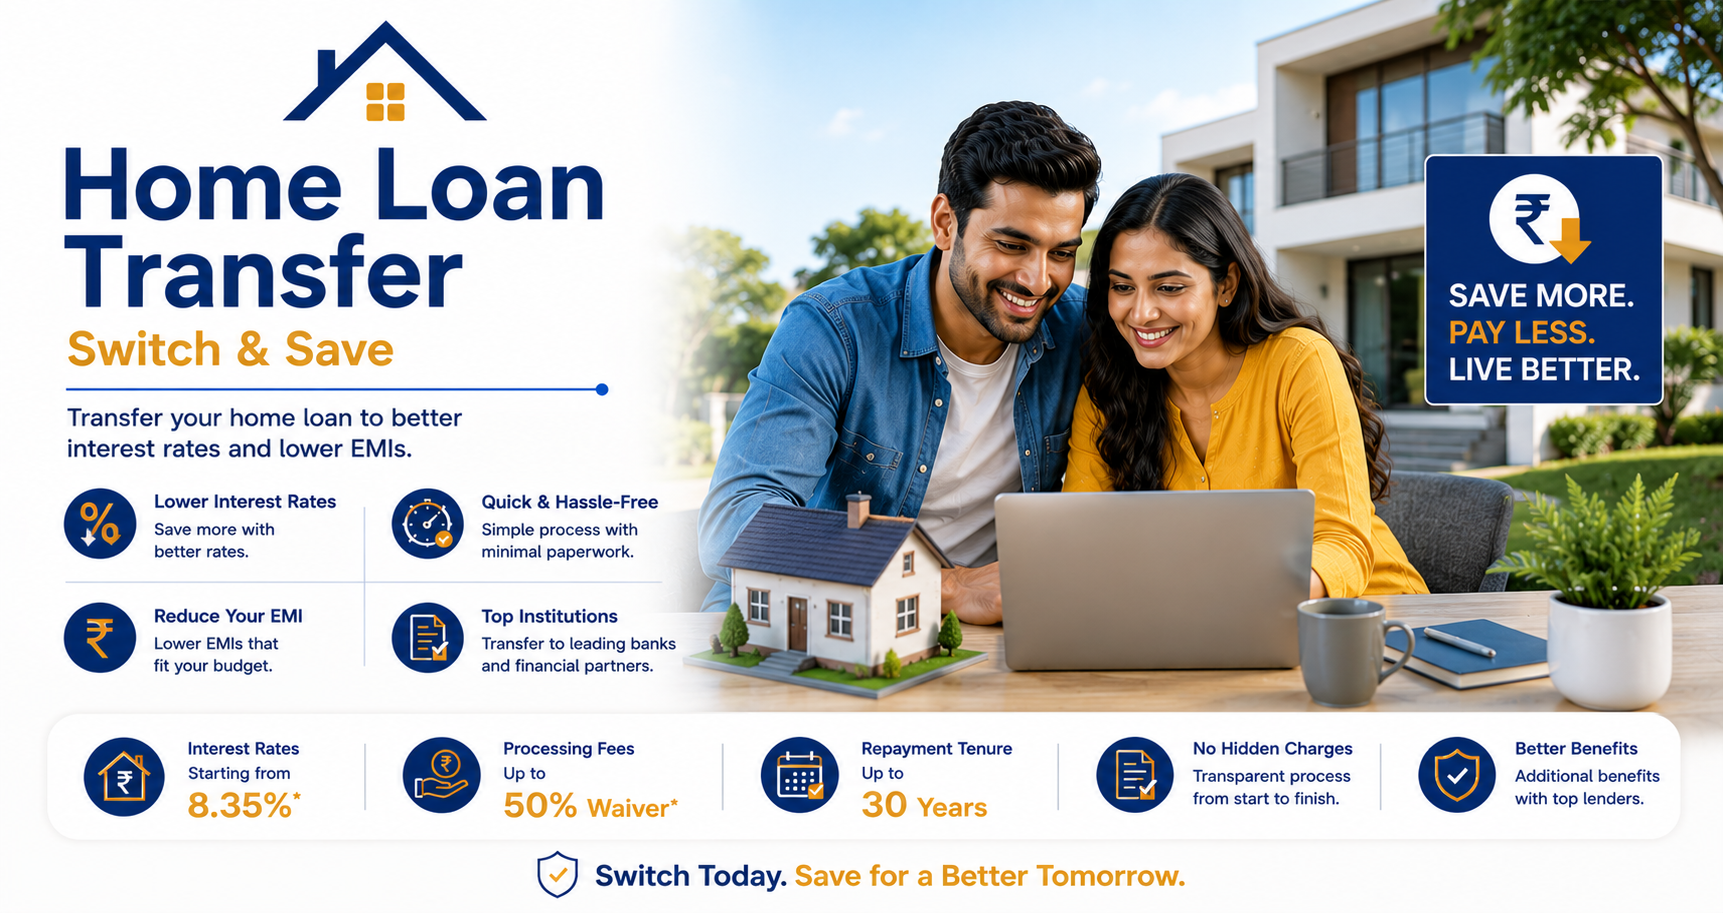
Home Loan Transfer

Moving a home loan to a cheaper lender — where the arithmetic usually works, unlike on shorter loans.

  • A lower rate saves a large amount across a long remaining tenure
  • Tenure can be shortened at the same time, saving more
  • Top-up borrowing frequently available alongside the transfer
View Details

Plan Today. Own Tomorrow.

Why Property Loan?

  • The lowest interest rate available on any retail borrowing
  • Tenure up to thirty years, which keeps the EMI manageable
  • Section 80C on principal and Section 24(b) on interest, under the old regime
  • No prepayment penalty on floating-rate loans to individuals
  • Balance transfer available if rates move against you

More than Loans A Partner for Life

What's Included?

  • Purchase of a ready or under-construction property
  • Registration and stamp duty, at some lenders and within limits
  • Cost of a parking space, where part of the sale agreement
  • Payment to the builder in construction-linked stages
  • Purchase from a resale seller against the sale deed
View complete coverage

Things to Keep in Mind

  • Down payment — the margin you contribute, typically 10 to 25 per cent
  • Processing, legal, technical and documentation charges
  • Interiors, furnishing and fit-out
  • Brokerage and society transfer charges
  • Property maintenance and society outgoings
  • Any amount above the lender's valuation of the property
View all details

Compare Popular Loans

Plan Home Loan Home Renovation Loan Home Loan Transfer Loan Against Property
Best for Own your home Upgrade your space Switch & save Unlock your equity
Interest from* 8.35% 9% 8.4% 9.5%
Rating 4.7 4.2 4.5 4.2
Details View View View View

*Indicative starting figures; the final terms depend on your profile.

Compare Plans

Already have a loan?

Review your existing loans and make sure you're not paying more than you need to.

  • Check for a lower rate
  • Explore a balance transfer
  • Check top-up eligibility
  • Get expert recommendations

Get your current loan reviewed

Share it with an advisor — no cost, no obligation

We're Here Till Your Last EMI.

Frequently Asked Questions

View All FAQs
Should I take the longest tenure available?

Only if you need to. A longer tenure reduces the EMI and increases total interest substantially — sometimes by more than the original loan amount. A useful approach is to take the longer tenure for safety and then prepay aggressively, which gives you flexibility without the cost.

How much does prepaying early actually save?

A great deal, because interest is front-loaded. In the first years most of your EMI is interest, so a prepayment then removes years of future interest. One extra EMI a year can shorten a twenty-year loan by three to four years.

Is a fixed or floating rate better?

Floating, for almost all borrowers. Fixed-rate home loans in India are usually fixed only for an initial period, are priced above floating, and can carry prepayment penalties that floating loans cannot. The rate certainty is rarely worth what it costs.

Do I have to buy insurance from the lender?

No. Loan protection cover is frequently bundled into the disbursal and is rarely competitive. You are entitled to buy a term plan separately for the loan amount, and doing so is usually cheaper and gives better cover.

What tax benefit do I actually get?

Under the old regime, principal repayment counts within the Section 80C limit and interest is deductible under Section 24(b), subject to the applicable ceiling for a self-occupied property. Under the new regime these are not available, so run our income tax calculator before assuming the benefit applies to you.

Not sure what property loan you need?

Tell us about your needs. Our experts will help you find the right loan.

Talk to an Expert

Speak to an advisor

Good decisions begin with clarity.

Tell us where you are today. We’ll help you understand what matters, what may be missing, and what you can do next.

See the full picture
Understand what you already have and where it stands.
Find what's missing
Identify the gaps that could affect your family, wealth or business.
Know what to do next
Get practical guidance built around your priorities — not a product pitch.

No pressure. No obligation. Just a thoughtful conversation.

Let's Connect

Your details are safe & confidential. We'll contact you only regarding your enquiry.