
Check your eligibility
What These Loans Fund
-
The lender's assessed value of the...
-
Transfer of ownership charges
-
Insurance for the first year
-
Valuation and inspection charges
Who Can Consider This Loan?
- Indian resident, generally aged 21 to 65 at loan maturity
- Salaried applicants: stable employment, commonly at least one year of total experience
- Self-employed applicants: business vintage, typically two to three years, with filed returns
- Minimum income threshold that varies by lender, city and vehicle segment
- Credit score materially affects both approval and the rate offered
- Existing EMIs are counted — total obligations usually cannot exceed 50 to 55% of income
What May Not Be Funded?
- Any gap between the agreed price and the lender's valuation
- Down payment — the margin you contribute
- Processing fee and documentation charges
- Repairs, refurbishment and reconditioning after purchase
- Vehicles older than the lender's age cap
Always check the sanction letter before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading loans companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced loans professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
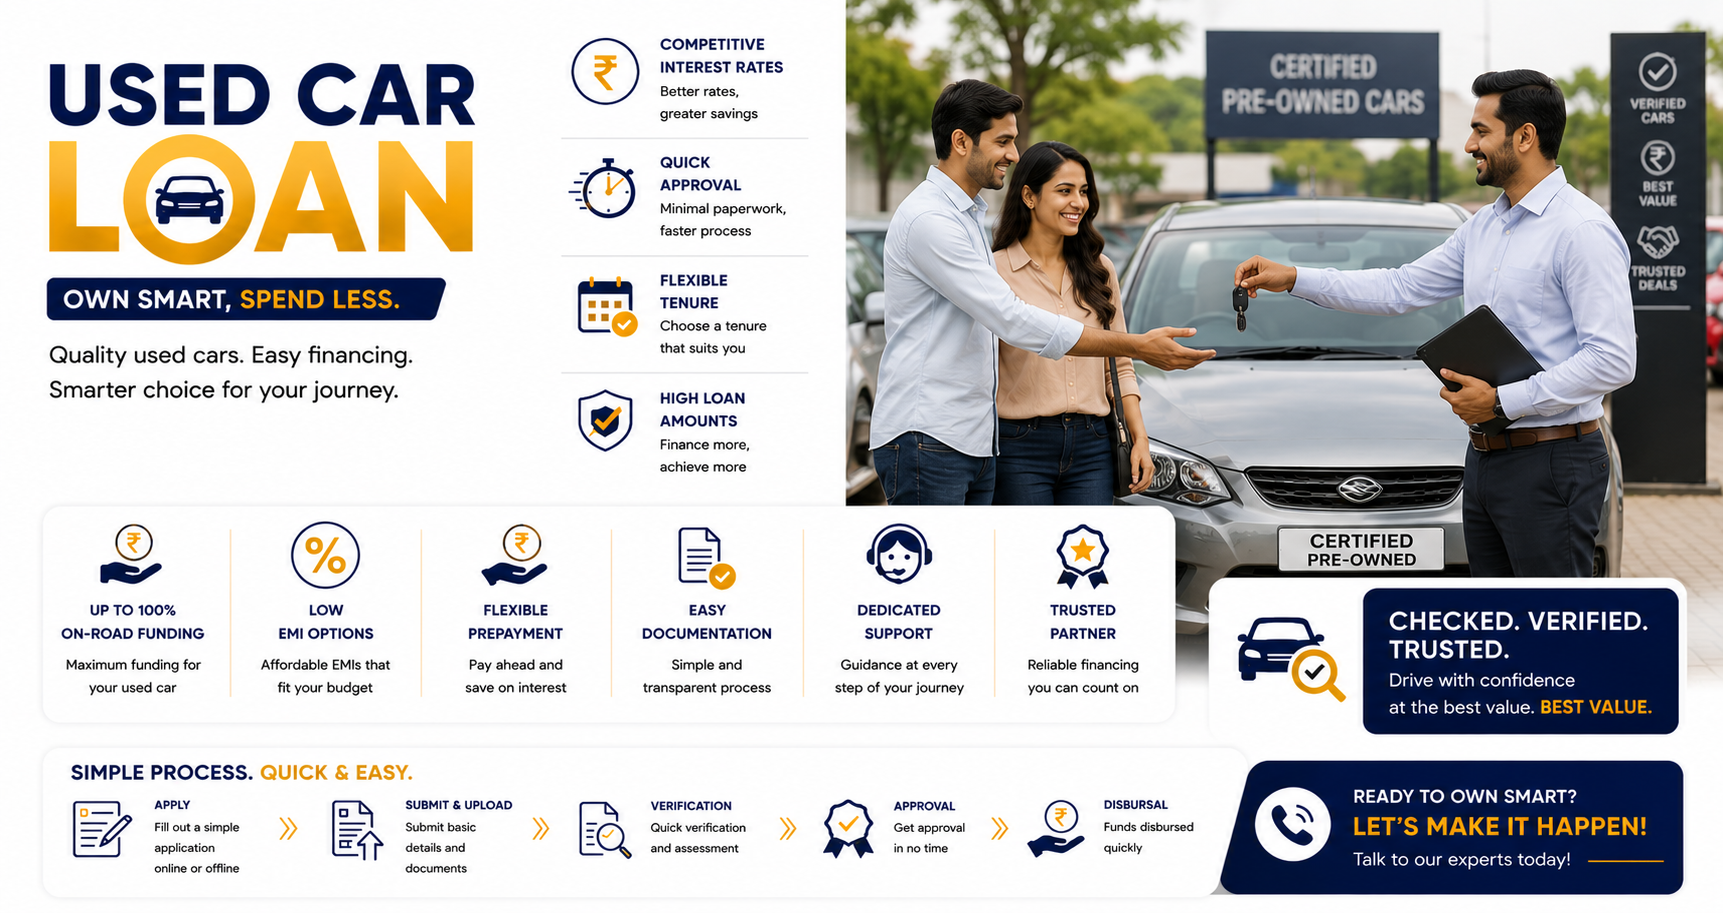
A used car loan is secured against a vehicle whose value the lender has to estimate rather than read off an invoice. That single difference explains most of what distinguishes it from new car finance: higher rates, shorter tenures, lower funding percentages and a valuation step in the middle of the process.
Lenders typically fund 70 to 85 per cent of their own assessed value, not the price you agreed with the seller. Where those two numbers differ, the gap is yours to bridge — and buyers who have negotiated hard on price are frequently surprised to find the lender valuing the car below what they are paying.
Vehicle age is the other constraint. Most lenders cap the vehicle's age at the end of the loan term, commonly at ten to twelve years, which quietly shortens the tenure available on an older car regardless of what you can afford.
Who should consider it
Buyers purchasing from a dealer or privately who want to preserve savings. Buyers who have concluded, correctly, that a two-year-old car with the steepest depreciation already absorbed is better value than a new one.
It is worth comparing against a loan against securities or a top-up on an existing home loan, both of which can be cheaper if you have the underlying assets.
Benefits
- Makes a better car affordable without exhausting savings
- Secured lending, so cheaper than a personal loan for the same purpose
- Available for both dealer and private purchases
- No prepayment penalty on floating-rate loans to individuals
- Certified pre-owned programmes often carry better rates
- Loan can include transfer and registration costs at some lenders
What the loan funds, and what it does not
Read the right-hand column first. It is the one that decides how much you have to arrange yourself.
Usually funded
- The lender's assessed value of the vehicle, up to the funding percentage
- Transfer of ownership charges, at some lenders
- Insurance for the first year, where the lender permits funding it
- Valuation and inspection charges, sometimes deducted from disbursal
Usually not funded
- Any gap between the agreed price and the lender's valuation
- Down payment — the margin you contribute
- Processing fee and documentation charges
- Repairs, refurbishment and reconditioning after purchase
- Vehicles older than the lender's age cap
- Running costs and subsequent insurance renewals
Funding limits and the treatment of add-ons vary between lenders and move with the borrower profile. The sanction letter you receive is what governs — we will walk you through it before you sign.
How it works with us
- 1 Check eligibility before anyone pulls your credit file We assess income, existing EMIs and profile against lender criteria first, so applications only go where they will actually qualify.
- 2 Compare on total cost, not headline rate Rate, processing fee, tenure and prepayment terms together. A lower rate with a heavy fee is often the costlier loan.
- 3 Documentation prepared once One set of documents, used across lenders, rather than assembling a fresh file for each application.
- 4 Sanction and disbursal The sanction letter states rate, tenure and charges. Funds go directly to the dealer or seller against the invoice.
- 5 Delivery, and the paperwork after it Hypothecation is noted on the RC. We flag the closure formalities so removing it later is not a scramble.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- The lender funds a percentage of its own valuation, not of your negotiated price. Get an indicative valuation before agreeing a price, not after.
- Vehicle age caps the tenure. A seven-year-old car at a twelve-year cap gives you five years at most, whatever your affordability shows.
- Have the car inspected independently before committing. The lender's valuation assesses value, not condition, and those are different questions.
- Verify the seller has cleared any existing hypothecation. Buying a car with a live charge on the RC creates a transfer problem that is slow to unwind.
- Compare against a top-up on a home loan or a loan against securities. Both are usually cheaper if you hold the underlying assets.
Documents required
- Identity proof — Aadhaar, PAN, passport or driving licence
- Address proof
- Salaried: last three months of salary slips and Form 16
- Self-employed: last two to three years of income tax returns with computation
- Bank statements for the last six months
- Proforma invoice or booking confirmation from the dealer
- Passport-size photographs
- Existing loan statements, where you are servicing other EMIs
Frequently Asked Questions
Why is the rate higher than for a new car?
Because the security is worth less and is harder to value. A new car has an invoice; a used one has an estimate, and its resale value is less predictable. Lenders price that uncertainty, which is also why tenures are shorter and funding percentages lower.
How much will the lender actually fund?
Typically 70 to 85 per cent of the lender's own assessed value — not of the price you agreed. Where the lender values the car below your purchase price, that gap comes out of your pocket in addition to the down payment.
Is there an age limit on the car?
Most lenders cap the vehicle's age at loan maturity, commonly at ten to twelve years. That cap shortens the available tenure on an older vehicle regardless of what you can afford monthly.
Can I buy privately or only from a dealer?
Both, though private purchases involve more documentation and lenders sometimes fund a lower percentage. Certified pre-owned programmes at manufacturer dealerships often carry better rates because the vehicle history is documented.
What should I check about the seller?
That any existing hypothecation has been cleared and a no-objection certificate obtained. Buying a car with a live charge on the registration certificate makes the transfer slow and can stall your own loan disbursal.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.