
Wealth & Covers
Search products, guides, calculators
+919990003062

Term Insurance

The most cover per rupee

  • Unbiased Advice
  • Claims Assistance
  • Competitive Premiums
  • End-to-End Support
Term Insurance

What are you looking to insure?

Choose the right cover

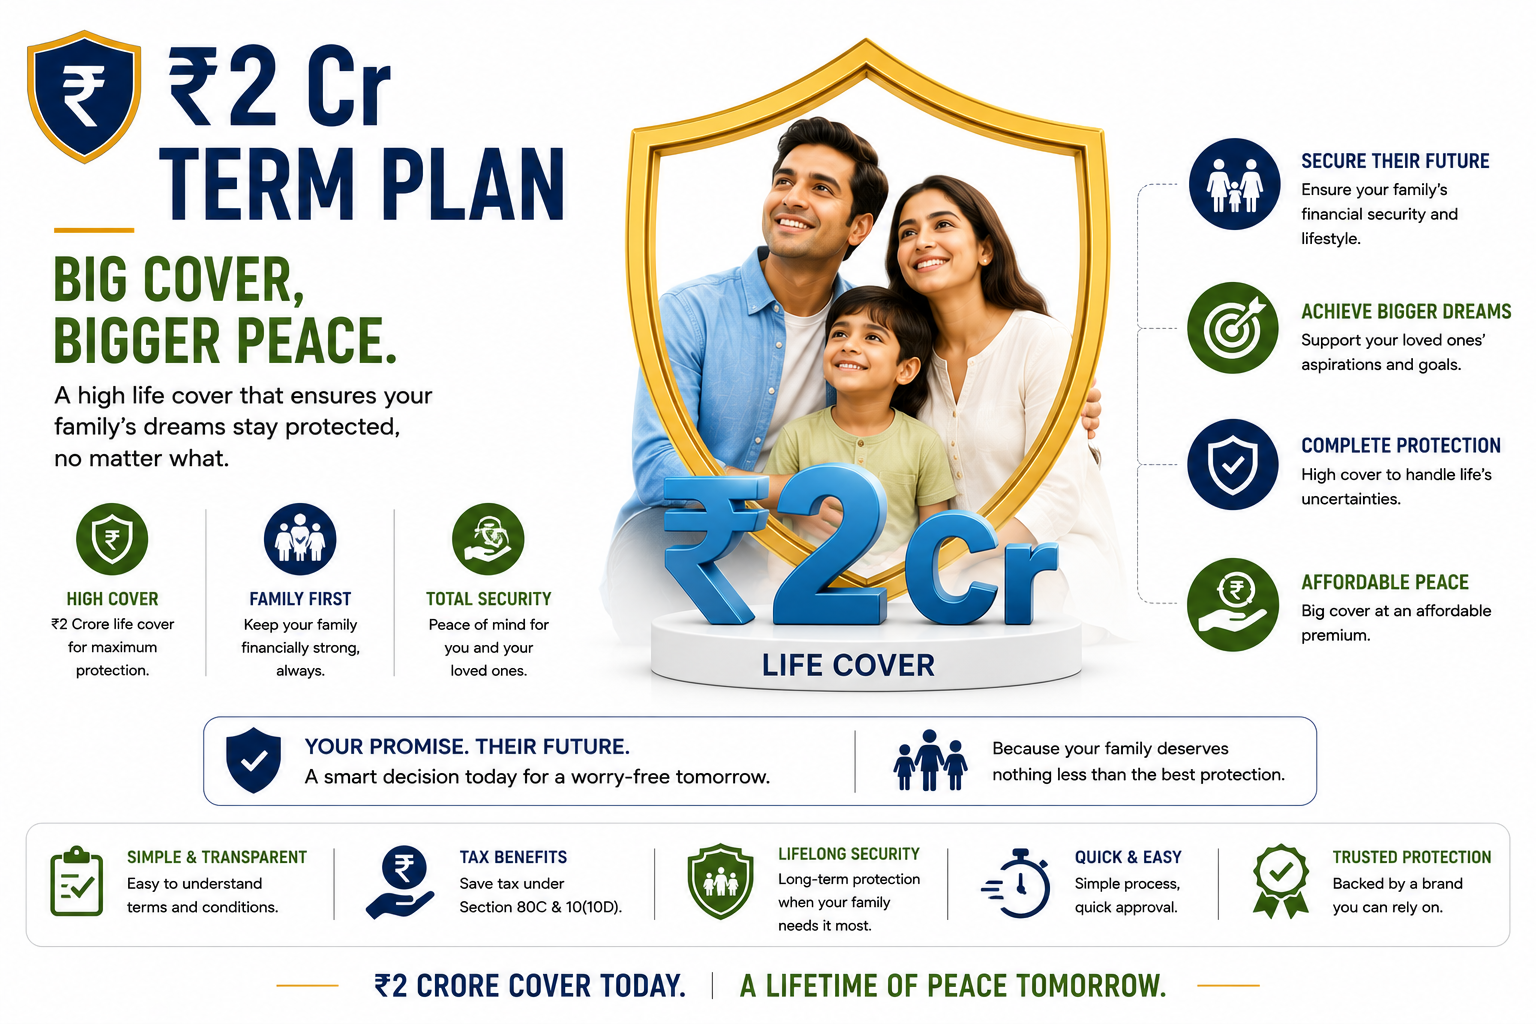
₹2 Cr Term Plan

Most Popular

Two crore of cover — what it takes to be approved for it, and what it actually costs.

  • A sum assured large enough to clear a metro home loan and still fund education
  • Cost per lakh of cover falls as the sum assured rises
  • Structured payout options — lump sum, monthly income, or both
View Details

Pure Term Plan

The most cover per rupee available anywhere — nothing back if you survive, which is precisely the point.

  • The highest sum assured per rupee of premium available in the market
  • Premium is level for the entire term, fixed at your entry age
  • A large cover becomes affordable for an ordinary income
View Details

Return of Premium Plan

Term cover that refunds your premiums if you survive — and costs two to three times as much for it.

  • The full sum assured is paid on death, as with any term plan
  • All premiums paid are returned if you survive the term
  • Nothing is "lost" if no claim occurs, which is the whole appeal
View Details

Today Protected. Tomorrow Stronger.

Why Term Insurance?

  • A sum assured large enough to clear a metro home loan and still fund education
  • Cost per lakh of cover falls as the sum assured rises
  • Structured payout options — lump sum, monthly income, or both
  • Riders can add critical illness and accidental death at this scale meaningfully
  • Premium under Section 80C; death benefit tax-free under Section 10(10D)

More than Policies A Partner for Life

What's Covered?

  • Death benefit of ₹2 crore to the nominee
  • Terminal illness acceleration on most plans
  • Choice of lump sum, staggered monthly income, or a combination
  • Optional critical illness rider, often up to a defined proportion of the cover
  • Optional accidental death benefit rider
  • Optional waiver of premium on total disability
View complete coverage

What's Not Covered?

  • Suicide within the first twelve months
  • Death from material facts concealed at proposal stage
  • Sum assured above what income and financial underwriting support
  • Undeclared hazardous occupations and pursuits
  • Any survival or maturity benefit — this is pure protection
  • Death during a lapse in cover
View all details

Compare Popular Plans

Plan ₹2 Cr Term Plan Pure Term Plan Return of Premium Plan Term for Housewives
Best for Big cover, bigger peace High cover, low cost Money back on survival Her care, her cover
Premium from* ₹18,000 ₹9,000 ₹24,000 ₹6,000
Rating 4.6 4.8 4.0 4.2
Details View View View View

*Indicative starting figures; the final terms depend on your profile.

Compare Plans

Already have insurance?

Review your existing policies and ensure you're truly protected.

  • Find coverage gaps
  • Avoid duplications
  • Check renewal dates
  • Get expert recommendations

Get your current cover reviewed

Share it with an advisor — no cost, no obligation

We're Here After You Buy Too.

Frequently Asked Questions

View All FAQs
What income do I need to be approved for ₹2 crore?

Broadly fifteen lakh a year or more, though insurers differ and the multiple applied varies with age — younger applicants are generally allowed a higher multiple of income. You will need filed returns or Form 16 to demonstrate it.

Is ₹2 crore too much cover?

It depends entirely on your liabilities. For a household with a metro home loan, two children in private school and one earner, it is often a realistic figure rather than a generous one. For a young single earner with no dependants and no debt, it is more than the need justifies.

Why is the premium lower per lakh at this level?

Because a large part of an insurer's cost is fixed per policy rather than per rupee of cover. Spreading that across a larger sum assured reduces the cost per lakh, which is why doubling cover rarely doubles the premium.

Will I need a medical test?

Almost certainly, and a full one. At this sum assured, insurers examine both health and finances closely. That thoroughness works in your family's favour later — a well-underwritten policy is a policy that is harder to contest.

Should the payout be a lump sum or a monthly income?

Consider who receives it. A lump sum offers flexibility and assumes financial confidence. A staggered monthly income protects a family that would find managing a very large sum difficult. Many buyers choose a partial lump sum to clear the loan, with the balance as income.

Not sure what term insurance you need?

Tell us about your needs. Our experts will help you find the right cover.

Talk to an Expert

Speak to an advisor

Good decisions begin with clarity.

Tell us where you are today. We’ll help you understand what matters, what may be missing, and what you can do next.

See the full picture
Understand what you already have and where it stands.
Find what's missing
Identify the gaps that could affect your family, wealth or business.
Know what to do next
Get practical guidance built around your priorities — not a product pitch.

No pressure. No obligation. Just a thoughtful conversation.

Let's Connect

Your details are safe & confidential. We'll contact you only regarding your enquiry.