
Plan your investment
What Our Plans Cover
-
Discretionary management of your p...
-
Execution through your own demat a...
-
Regular reporting of holdings
-
Rebalancing at the manager's discr...
-
Direct receipt of dividends and co...
Who Can Consider This Plan?
- Minimum investment of ₹50 lakh, as regulated
- Indian resident individual, HUF, trust, company or NRI
- Completed KYC with the portfolio manager
- A demat account in the investor's own name
- Acceptance by the portfolio manager
What May Not Be Covered?
- Any guarantee of return or of outperformance
- Your approval of individual trades
- Protection against market falls
- Low costs — fees are materially above mutual funds
- Availability below the ₹50 lakh regulatory minimum
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
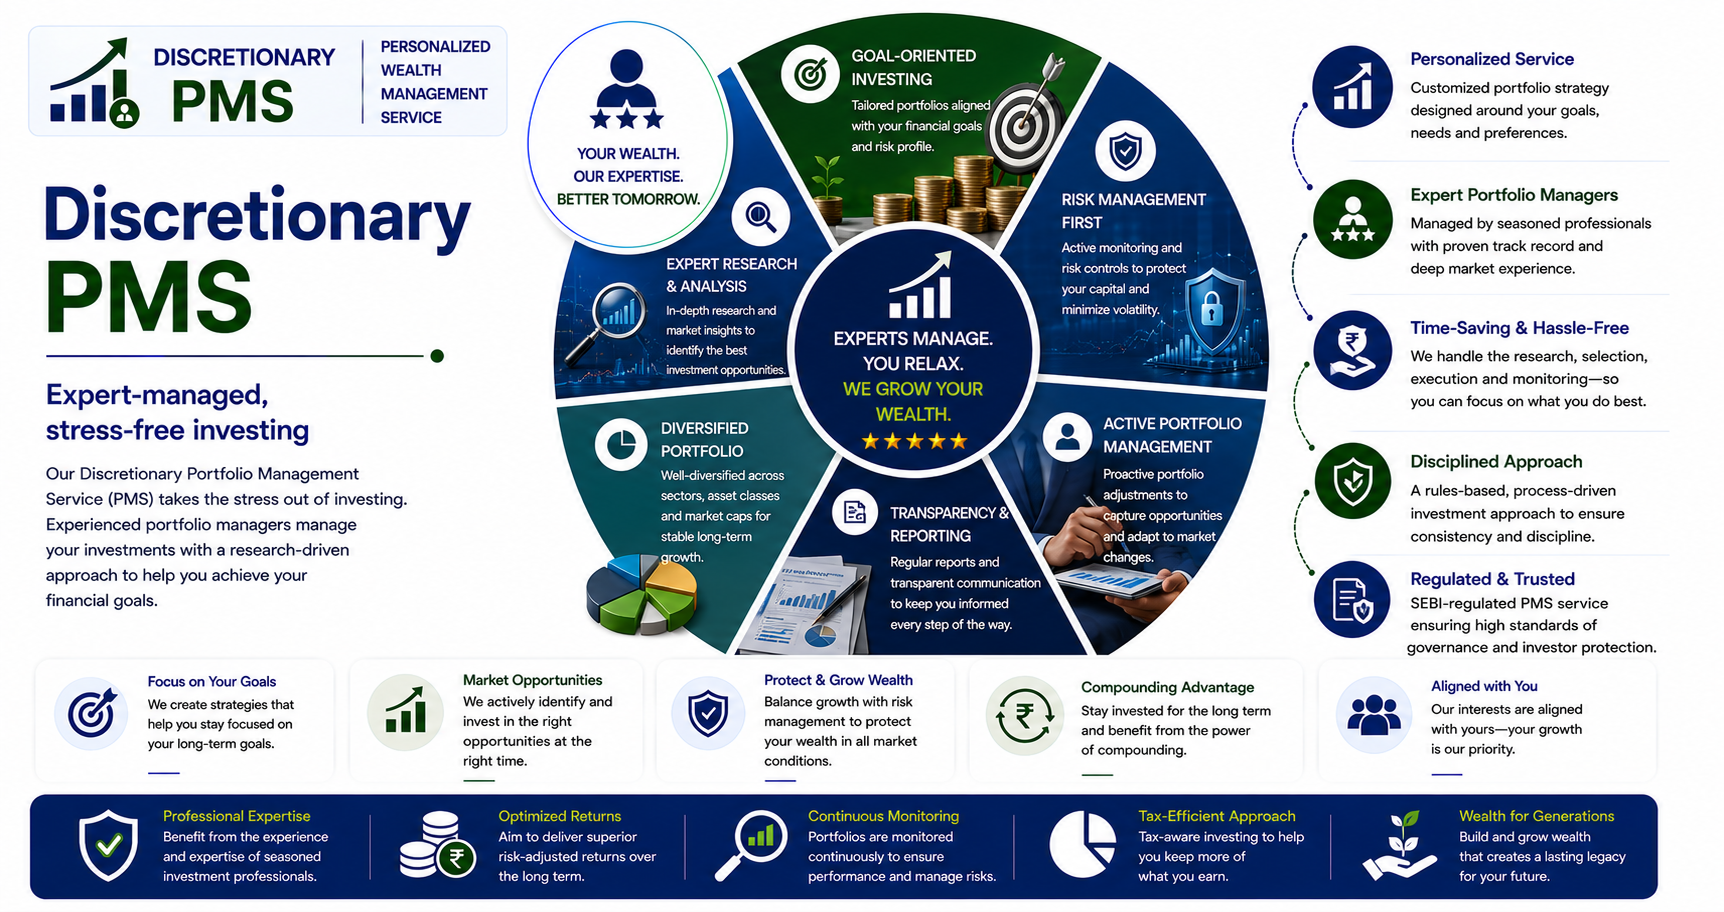
In a discretionary portfolio management service the manager makes and executes investment decisions without seeking your approval for each trade. Shares are bought in your own name and held in your own demat account, so you see every holding and every transaction.
That combination — professional management with direct ownership — is the structure's defining feature. Unlike a mutual fund, your gains and losses are your own rather than pooled, and the portfolio can be adjusted for your specific constraints.
The comparison worth making is against a mutual fund. A PMS costs materially more, has a fifty lakh minimum, and creates a taxable event on every rebalancing trade in your hands. It has to add enough value to overcome all three, and the honest position is that many do not.
Who should consider it
Investors above the minimum who want direct ownership and a portfolio shaped to their constraints. Investors with existing concentrated holdings a fund cannot accommodate. Investors who want full transparency of holdings and transactions.
Benefits
- Shares held directly in your own demat account
- Full visibility of every holding and every transaction
- Portfolio can accommodate your specific constraints
- Your tax position is your own, not pooled with other investors
- Professional management without needing to approve each trade
- Concentration levels a mutual fund cannot take
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Discretionary management of your portfolio
- Execution through your own demat and trading account
- Regular reporting of holdings, transactions and performance
- Rebalancing at the manager's discretion
- Direct receipt of dividends and corporate actions
Not included
- Any guarantee of return or of outperformance
- Your approval of individual trades
- Protection against market falls
- Low costs — fees are materially above mutual funds
- Availability below the ₹50 lakh regulatory minimum
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 We test the case against a mutual fund first A ₹50 lakh minimum and higher fees need justifying. If a fund does the same job, that is the honest answer.
- 2 Strategy and manager assessed on process, not last year How the portfolio is constructed, how it behaved in a bad year, and how consistent the process has been.
- 3 Fee structure understood in full Fixed fee, performance fee, hurdle, high-water mark and exit load. These vary enormously and compound over time.
- 4 Account opened and portfolio built Shares are bought in your own name in your own demat account. You see every transaction as it happens.
- 5 Reviewed on process and reported for tax Every trade is a taxable event in your hands. We keep the reporting straight and review against the mandate, not the market.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Portfolio turnover has a direct tax cost to you that a mutual fund investor does not bear. Ask about expected turnover, not just expected returns.
- Compare net-of-fee performance against a low-cost diversified fund over a full cycle. That is the test the structure has to pass.
- Ask how the strategy behaved in its worst year. Drawdown behaviour tells you more than annualised returns over a chosen period.
- Understand the performance fee mechanics — hurdle rate, high-water mark and calculation frequency. These vary considerably.
- Equity investments are subject to market risk. Discretionary management does not remove the possibility of loss.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Bank account proof
- Demat account details, or consent to open one
- Completed KYC and PMS agreement
- Power of attorney in favour of the portfolio manager
Frequently Asked Questions
How is this different from a mutual fund?
Shares are in your own demat account rather than pooled, you see every transaction, and your tax position is your own. A fund is far cheaper, has a much lower minimum and creates no tax event when it rebalances. The PMS has to add enough value to overcome all three differences.
Do I approve each trade?
No — that is what makes it discretionary. The manager decides and executes within the agreed mandate. If you want to approve each decision, a non-discretionary service is the corresponding structure.
Why does turnover matter so much?
Because every rebalancing trade realises gains in your own name and is taxable. A high-turnover strategy has a real tax cost to you that an equivalent mutual fund investor does not bear, and it should be part of how you assess the manager.
How should I evaluate a PMS manager?
On process and on drawdown behaviour rather than on returns over a favourable period. How the portfolio was constructed, how concentrated it was, and what happened in the worst year are more informative than a headline number.
Is outperformance guaranteed?
No. Nothing in equity investing is guaranteed, and professional management does not change that. Equity investments carry market risk, values can fall, and past performance does not indicate future returns.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.