
Get Expert Guidance
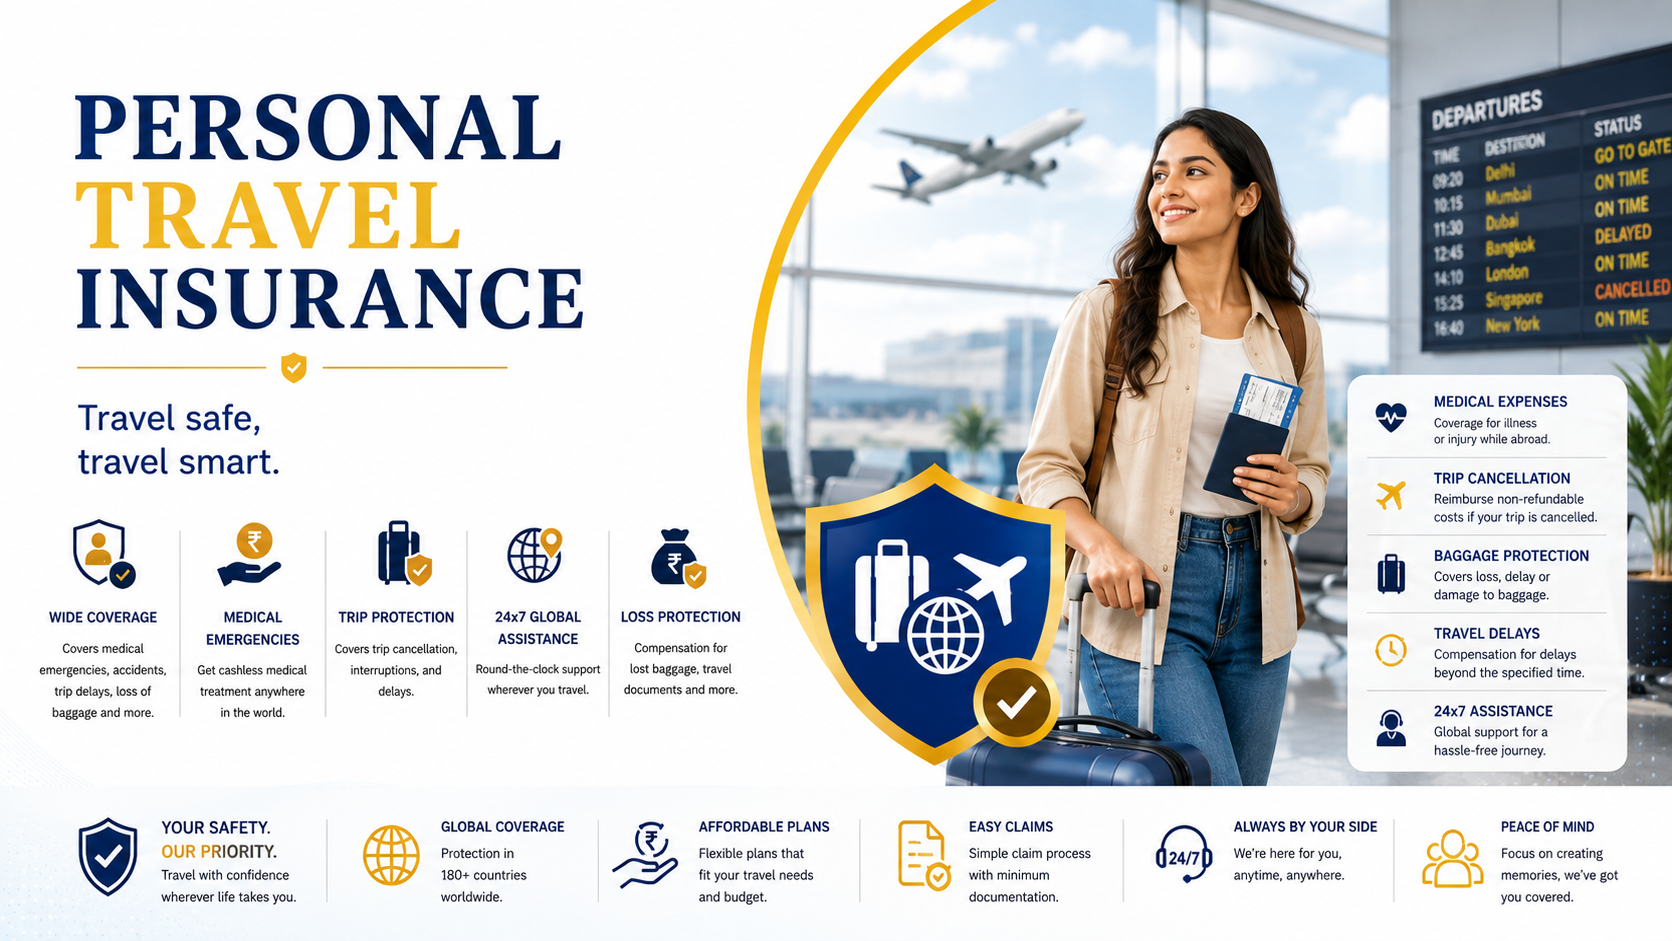
What Our Plans Cover
-
Emergency medical expenses and hos...
-
Emergency dental treatment for acu...
-
Medical evacuation to the nearest...
-
Repatriation of remains
-
Trip cancellation
-
Checked baggage loss and delay
-
Loss of passport and emergency doc...
-
Personal liability to third partie...
Who Can Consider This Plan?
- Valid passport, and a visa where the destination requires one
- Age within the plan limits, commonly 6 months to 70 years for standard plans
- Policy purchased before departure from India
- Full disclosure of pre-existing conditions and planned activities
- Trip duration within the maximum permitted by the plan
What May Not Be Covered?
- Pre-existing conditions, unless specifically declared and accepted
- Treatment that was the purpose of the trip
- Adventure and hazardous sports, unless the extension is purchased
- Incidents involving alcohol or drugs
- Travel against medical advice
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
An individual travel policy covers one person for one trip. It is priced on destination, duration and age, and the overwhelming majority of its value sits in one component: emergency medical treatment abroad.
The reason is arithmetic. Lost baggage costs you a few thousand rupees of inconvenience. An emergency admission in North America or Western Europe can run to tens of lakhs, and no Indian health policy responds to it. That single exposure justifies the premium several times over.
Everything else the policy does — baggage, delay, cancellation, passport loss, personal liability — is genuinely useful and financially secondary. Buy on the medical limit and treat the rest as included.
Who should consider it
Every traveller leaving India, without exception. For business travellers with frequent departures, an annual multi-trip policy is usually cheaper than three single-trip ones — but some cover, always.
Benefits
- Emergency medical treatment abroad at limits no domestic policy provides
- Cashless treatment through a global assistance network
- Emergency evacuation and repatriation, which can cost more than the treatment
- Trip cancellation and curtailment for covered reasons
- Baggage loss and delay, and loss of passport
- Personal liability cover abroad
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Emergency medical expenses and hospitalisation abroad
- Emergency dental treatment for acute pain
- Medical evacuation to the nearest suitable facility
- Repatriation of remains
- Trip cancellation, curtailment and missed connection, for covered reasons
- Checked baggage loss and delay
- Loss of passport and emergency document replacement
- Personal liability to third parties abroad
Typically not covered
- Pre-existing conditions, unless specifically declared and accepted
- Treatment that was the purpose of the trip
- Adventure and hazardous sports, unless the extension is purchased
- Incidents involving alcohol or drugs
- Travel against medical advice
- Unattended baggage and cash left in checked luggage
- Cancellation for reasons outside the policy's listed causes
- Trips beyond the maximum duration stated in the policy
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 Tell us where, how long, and who is going Destination, dates, ages and any medical history. Destination decides the sum insured; age and history decide the premium.
- 2 We match the cover to the visa and the country Schengen has a minimum medical requirement. The US has no minimum and the highest costs. Both need answering properly.
- 3 Declare conditions and activities before you buy A pre-existing condition or a scheduled trek changes the policy. Declaring it costs a little; not declaring it costs the claim.
- 4 Policy issued the same day, usually within the hour Certificate and emergency numbers by email, in the format embassies accept.
- 5 One number to call from anywhere You call the assistance line first, before treatment. That call is what makes a claim cashless rather than a reimbursement fight.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Call the assistance number before you receive treatment. That single call is the difference between a cashless admission and a reimbursement claim you have to fund yourself.
- Declare pre-existing conditions. An undeclared condition is the leading cause of declined travel medical claims, and an unrelated diagnosis rarely rescues the argument.
- Match the medical limit to the destination. USD 50,000 is thin in the United States and generous in South-East Asia.
- Keep every receipt, boarding pass and property irregularity report. Travel claims are lost on documentation more often than on cover.
- If you plan to trek, dive, ski or ride, buy the adventure extension. Standard policies exclude these outright.
Documents required
- Passport copy of every traveller
- Travel dates and itinerary
- Visa, where already issued
- Declaration of any pre-existing medical conditions
- Details of any adventure or sporting activities planned
- Student visa and university admission letter, for student policies
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.