
Plan your investment
What Our Plans Cover
-
Professional stock selection and p...
-
Execution through your own demat a...
-
Periodic reporting of holdings and...
-
Rebalancing as the manager judges...
-
Direct receipt of dividends and co...
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, through a portfolio investment scheme account
- PAN and completed KYC
- A demat account with a registered depository participant
- A trading account with a registered broker
What May Not Be Covered?
- Any guarantee of return or of outperformance
- Protection against market falls
- Suitability below the stated minimum investment
- Pooling of gains and losses, which is a feature of funds
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
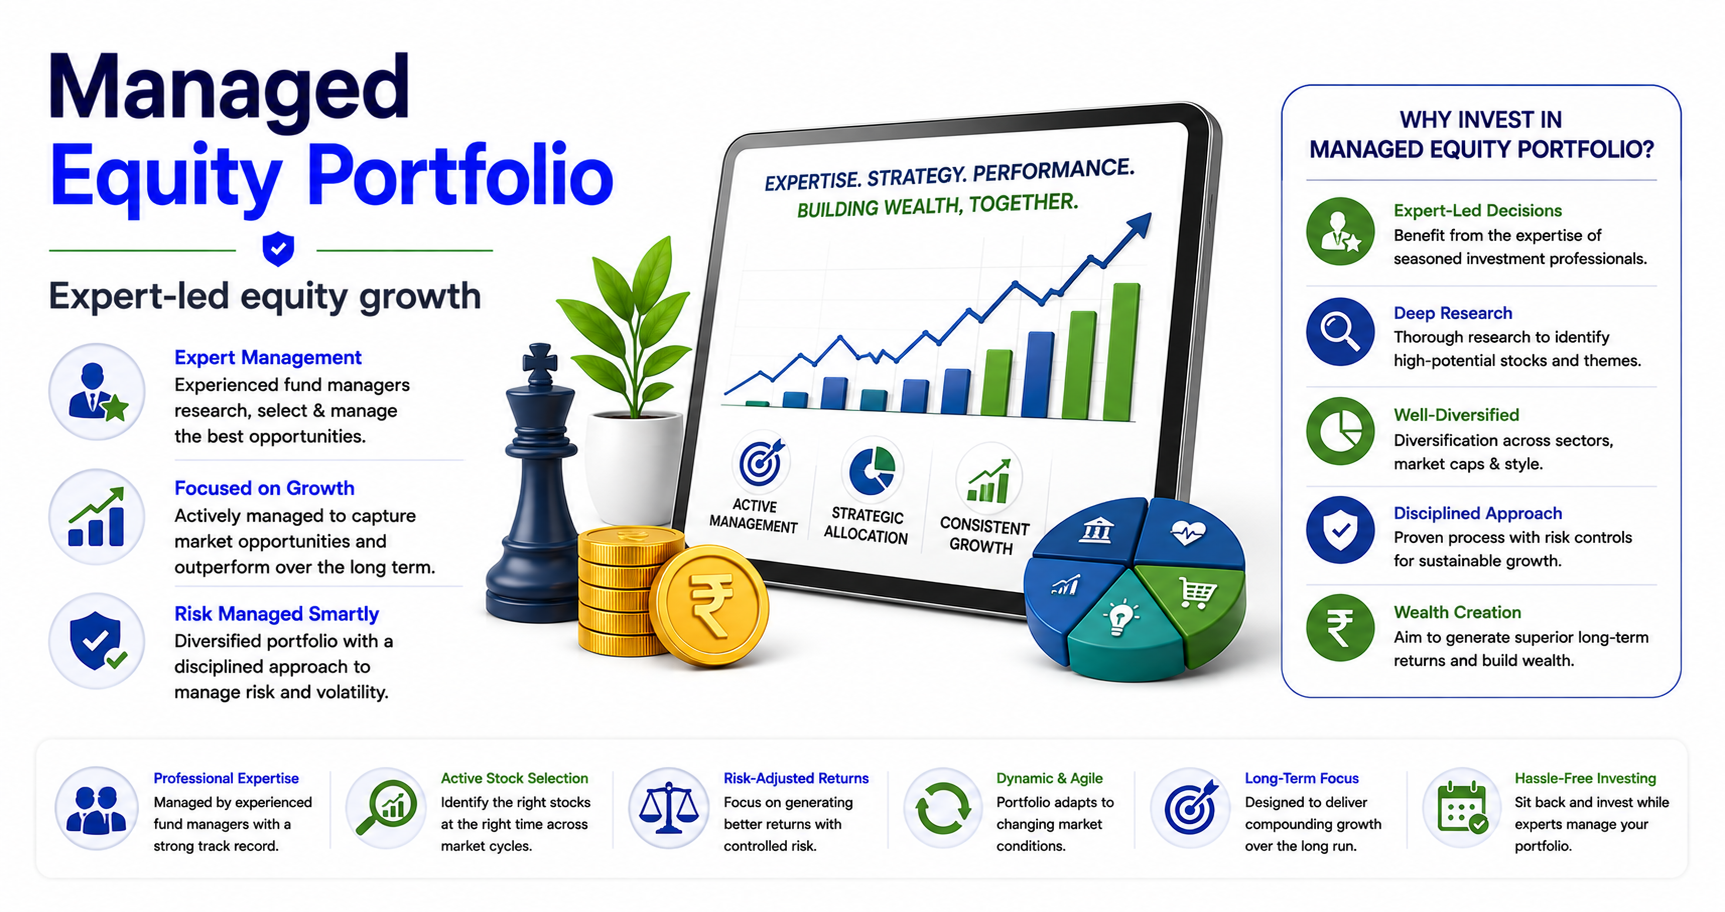
A managed equity portfolio places direct stock selection in professional hands while the shares remain in your own demat account. It sits between doing it yourself and buying a mutual fund: you get individual ownership and a portfolio built around your circumstances, with research and execution handled for you.
The practical differences from a fund are transparency and tax. You see every holding and every transaction, rather than a monthly disclosure. And because gains are realised in your own account, your tax position is your own rather than pooled with other investors'.
The cost structure is different too, typically a management fee on assets and sometimes a performance element. Those fees are visible rather than embedded in a net asset value, which makes them easier to evaluate — and worth evaluating, because on a smaller portfolio they can outweigh the benefit.
Who should consider it
Investors with a substantial equity allocation who want direct ownership and professional management. Investors with specific constraints — sectors to avoid, existing concentrated holdings — that a fund cannot accommodate.
Investors below the minimum, or without particular constraints, are usually better served by a diversified mutual fund at a fraction of the cost.
Benefits
- Shares held directly in your own demat account
- Full transparency of every holding and transaction
- Portfolio built around your constraints and circumstances
- Your tax position is your own, not pooled
- Professional research and execution
- Ability to exclude sectors or accommodate existing holdings
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Professional stock selection and portfolio construction
- Execution through your own demat and trading account
- Periodic reporting of holdings and performance
- Rebalancing as the manager judges appropriate
- Direct receipt of dividends and corporate actions
Not included
- Any guarantee of return or of outperformance
- Protection against market falls
- Suitability below the stated minimum investment
- Pooling of gains and losses, which is a feature of funds
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 We establish whether direct equity suits you at all For many investors a diversified fund does the same job with less to go wrong. That conversation comes before anything else.
- 2 Allocation set before any stock is discussed How much of your portfolio belongs in direct equity, and what stays in funds and fixed income. Position sizing prevents most permanent damage.
- 3 Demat and trading account set up properly KYC, nomination and the mandates. Done once, correctly, so nothing stalls when you want to transact.
- 4 Research shared, decisions left with you We provide analysis and context. We do not provide tips, and we will not tell you a stock will go up.
- 5 Reviewed against the thesis, not the price The question at review is whether the reason you bought still holds — not whether the price has moved since.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Total the fees in rupees over a realistic period and compare against a diversified fund. On smaller portfolios the cost difference is difficult to justify.
- Direct ownership means every rebalancing trade is a taxable event in your hands. Higher portfolio turnover has a direct tax cost that a fund investor does not bear in the same way.
- Ask how the manager has behaved in a bad year, not what returns they achieved in a good one. Drawdown behaviour is more informative than headline performance.
- Understand the performance fee structure if there is one, including the benchmark and any high-water mark. These vary considerably.
- Equity investments are subject to market risk. Professional management does not remove the possibility of loss, and past performance does not indicate future returns.
Documents required
- PAN card, mandatory for all securities transactions
- Aadhaar or other identity proof
- Address proof
- Bank account proof — cancelled cheque or statement
- Income proof, for derivatives segment activation
- Recent passport-size photograph
- Signature specimen and in-person verification
Frequently Asked Questions
How is this different from a mutual fund?
The shares are in your own demat account rather than pooled, you see every holding and transaction, and your tax position is your own. A fund is cheaper, has a much lower minimum and requires no involvement. The managed route earns its cost where you need direct ownership or specific constraints accommodated.
What does it cost?
Typically a management fee on assets, sometimes with a performance element. Unlike a fund's expense ratio, these are visible rather than embedded — which makes them easier to evaluate, and worth evaluating, because on a smaller portfolio they can outweigh the benefit.
Does higher turnover cost me anything?
Yes. Every rebalancing trade realises gains in your own name and is taxable, which a fund investor does not bear in the same way. Ask about expected turnover, because it has a direct tax cost to you.
How should I evaluate a manager?
On how the portfolio behaved in a bad year rather than on returns in a good one. Drawdown behaviour, concentration and the consistency of the process tell you more than headline performance, which is heavily influenced by the period chosen.
Is outperformance guaranteed?
No. Nothing in equity investing is guaranteed, professional management included. Equity investments are subject to market risk, values can fall, and past performance does not indicate future returns.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.