
Get Expert Guidance
What Our Plans Cover
-
Theft of insured property followin...
-
Theft following forcible and viole...
-
Damage to the premises caused duri...
-
Damage to safes and strongrooms du...
-
Money in a locked safe
-
Scheduled valuables
-
Theft accompanied by violence or t...
Who Can Consider This Plan?
- Legal ownership, or an insurable interest such as a lease
- Property of permanent construction, meeting the insurer's standards
- Accurate declaration of occupancy and use
- Sum insured set on a defensible valuation basis
- Compliance with any fire safety requirements applicable to the premises
What May Not Be Covered?
- Theft without evidence of forcible entry or exit
- Shoplifting and theft during business hours
- Employee theft, unless a fidelity guarantee is in force
- Theft using a duplicate or stolen key without force
- Unexplained inventory shortages
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
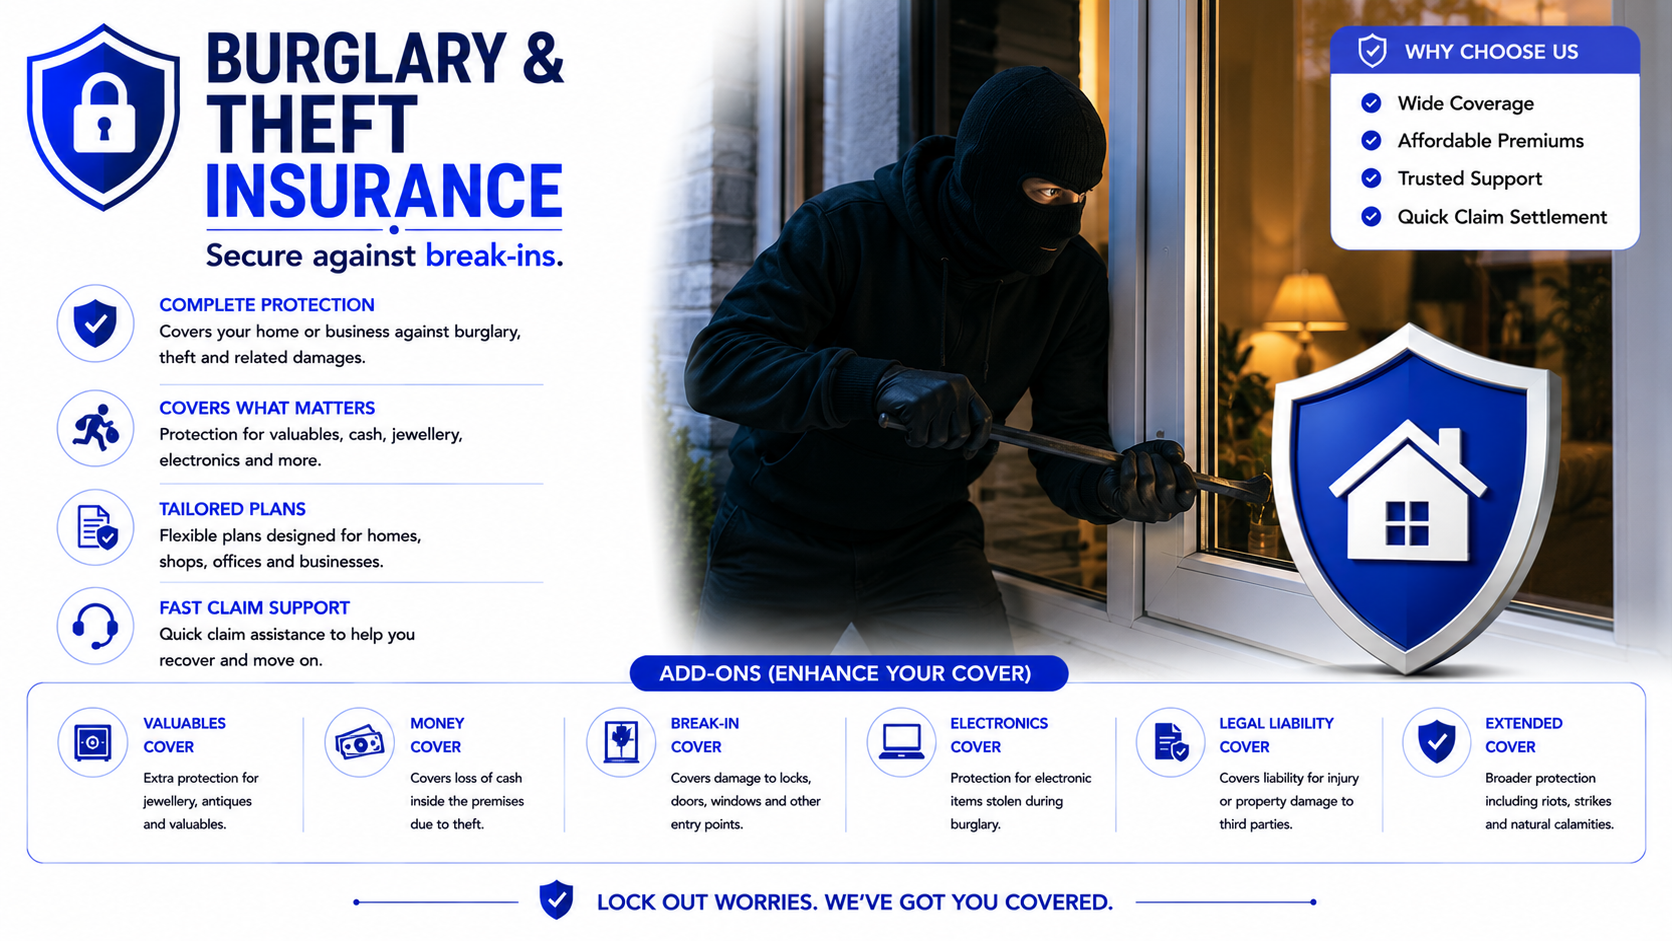
Burglary insurance covers the loss of property from your premises by theft involving forcible and violent entry or exit, and damage to the premises caused during that entry. That definition is the whole product, and it is where nearly every dispute begins.
Theft without forcible entry is not burglary. Shoplifting, a walk-in theft during business hours, an employee taking stock, a duplicate key used quietly — none of these trigger the policy however real the loss is.
That is not a defect in the cover; it is the definition of the peril. It simply means burglary insurance has to be understood alongside the covers that address the other kinds of theft: fidelity guarantee for employees, and money cover for cash.
Who should consider it
Businesses holding stock, cash or portable valuables. Shops, warehouses, jewellers, pharmacies and offices with valuable equipment. Households insuring contents against burglary as part of a home policy.
Benefits
- Covers stock, contents and equipment against forcible theft
- Damage to the premises during break-in is covered
- Can be written on a first-loss basis, reducing premium
- Valuables can be scheduled individually
- Cover for money in a safe, within stated limits
- Premium responsive to security measures installed
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Theft of insured property following forcible and violent entry
- Theft following forcible and violent exit
- Damage to the premises caused during the break-in
- Damage to safes and strongrooms during an attempted theft
- Money in a locked safe, up to the stated limit
- Scheduled valuables, where declared
- Theft accompanied by violence or threat to a person
Typically not covered
- Theft without evidence of forcible entry or exit
- Shoplifting and theft during business hours
- Employee theft, unless a fidelity guarantee is in force
- Theft using a duplicate or stolen key without force
- Unexplained inventory shortages
- Property left in unattended or unsecured premises
- Money outside the safe beyond the stated limit
- Theft during a period the premises were unoccupied beyond the stated limit
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 We value the risk before we quote it Reinstatement cost of the structure, current value of the contents, and what a total loss would actually cost to rebuild today.
- 2 Perils matched to the location A coastal warehouse, a basement in a flood-prone city and a first-floor office are three different risks. The policy should reflect which one you are.
- 3 Quotes compared on sum insured basis, not premium Market value against reinstatement value changes what you receive far more than the premium difference between insurers.
- 4 Survey where the value warrants it Larger risks are surveyed before cover. It is also the moment to fix anything that would reduce a claim later.
- 5 Policy issued, and reviewed annually We revisit the sum insured every renewal. Under-insurance is the single most common reason property claims are cut.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Forcible entry is the whole test. Keep the premises secured and report every break-in to the police immediately — the FIR is the primary evidence a claim depends on.
- Employee theft needs fidelity guarantee cover. It is a common loss and it is expressly outside this policy.
- A first-loss basis insures a realistic maximum single loss rather than the full stock value, and can cut the premium substantially for a large warehouse.
- Security investment reduces premium. Grilles, shutters, alarms and monitored CCTV are rating factors, not just deterrents.
- Watch the unoccupancy clause. Premises closed for an extended period — a long festival shutdown, for instance — can fall outside cover.
Documents required
- Proof of ownership or the lease agreement
- Details of construction — age, materials, number of floors
- Valuation or reinstatement cost estimate of the structure
- Inventory and value of contents, stock or equipment
- Details of fire protection and security arrangements
- Previous policy and claims history, where applicable
- Photographs of the premises, for larger risks
Frequently Asked Questions
What exactly does "forcible entry" mean?
Visible evidence that someone broke in or broke out — a forced shutter, a cut grille, a damaged lock. Without it the loss is theft rather than burglary, and this policy does not respond. It is the single most important term in the contract.
Is shoplifting covered?
No. Shoplifting happens without forcible entry, during business hours, and is treated as a trading loss. Retailers manage it through controls and stock management rather than through insurance.
What if an employee steals from us?
Not covered here. Employee dishonesty requires a fidelity guarantee policy, which is a separate cover and worth considering for any business where staff handle stock or cash.
Someone used a copied key. Are we covered?
Generally not, because there is no forcible entry. Some policies extend to theft by a person who remained hidden on the premises, but a quiet entry with a duplicate key normally falls outside the cover.
What is a first-loss basis?
You insure a realistic maximum single loss rather than your total stock value — recognising that a burglar cannot remove an entire warehouse in one night. It reduces premium substantially and is the standard approach for large stock holdings.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.