
Get Expert Guidance
What Our Plans Cover
-
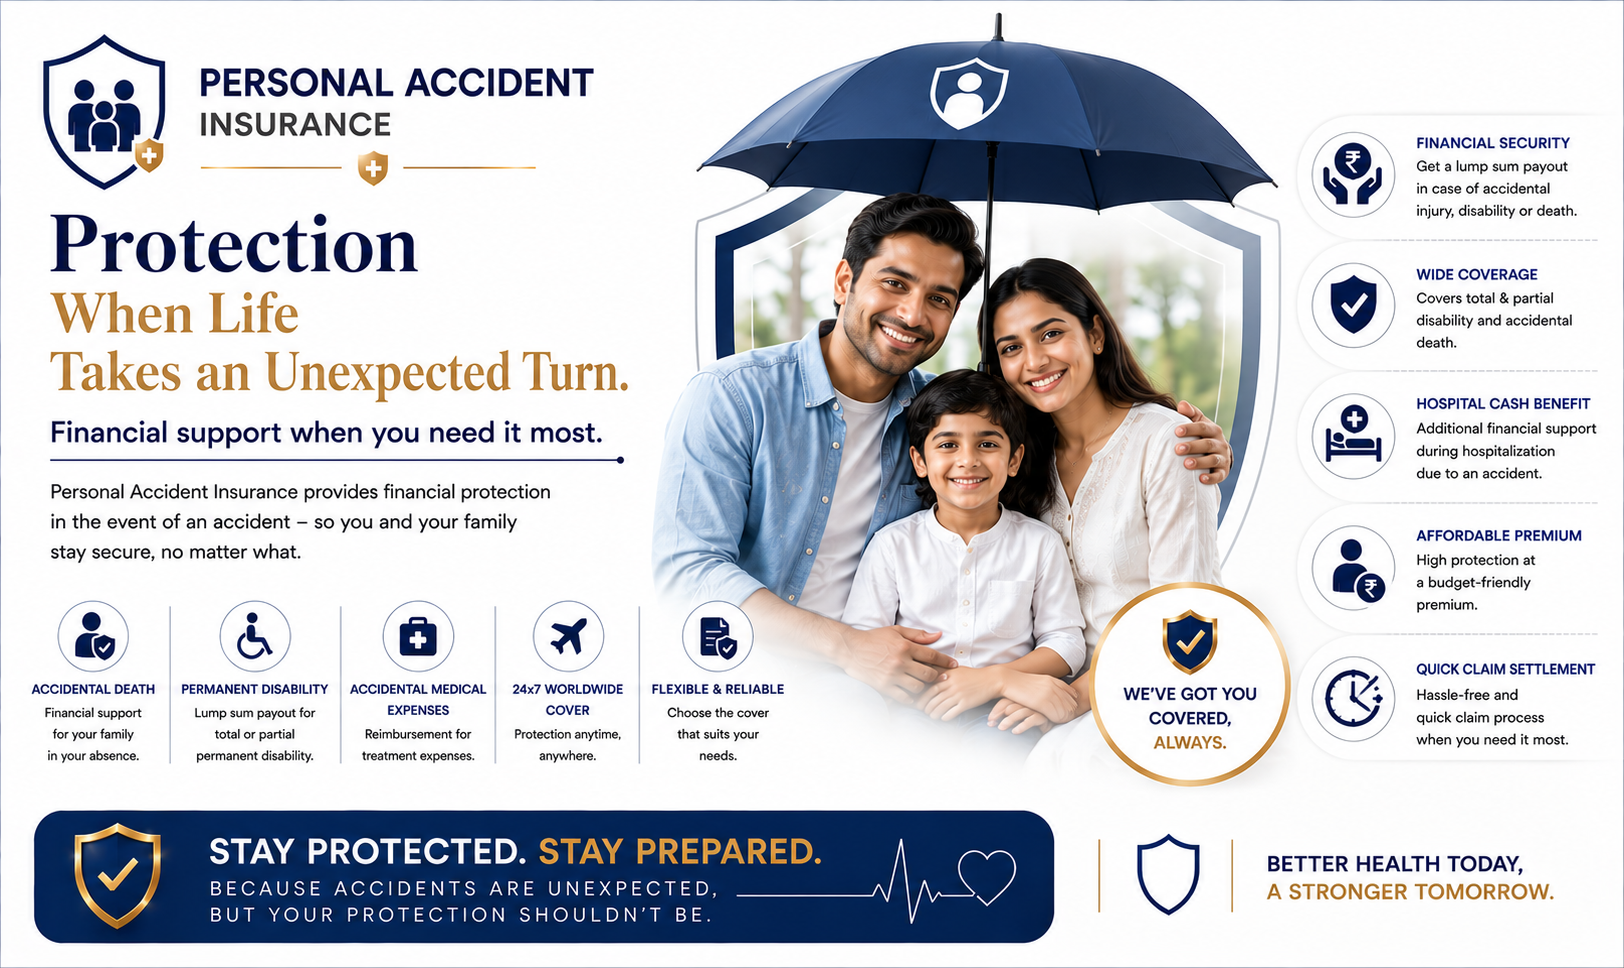
Accidental death
-
Permanent total disablement
-
Permanent partial disablement
-
Temporary total disablement
-
Accidental hospitalisation expense...
-
Ambulance charges following an acc...
-
Children's education grant on deat...
-
Funeral expenses
Who Can Consider This Plan?
- Indian resident, typically aged 18 to 65 at entry
- Children can usually be covered from 91 days, subject to insurer rules
- Medical tests may be required above a threshold age or sum insured
- Full and accurate disclosure of existing conditions, medication and family history
- Tobacco and alcohol use must be declared — non-disclosure is the leading cause of rejected claims
What May Not Be Covered?
- Death or disablement from illness rather than accident
- Self-inflicted injury and suicide
- Accidents while under the influence of alcohol or drugs
- Injury while committing a criminal act
- Adventure and hazardous sports, unless specifically covered
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
A personal accident policy pays on death or disablement caused by an accident. It is inexpensive because accidents, unlike illness, are not correlated with age or medical history — which is also why a healthy thirty-year-old can hold a very large sum insured for a very small premium.
The cover that matters most here is permanent total disablement. Death is catastrophic but final; permanent disablement means income stops while costs rise, often for decades. A well-constructed accident policy pays the full sum insured in that event, and a proportion of it for defined partial disablements.
Many buyers already hold some accident cover inside a motor policy or a group scheme, but those are usually small and narrow. A standalone policy covers you everywhere, around the clock, not only in a vehicle or at work.
Who should consider it
Anyone who earns. It is the cheapest meaningful cover available in the Indian market, and the risk it addresses is entirely independent of the health risks your other policies handle.
It is particularly important for people who travel frequently by road, work in physical trades, ride two-wheelers daily, or are self-employed with no employer scheme behind them. It is also the sensible companion to a term plan for a young earner, because it covers the disability scenario that a term plan does not.
Benefits
- Very large sums insured for a very small premium
- Premium is largely independent of age and medical history
- Permanent total disablement pays the full sum insured
- Cover applies worldwide and around the clock, not only at work or in a vehicle
- Weekly compensation for temporary total disablement on most plans
- Education benefit for children and funeral expenses on many plans
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Accidental death — the full sum insured
- Permanent total disablement — usually the full sum insured
- Permanent partial disablement — a defined percentage by body part
- Temporary total disablement — a weekly benefit for a limited number of weeks
- Accidental hospitalisation expenses, where the plan includes them
- Ambulance charges following an accident
- Children's education grant on death or permanent disablement
- Funeral expenses, a small fixed amount on most plans
Typically not covered
- Death or disablement from illness rather than accident
- Self-inflicted injury and suicide
- Accidents while under the influence of alcohol or drugs
- Injury while committing a criminal act
- Adventure and hazardous sports, unless specifically covered
- War, invasion and nuclear risks
- Pre-existing disablement
- Accidents while flying other than as a fare-paying passenger
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 Tell us who is being covered Age, city, existing conditions and any cover you already hold. Two minutes, and it decides everything downstream.
- 2 We shortlist on structure, not price Room rent, co-payment, sub-limits and pre-existing waiting periods — the four things that decide what you actually get paid.
- 3 You see two or three options, with the trade-offs named Including what each one gives up. If your existing policy is already the right answer, we will tell you that.
- 4 Proposal and medicals We help you complete disclosure properly. A medical test, where required, is usually arranged at home.
- 5 Policy issued, and we stay on the file At claim time you call us, not a helpline. We prepare the file, submit it and chase the insurer until it settles.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Occupation class drives both premium and acceptance. Declare your actual work, including site visits or riding a two-wheeler for work, rather than a tidier job title.
- The disablement percentage table is the substance of the policy. Two plans with the same sum insured can pay very different amounts for the same injury.
- Accident cover attached to a motor policy applies to the owner-driver in that vehicle. It is not a substitute for a standalone policy that covers you everywhere.
- Check whether the plan covers accidental hospitalisation. Some pay only the lump sums and leave treatment costs to your health policy.
- If you ride regularly, take part in adventure sports or travel constantly by road, say so. Silence is cheap at proposal and expensive at claim.
Documents required
- Completed proposal form with full medical disclosure
- Identity proof — Aadhaar, passport, voter ID or driving licence
- Address proof
- PAN card
- Recent passport-size photograph
- Medical reports, where the insurer requires them at your age or sum insured
- Existing policy copy, if you are porting
Frequently Asked Questions
How is this different from term insurance?
A term plan pays on death from any cause but generally pays nothing if you survive with a permanent disability. A personal accident policy pays on accidental death and, importantly, on permanent disablement — the scenario where income stops and costs rise at the same time. They cover different halves of the same problem.
Doesn't my motor policy already include accident cover?
It includes a compulsory owner-driver personal accident cover, which is limited in amount and applies to that vehicle. It is a floor, not a plan. A standalone policy covers you at home, at work, on foot and abroad, at a sum insured you choose.
Why is the premium so low?
Because accident risk is far less correlated with age and health than illness risk is, and because claims are less frequent than health claims. It is the reason a large sum insured is affordable here in a way it never is on a health policy.
What counts as permanent total disablement?
The policy defines it precisely — typically loss of both limbs, sight in both eyes, or a combination specified in the schedule, and sometimes total inability to follow any occupation. Read that definition and the accompanying percentage table before comparing plans on price.
Are two-wheeler accidents covered?
Yes, under an ordinary policy, provided you were riding lawfully and were not under the influence. If riding is central to your work, declare it — occupation class affects both the premium and whether the claim is accepted.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.