
Plan your investment
What Our Plans Cover
-
Investment in a fund domiciled in...
-
Foreign currency denominated parti...
-
Global and Indian investment manda...
-
Periodic valuation and investor re...
-
Participation through a contributi...
Who Can Consider This Plan?
- Minimum commitment of ₹1 crore per investor, as regulated
- Indian resident individual, HUF, trust, company or NRI
- Completed KYC with the fund
- Ability to meet capital calls through the drawdown period
- Acceptance by the fund manager, which is discretionary
What May Not Be Covered?
- Unrestricted participation by resident investors, which follows remittance rules
- Any guarantee of return
- A fully settled regulatory framework, which continues to develop
- Liquidity before the fund's realisation period
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
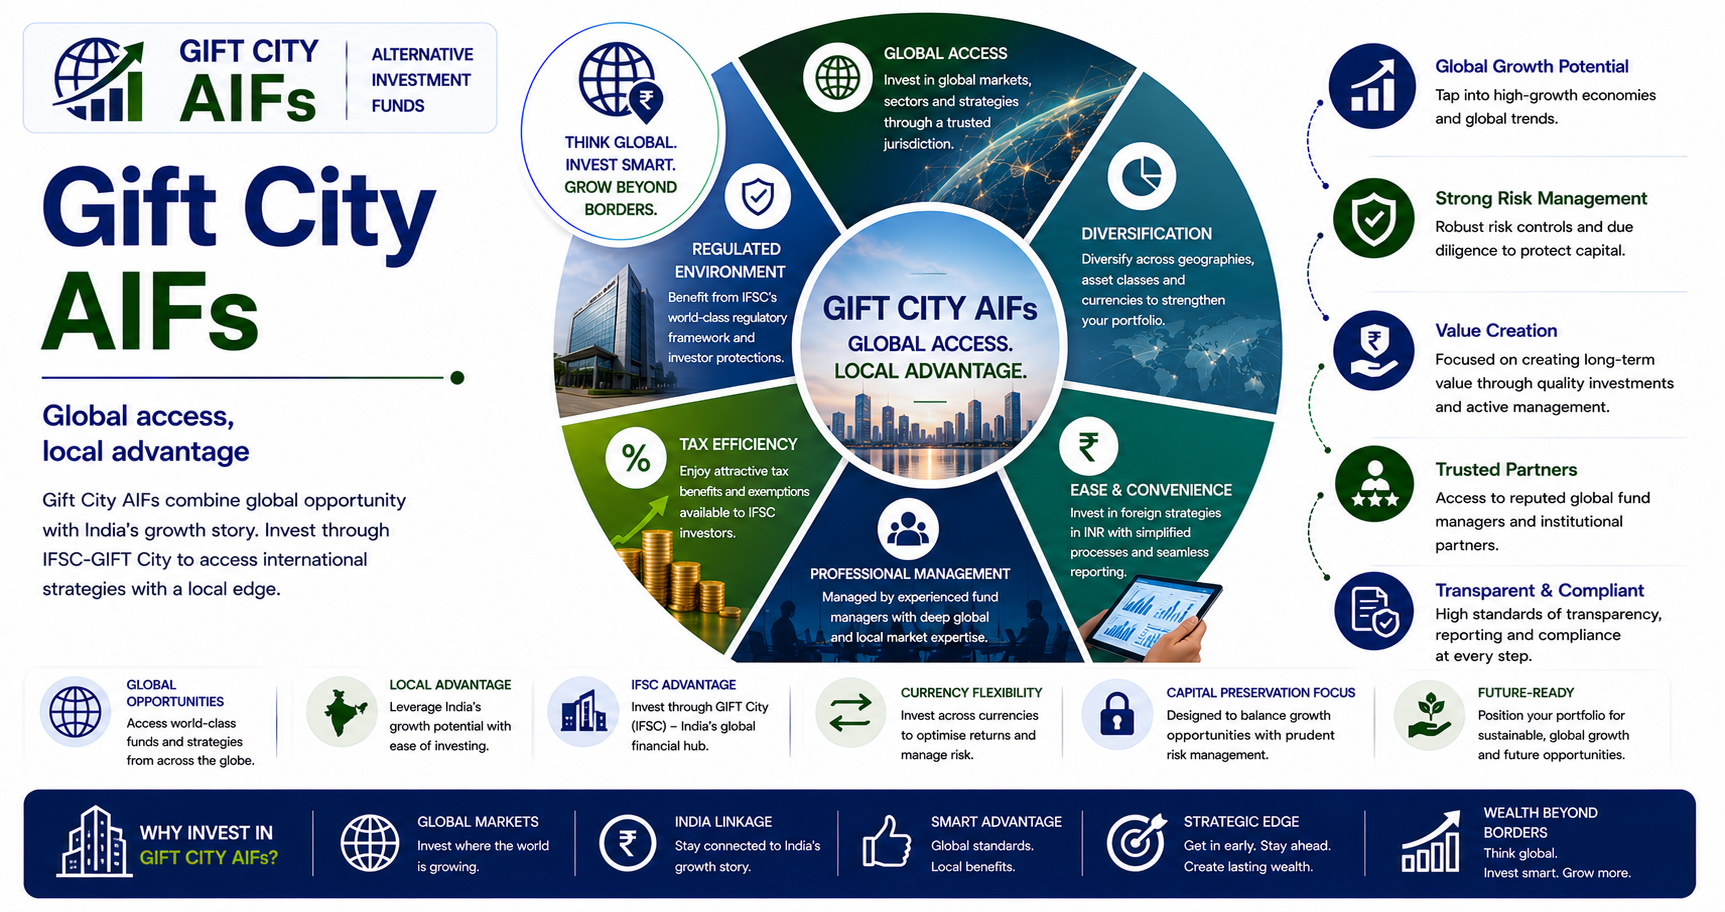
GIFT City is India's international financial services centre, operating under a separate regulatory and tax framework from the domestic market. Funds domiciled there can be denominated in foreign currency and can invest globally without the constraints that apply to domestic funds.
For non-resident investors the attraction is a familiar structure in a jurisdiction with tax concessions, without the complications of investing through the domestic Indian regime. For resident investors, participation is subject to the applicable remittance rules.
The regime is relatively new and continues to develop. Tax concessions, permitted activities and operational frameworks have evolved several times, and while the direction has been consistently supportive, the framework is less settled than the domestic one.
Who should consider it
Non-resident investors seeking Indian or global exposure through a favourable jurisdiction. Investors wanting foreign currency denominated funds. Family offices structuring international allocations.
Benefits
- Tax concessions available under the IFSC framework
- Foreign currency denomination available
- Ability to invest globally without domestic constraints
- A familiar structure for non-resident investors
- Regulated by the International Financial Services Centres Authority
- Simpler route for non-residents than domestic Indian structures
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Investment in a fund domiciled in the IFSC
- Foreign currency denominated participation
- Global and Indian investment mandates
- Periodic valuation and investor reporting
- Participation through a contribution agreement
Not included
- Unrestricted participation by resident investors, which follows remittance rules
- Any guarantee of return
- A fully settled regulatory framework, which continues to develop
- Liquidity before the fund's realisation period
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 We start with whether an AIF suits you at all A one-crore minimum, multi-year lock-ins and higher fees. If a mutual fund does the same job, we will say so.
- 2 Category and strategy matched to the objective Category I, II and III are genuinely different things. Choosing between them is the substantive decision.
- 3 Fees and terms read in full Management fee, carry, hurdle rate, catch-up and drawdown schedule. These vary enormously and compound over a fund's life.
- 4 Commitment and drawdown planned You commit capital that is called over time. Liquidity has to be arranged for calls you cannot decline.
- 5 Reporting tracked through the fund life Valuations are periodic and taxation differs by category. We keep the reporting straight through to wind-up.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- For residents, participation runs through the Liberalised Remittance Scheme and its annual limit. That constrains how much can be committed.
- Tax concessions have specific conditions attached. Confirm how they apply to your own residency and circumstances rather than assuming the headline position.
- The framework continues to evolve. The direction has been supportive, but it is less settled than the domestic regime.
- Foreign currency denomination introduces currency exposure for a rupee-based investor. That is a separate source of return and risk.
- Assess the fund and manager on the same terms as any other AIF. The jurisdiction is a wrapper, not a strategy.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Demat account details
- Bank account proof
- Net worth or income evidence, where the fund requires it
- Completed KYC and contribution agreement
Frequently Asked Questions
What is GIFT City?
India's international financial services centre, operating under a separate regulatory and tax framework from the domestic market and regulated by the IFSCA. Funds domiciled there can be foreign currency denominated and can invest globally without the constraints applying to domestic funds.
Can a resident Indian invest?
Yes, subject to the Liberalised Remittance Scheme and its annual limit. That constrains how much can be committed and makes it a more natural route for non-residents, for whom the structure was primarily designed.
What are the tax advantages?
The IFSC framework carries concessions, with conditions attached that depend on the fund structure and the investor's residency. Confirm how they apply to your own circumstances rather than relying on the headline position, because the detail matters.
Is the framework stable?
It has evolved several times since inception, consistently in a supportive direction, but it is newer and less settled than the domestic regime. That is worth factoring into a long-dated commitment.
Does the jurisdiction improve the investment?
No. GIFT City is a wrapper providing regulatory and tax treatment; it says nothing about the strategy or the manager. Assess the fund on exactly the same terms as any other AIF, and treat the jurisdiction as a structuring consideration rather than a merit.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.