
Check your eligibility
What These Loans Fund
-
Tuition and course fees paid direc...
-
Hostel and accommodation charges
-
Examination
-
Books
-
A computer where the course requir...
-
Study tours
-
Caution deposit and refundable ins...
Who Can Consider This Loan?
- Indian national admitted to a recognised course
- A co-applicant, generally a parent, guardian or spouse
- Admission secured through a recognised selection process
- Co-applicant income sufficient to support repayment
- Collateral required above the unsecured threshold
- Satisfactory academic record
What May Not Be Funded?
- Courses at unrecognised institutions
- Personal expenses unrelated to the course
- Amounts above the sanctioned limit
- Processing charges, where the lender applies them
- Repeat years, at some lenders
Always check the sanction letter before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading loans companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced loans professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
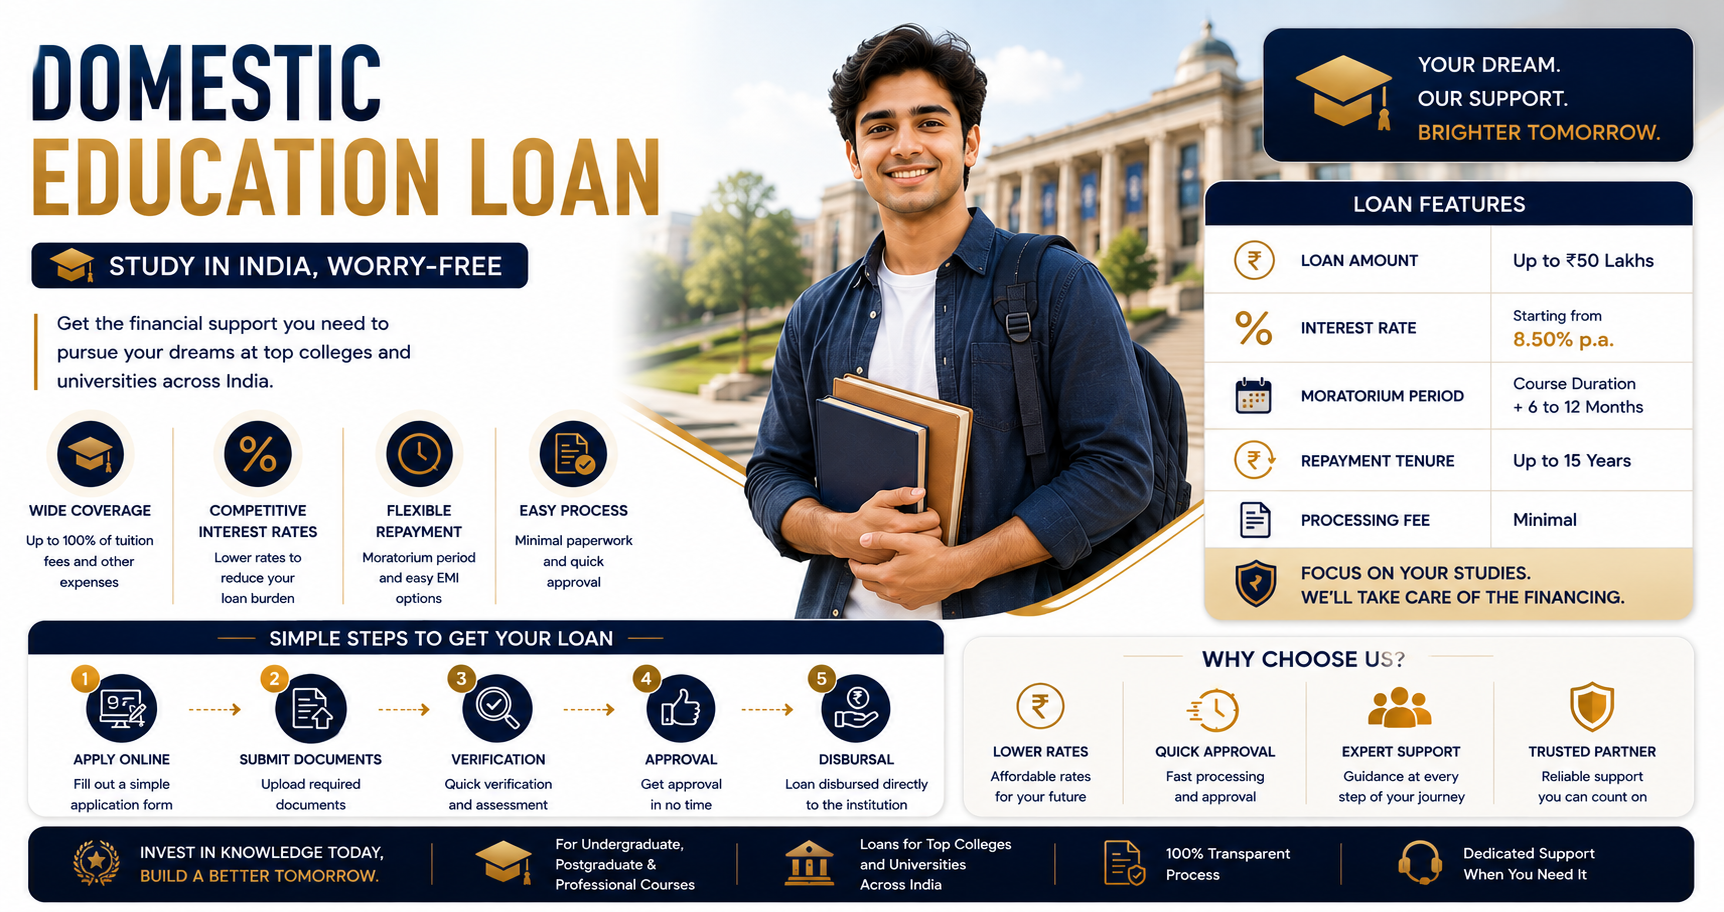
A domestic education loan funds tuition, hostel costs and related expenses for study in India. Repayment does not begin during the course: a moratorium covers the study period plus a further six months to a year while the graduate finds work.
The feature most families do not know about is Section 80E. Interest paid on an education loan is fully deductible with no upper limit, for eight years from when repayment begins. That makes it one of the very few borrowings that is genuinely tax-efficient to hold, and it is a strong argument against clearing it early with savings.
Loans up to a threshold — commonly ₹4 lakh — require no collateral and no third-party guarantee. Above that, security is generally required, and offering it usually reduces the rate enough to be worth doing.
Who should consider it
Students admitted to professional, graduate or postgraduate courses in India. Families who would otherwise liquidate long-term investments. Anyone wanting the student to build a credit record and take responsibility for the funding.
Benefits
- Moratorium covering the course plus six to twelve months
- Section 80E deduction on interest with no upper limit
- No collateral required below the threshold amount
- Concessional rates for girl students at many lenders
- Covers tuition, hostel, books, equipment and examination fees
- Tenure up to fifteen years after the moratorium
What the loan funds, and what it does not
Read the right-hand column first. It is the one that decides how much you have to arrange yourself.
Usually funded
- Tuition and course fees paid directly to the institution
- Hostel and accommodation charges
- Examination, library and laboratory fees
- Books, equipment, instruments and uniforms
- A computer where the course requires one
- Study tours, project work and thesis costs
- Caution deposit and refundable institutional deposits
Usually not funded
- Courses at unrecognised institutions
- Personal expenses unrelated to the course
- Amounts above the sanctioned limit
- Processing charges, where the lender applies them
- Repeat years, at some lenders
Funding limits and the treatment of add-ons vary between lenders and move with the borrower profile. The sanction letter you receive is what governs — we will walk you through it before you sign.
How it works with us
- 1 Start before the admission letter, not after Pre-approval based on the course and the co-applicant's profile means the money is ready when the deadline arrives.
- 2 Course and institution assessed first Lenders rank institutions. A recognised course at a listed institution attracts better terms than the same amount elsewhere.
- 3 Collateral decided deliberately Below the threshold no security is needed. Above it, offering collateral usually reduces the rate enough to be worth it.
- 4 Sanction, and the disbursal schedule agreed Fees release semester by semester directly to the institution. Living costs follow the agreed schedule.
- 5 Moratorium tracked, repayment planned We flag when the moratorium ends and what the EMI becomes, so the first repayment is not a surprise.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Section 80E has no ceiling, unlike almost every other deduction. Before clearing the loan early from savings, compare the after-tax cost of the loan against what those savings earn.
- Interest accrues during the moratorium even though you are not paying. Servicing the interest while studying, where affordable, reduces the eventual EMI substantially.
- Offering collateral above the threshold usually reduces the rate enough to justify it, even where the lender would lend unsecured.
- Check whether your institution is on the lender's approved list. A listed institution attracts materially better terms for the same amount.
- Apply before the admission deadline. Pre-approval based on the course and co-applicant means the fee is ready when it is due.
Documents required
- Admission letter from the institution
- Fee structure and course details from the institution
- Academic records — mark sheets and certificates
- Entrance examination results, where applicable
- Identity and address proof of student and co-applicant
- Co-applicant income proof — salary slips, Form 16 or returns
- Bank statements of the co-applicant for six months
- Collateral documents, where security is offered
Frequently Asked Questions
When does repayment start?
After the moratorium, which covers the course period plus a further six to twelve months. Interest accrues during that time even though you are not paying it, so servicing at least the interest while studying — where the family can afford it — meaningfully reduces the eventual EMI.
What is Section 80E?
A deduction for interest paid on an education loan, available for eight years from when repayment begins, with no upper limit. That absence of a ceiling is unusual and makes an education loan one of the few genuinely tax-efficient borrowings — worth weighing before you clear it early from savings.
Do I need collateral?
Not below the threshold, commonly around four lakh rupees. Above that, security is generally required. Even where a lender will go unsecured, offering collateral usually reduces the rate enough to be worth doing.
Who can be the co-applicant?
Generally a parent, guardian or spouse. Their income and credit profile carry most of the assessment weight, since the student typically has neither at the point of application.
Are there concessions for girl students?
Most lenders offer a rate concession for female students, typically a modest reduction. It is applied on request rather than automatically at some lenders, so it is worth asking explicitly.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.