
Plan your investment
What Our Plans Cover
-
Investment into a diversified equi...
-
Section 80C deduction within the a...
-
SIP or lumpsum investment options
-
Growth and dividend options
-
Redemption after three years from...
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, subject to the fund house accepting the country of residence
- Completed KYC with a registered KYC registration agency
- PAN, which is mandatory for all mutual fund investments
- A bank account in the investor's own name for transactions
What May Not Be Covered?
- Any deduction under the new tax regime
- Withdrawal inside the three-year lock-in, under any circumstances
- Any guarantee of return — this is an equity fund
- Deduction above the ₹1.5 lakh aggregate 80C limit
- Loans against the units during the lock-in
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
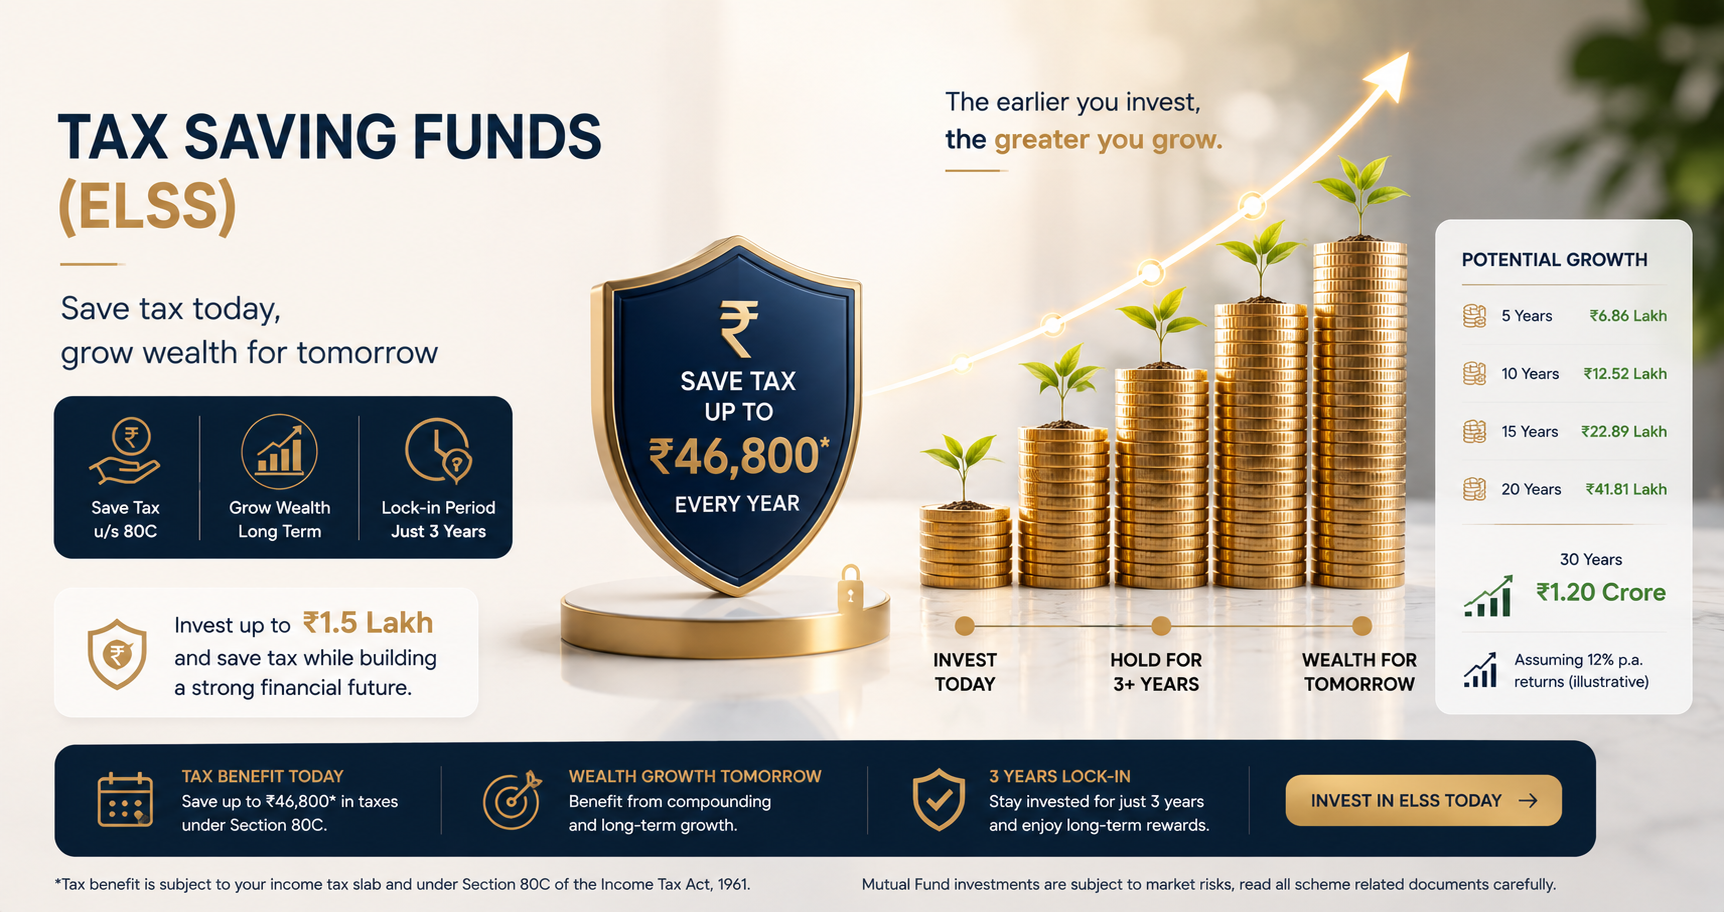
An equity linked savings scheme is an equity mutual fund that qualifies for deduction under Section 80C, with a mandatory three-year lock-in on each investment. It is the shortest lock-in of any 80C instrument — public provident fund runs fifteen years and tax-saving deposits five.
Because it is an equity fund, it carries equity risk. The tax deduction does not change that. An ELSS can fall in value like any equity investment, and the lock-in means you cannot exit while it does.
Under the new tax regime, Section 80C is not available. If you have moved to the new regime, an ELSS offers you nothing an ordinary equity fund does not — and an ordinary fund has no lock-in. That is worth establishing before investing.
Who should consider it
Taxpayers under the old regime with 80C headroom remaining after provident fund and home loan principal. Investors who want equity exposure and a deduction in the same instrument. Younger investors, for whom a three-year lock-in is not a constraint.
Benefits
- Deduction under Section 80C, within the overall limit
- The shortest lock-in of any 80C instrument, at three years
- Full equity participation rather than an administered return
- Available through SIP, so the deduction can be spread across the year
- No maximum investment, though the deduction is capped
- Long-term capital gains treatment on redemption
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Investment into a diversified equity scheme
- Section 80C deduction within the aggregate limit
- SIP or lumpsum investment options
- Growth and dividend options
- Redemption after three years from each instalment
Not included
- Any deduction under the new tax regime
- Withdrawal inside the three-year lock-in, under any circumstances
- Any guarantee of return — this is an equity fund
- Deduction above the ₹1.5 lakh aggregate 80C limit
- Loans against the units during the lock-in
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 Goal and horizon before fund selection What the money is for and when you need it decides the asset class. The fund name is the last decision, not the first.
- 2 Risk profiling that is honest rather than flattering Capacity to take risk and willingness to sit through a fall are different things. We assess both, because the second is what breaks plans.
- 3 Shortlist built on process, not last year's return Mandate, expense ratio, fund manager tenure and how the fund behaved in a bad year. Past performance is not a forecast.
- 4 KYC, onboarding and the first investment One-time KYC, then the folio and the mandate. We set up the SIP so it runs without depending on you remembering.
- 5 Review annually, rebalance deliberately A yearly review against the goal, not a monthly reaction to markets. Most damage in investing is self-inflicted.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Under the new tax regime there is no 80C deduction, which removes the entire reason to accept the lock-in. Run our income tax calculator before investing.
- On an SIP, each instalment has its own three-year lock-in. Money invested in month twelve is locked until month forty-eight, not until month thirty-six.
- Check your remaining 80C headroom first. Provident fund and home loan principal often fill most of the limit already.
- The lock-in is absolute. There is no premature withdrawal for any reason, unlike a PPF which permits limited withdrawals.
- This is an equity fund and is subject to market risk. The deduction reduces your tax; it does not reduce the volatility.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Cancelled cheque or bank account details
- Recent passport-size photograph
- Completed KYC, or KYC documents to complete it
- FATCA and nominee declaration
Frequently Asked Questions
Is ELSS worth it under the new tax regime?
No. Section 80C is not available under the new regime, which removes the only reason to accept a three-year lock-in. If you have moved to the new regime, an ordinary diversified equity fund gives you the same exposure with no lock-in at all.
How does the lock-in work with an SIP?
Each instalment locks separately for three years from its own date. An SIP started in April 2026 has its first instalment free in April 2029 and its twelfth free in March 2030. The whole investment is not free three years after you started.
Can I withdraw early in an emergency?
No. The three-year lock-in is absolute with no premature withdrawal provision for any reason. That is stricter than a PPF, which permits limited withdrawals after a period.
Is ELSS safer than other equity funds because of the tax benefit?
No. It is a diversified equity fund and carries the same market risk as any other. The deduction reduces your tax outgo; it has no effect on how the fund behaves in a falling market. Mutual fund investments are subject to market risk.
How much can I claim?
ELSS counts within the ₹1.5 lakh aggregate Section 80C limit, shared with provident fund, home loan principal, life insurance premium and the rest of that basket. Most salaried taxpayers have less headroom remaining than they assume.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.