
Plan your investment
What Our Plans Cover
-
Investment into a liquid or ultra-...
-
Fixed periodic transfers into the...
-
Weekly
-
Ability to change the amount or st...
-
Redemption of the remaining source...
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, subject to the fund house accepting the country of residence
- Completed KYC with a registered KYC registration agency
- PAN, which is mandatory for all mutual fund investments
- A bank account in the investor's own name for transactions
What May Not Be Covered?
- Any protection against the target fund falling
- Any guarantee of return on either fund
- Tax exemption on transfers, which are redemptions from the source fund
- Transfers between fund houses — both funds must be with the same AMC
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
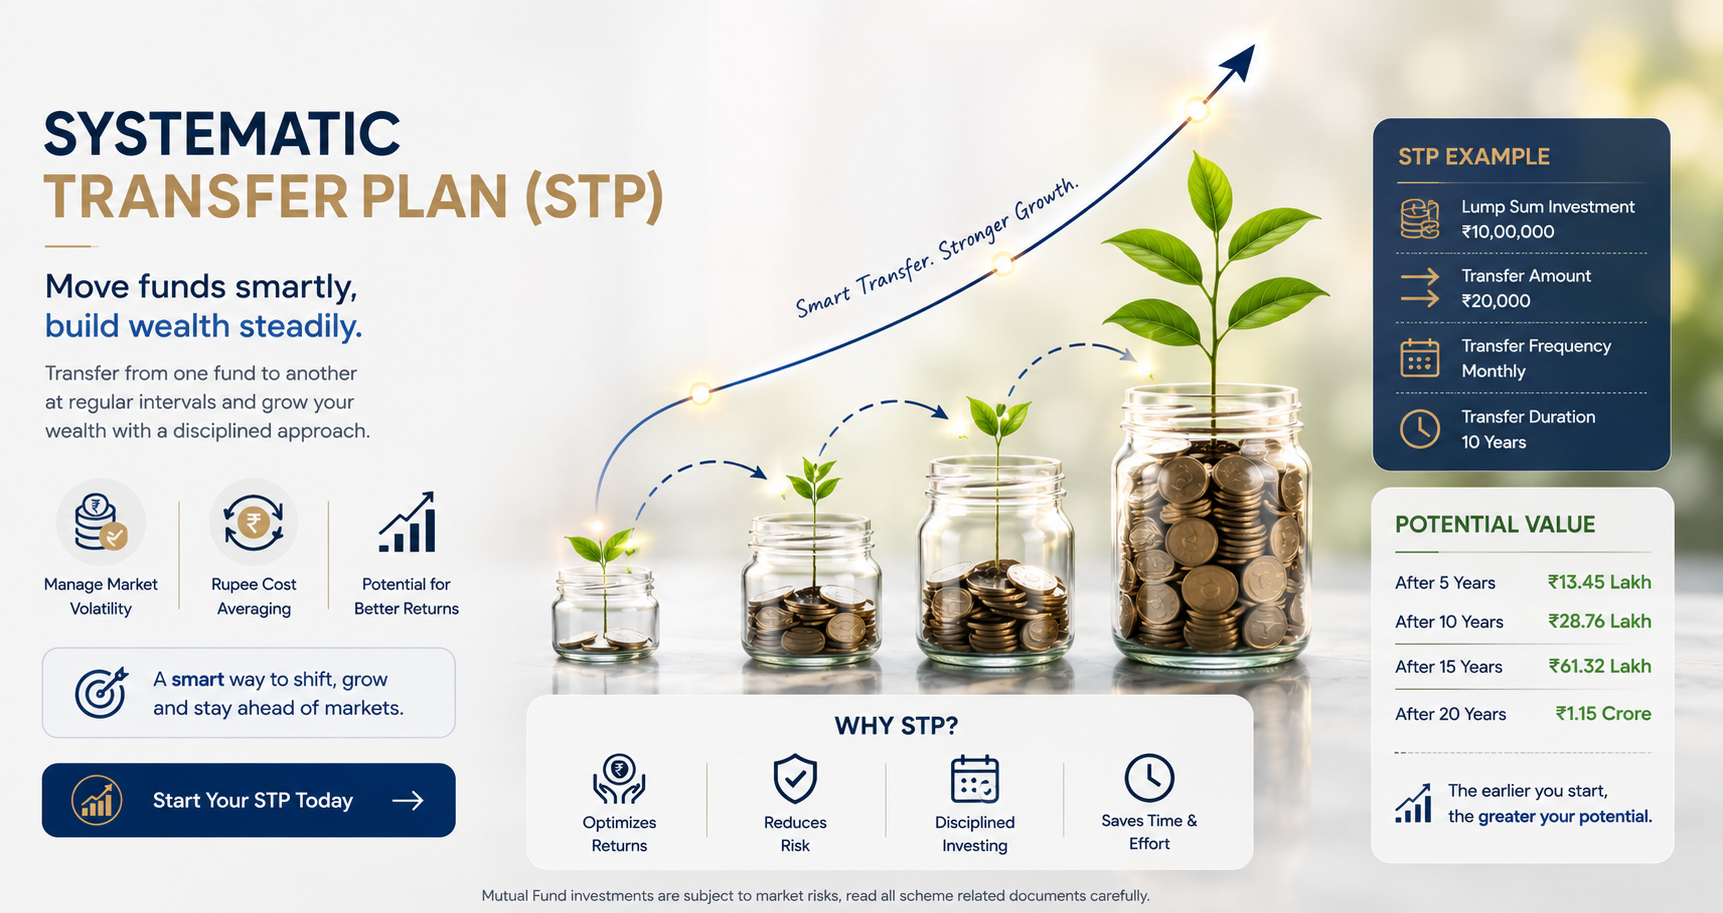
A systematic transfer plan parks a lumpsum in a liquid or ultra-short debt fund and transfers a fixed amount into an equity fund at regular intervals. It is the answer to having a large sum to invest and being uncomfortable deploying it all at one market level.
The advantage over simply holding cash and investing monthly is that the money is earning something in the meantime rather than sitting in a savings account. The advantage over a lumpsum is that entry is averaged across several months rather than concentrated on one day.
Each transfer is a redemption from the source fund, which means it is a taxable event on the gains in that fund. Those gains are usually small on a liquid fund, but the mechanism is worth understanding rather than discovering at tax time.
Who should consider it
Investors with a lumpsum — a bonus, a maturity, a property sale — who want equity exposure without a single entry point. Investors reallocating from debt to equity. Anyone who would otherwise leave the money in a savings account while deciding.
Benefits
- Money earns in a liquid fund while waiting to be deployed
- Entry into equity is averaged across several months
- Removes the pressure of picking a single entry level
- Transfer amount and frequency can be set to your comfort
- Can be stopped or modified at any time
- Better than holding the money in a savings account meanwhile
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Investment into a liquid or ultra-short duration source fund
- Fixed periodic transfers into the target equity scheme
- Weekly, monthly or quarterly transfer frequency
- Ability to change the amount or stop the plan
- Redemption of the remaining source corpus at any time
Not included
- Any protection against the target fund falling
- Any guarantee of return on either fund
- Tax exemption on transfers, which are redemptions from the source fund
- Transfers between fund houses — both funds must be with the same AMC
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 Goal and horizon before fund selection What the money is for and when you need it decides the asset class. The fund name is the last decision, not the first.
- 2 Risk profiling that is honest rather than flattering Capacity to take risk and willingness to sit through a fall are different things. We assess both, because the second is what breaks plans.
- 3 Shortlist built on process, not last year's return Mandate, expense ratio, fund manager tenure and how the fund behaved in a bad year. Past performance is not a forecast.
- 4 KYC, onboarding and the first investment One-time KYC, then the folio and the mandate. We set up the SIP so it runs without depending on you remembering.
- 5 Review annually, rebalance deliberately A yearly review against the goal, not a monthly reaction to markets. Most damage in investing is self-inflicted.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Both funds must be with the same fund house. You cannot run an STP from one AMC into another.
- Choose the transfer period deliberately. Six months is a common default; a longer period averages more but leaves more money in debt for longer.
- Each transfer is a redemption from the source fund and a taxable event on those gains. On a liquid fund the amounts are small, but the mechanism applies.
- An STP does not protect against a fall in the target fund after the money arrives. It averages entry; it does not remove equity risk.
- Mutual fund investments are subject to market risk. Neither the source nor the target fund is guaranteed.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Cancelled cheque or bank account details
- Recent passport-size photograph
- Completed KYC, or KYC documents to complete it
- FATCA and nominee declaration
Frequently Asked Questions
Why not just keep the money in savings and invest monthly?
Because a liquid fund typically earns more than a savings account while the money waits, and the transfer runs automatically rather than depending on you executing it each month. The averaging effect is the same; the intervening return and the discipline are better.
How long should the transfer period be?
Six to twelve months is the common range. A shorter period gets the money invested faster and averages less; a longer one averages more but leaves a larger share in debt for longer. There is no optimal answer, only one that fits your comfort with a single entry level.
Can I transfer between different fund houses?
No. An STP operates within one asset management company — the source and target funds must both belong to the same AMC. Moving between fund houses requires redeeming and reinvesting, which is a different transaction.
Are the transfers taxable?
Each transfer is a redemption from the source fund, so gains in that fund are taxable at that point. On a liquid fund over a few months those gains are usually small, but it is worth knowing the mechanism rather than being surprised by it.
Does an STP reduce my risk?
It reduces entry-level risk by averaging across several months. It does not reduce the risk of the equity fund falling after your money is in it. Mutual fund investments remain subject to market risk throughout.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.