
Check your eligibility
What These Loans Fund
-
A credit limit against pledged mut...
-
Both equity and debt funds
-
Overdraft structure with interest...
-
Any lawful end use
-
Continued dividends and returns on...
Who Can Consider This Loan?
- Ownership of the assets being pledged, in your own name
- Assets on the lender's approved list of pledgeable securities
- Minimum holding value set by the lender
- KYC completed with the lender
- For insurance policies, a policy that has acquired surrender value
What May Not Be Funded?
- Funds not on the lender's approved list
- Units held in a minor's name or under lock-in, such as ELSS within its period
- Amounts above the funding percentage after haircut
- Redemption of pledged units while the lien is active
- Speculative use, which most lenders prohibit
Always check the sanction letter before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading loans companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced loans professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
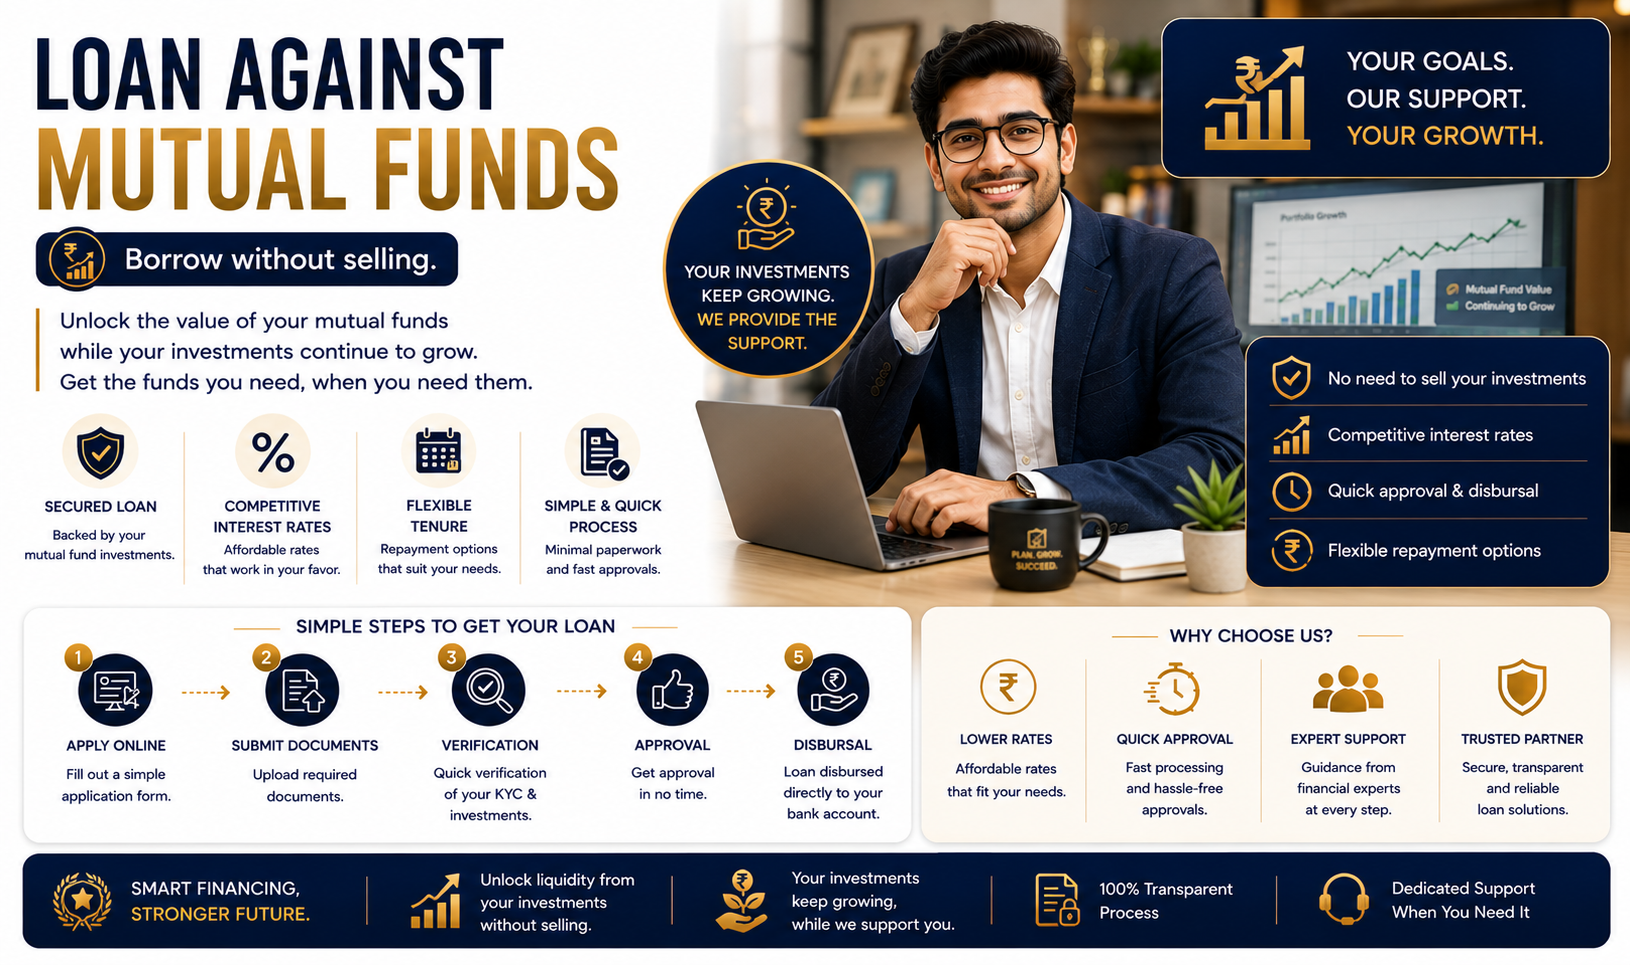
A loan against mutual funds pledges your units to a lender in exchange for a credit limit. The units stay invested, continue to earn returns, and are never sold — a lien is simply marked on them.
That distinction matters more than it first appears. Redeeming units to raise cash triggers capital gains tax, exits you from the market at whatever level it happens to be, and destroys the compounding you have built. Borrowing against them does none of those things.
Funding percentages differ by fund type. Debt funds attract a higher percentage of their value because they are less volatile; equity funds attract less, because a market fall reduces the collateral. That volatility also creates the main risk: if markets fall far enough, the lender can call for additional margin.
Who should consider it
Investors needing short-term liquidity who do not want to disturb a long-term portfolio. Anyone about to take a personal loan while holding mutual funds. Investors facing a temporary cash requirement rather than a permanent one.
Benefits
- Units stay invested and keep earning while you borrow against them
- No capital gains tax, because nothing is redeemed
- Rates far below unsecured personal borrowing
- Usually structured as an overdraft, so interest is on what you draw
- Fast processing — the asset is already visible to the lender
- Your long-term compounding is left intact
What the loan funds, and what it does not
Read the right-hand column first. It is the one that decides how much you have to arrange yourself.
Usually funded
- A credit limit against pledged mutual fund units
- Both equity and debt funds, at differing percentages
- Overdraft structure with interest on the drawn amount
- Any lawful end use
- Continued dividends and returns on the pledged units
Usually not funded
- Funds not on the lender's approved list
- Units held in a minor's name or under lock-in, such as ELSS within its period
- Amounts above the funding percentage after haircut
- Redemption of pledged units while the lien is active
- Speculative use, which most lenders prohibit
Funding limits and the treatment of add-ons vary between lenders and move with the borrower profile. The sanction letter you receive is what governs — we will walk you through it before you sign.
How it works with us
- 1 We look at what you already hold Mutual funds, deposits, shares, bonds and policies. Most people needing a personal loan are holding something cheaper to borrow against.
- 2 Eligible value calculated after haircut Lenders lend a percentage of market value, and the percentage varies sharply by asset. That number decides what you can raise.
- 3 Lien or pledge marked The asset stays yours and keeps earning. A lien is recorded so it cannot be sold while the loan runs.
- 4 Limit sanctioned, usually as an overdraft You draw what you need and pay interest only on that. For an uncertain need this is far cheaper than a term loan.
- 5 Margin monitored while the loan runs For market-linked assets we flag it if a fall approaches a margin call, so you are not surprised by one.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- This is the answer to most personal loan questions from investors. If you hold funds, borrowing against them is roughly half the cost of an unsecured loan.
- Equity funds carry margin call risk. A sharp market fall can require you to pledge more units or repay part of the loan, and that demand arrives at the worst moment.
- ELSS units inside their three-year lock-in generally cannot be pledged. Check which of your holdings are actually eligible before planning around a number.
- Use the overdraft structure. Interest on what you draw, for the days you draw it, is far cheaper than a term loan for an uncertain need.
- Keep the loan short. The reason this works is that your investment keeps compounding — a loan running for years against it erodes that advantage.
Documents required
- Identity proof — Aadhaar, PAN or passport
- Address proof
- Statement of holdings for the assets being pledged
- Demat account details, for shares and bonds
- Policy documents, for loans against insurance
- Fixed deposit receipts, where applicable
- Bank account details for disbursal
Frequently Asked Questions
Do I have to sell my units?
No. A lien is marked on the units and they stay invested in your name, continuing to earn returns. That is the central advantage: you get liquidity without triggering capital gains tax or exiting the market at whatever level it happens to be.
How much can I borrow?
Typically fifty to sixty per cent of the value of equity funds and seventy to eighty per cent of debt funds. The difference reflects volatility — equity collateral can fall in value, so the lender takes a larger haircut.
What is a margin call?
If markets fall enough that your pledged units no longer cover the loan at the required ratio, the lender can ask you to pledge more units or repay part of the balance. It is the main risk of borrowing against equity, and it arrives precisely when markets are already down.
Can I pledge ELSS units?
Not during the three-year statutory lock-in. Once the lock-in has expired they become eligible like any other equity fund. Check which of your holdings are actually pledgeable before planning around a total.
Is this better than a personal loan?
Almost always, for an investor. The rate is roughly half, there is no capital gains event, and your investment keeps compounding throughout. If you hold mutual funds and are considering a personal loan, start here.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.