
Wealth & Covers
Search products, guides, calculators
+919990003062

Fixed Deposits

Know your FDs

  • Goal-based Planning
  • Diversified Options
  • Regular Reviews
  • End-to-End Support
Fixed Deposits

Where would you like to invest?

Choose the right investment

Bank FD

Most Popular

A bank deposit at a fixed rate — safe, simple, fully taxable, and often below inflation after tax.

  • The rate is fixed at the outset and cannot fall
  • DICGC insurance up to ₹5 lakh per depositor per bank
  • Premature withdrawal available, subject to a penalty
View Details

Senior Citizen FD

Deposits for those over sixty — a higher rate, and a much larger tax exemption on the interest.

  • Additional interest rate, commonly 0.5% above standard
  • Section 80TTB exemption on interest up to ₹50,000 a year
  • Some banks offer a further increment above age 75
View Details

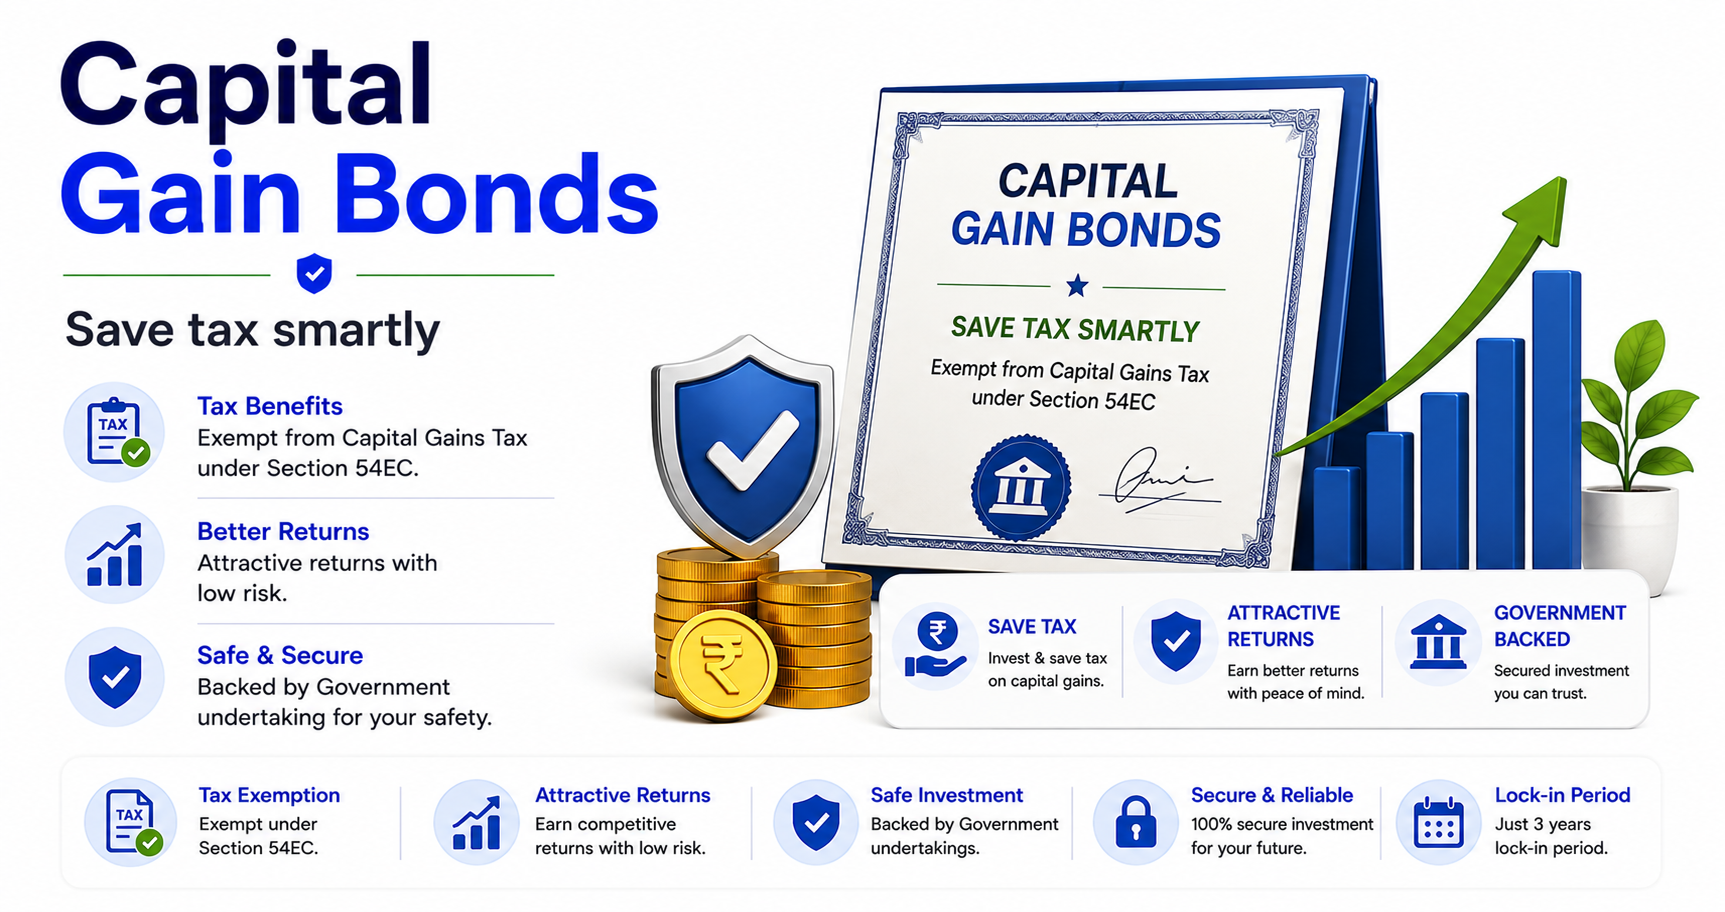
Capital Gain Bonds

Section 54EC bonds — deferring capital gains tax on a property sale, at a modest return.

  • Defers tax on long-term capital gains from land or building
  • Issued by designated institutions with a government-backed profile
  • A defined five-year tenure with a known outcome
View Details

Invest Today. Thrive Tomorrow.

Why Fixed Deposits?

  • The rate is fixed at the outset and cannot fall
  • DICGC insurance up to ₹5 lakh per depositor per bank
  • Premature withdrawal available, subject to a penalty
  • A loan against the deposit at a small spread over the deposit rate
  • No market risk and nothing to monitor

More than Returns A Partner for Life

What You Get

  • A deposit at a contractually fixed rate
  • Tenures from seven days to ten years
  • Cumulative or periodic interest payout options
  • Auto-renewal at maturity, where instructed
  • Loan or overdraft facility against the deposit
  • Nomination facility
View complete coverage

Risks to Know

  • Any tax exemption — interest is fully taxable at your slab rate
  • Protection against inflation
  • Any return above the contracted rate if market rates rise
  • DICGC cover above ₹5 lakh per depositor per bank
  • The full rate on premature withdrawal, where a penalty applies
View all details

Compare Popular Options

Plan Bank FD Senior Citizen FD Capital Gain Bonds Corporate Fixed Deposits
Best for Safe & reliable More benefits for seniors Save tax smartly Earn higher returns
Minimum from* ₹10,000 ₹10,000 ₹10,000 ₹25,000
Rating 4.4 4.6 4.2 4.0
Details View View View View

*Indicative starting figures; the final terms depend on your profile.

Compare Plans

Already investing?

Get your portfolio reviewed and make sure it is working for your goals.

  • Check your asset allocation
  • Spot overlapping funds
  • Review costs and returns
  • Get expert recommendations

Get your current investment reviewed

Share it with an advisor — no cost, no obligation

We're Here For The Long Run.

Frequently Asked Questions

View All FAQs
Is my money completely safe?

Deposits are insured up to five lakh rupees per depositor per bank under the DICGC scheme, covering both principal and interest. Above that limit you rely on the bank's own solvency, which is why large savers spread deposits across institutions.

How is the interest taxed?

Fully, at your income tax slab rate, whether you take it annually or at maturity. Banks deduct tax at source above a threshold. For a taxpayer in the highest bracket, a seven per cent deposit yields under five per cent after tax — which is the number to compare against inflation.

What happens if I withdraw early?

Most banks pay the rate applicable for the period actually held, less a penalty of typically half to one per cent. Before breaking a deposit, check whether a loan against it is cheaper — it usually is, because the deposit keeps earning.

Should I submit Form 15G or 15H?

If your total income is below the taxable threshold, yes — it prevents the bank deducting tax at source, which you would otherwise have to reclaim through your return. Form 15H is for senior citizens, 15G for others.

Are deposits a good long-term investment?

They are excellent for certainty and poor for growth. After tax, deposit returns frequently sit at or below inflation, which means purchasing power erodes slowly while the balance appears to rise. For long-term wealth building, deposits are usually the wrong instrument.

Not sure what fixed deposits you need?

Tell us about your needs. Our experts will help you find the right investment.

Talk to an Expert

Speak to an advisor

Good decisions begin with clarity.

Tell us where you are today. We’ll help you understand what matters, what may be missing, and what you can do next.

See the full picture
Understand what you already have and where it stands.
Find what's missing
Identify the gaps that could affect your family, wealth or business.
Know what to do next
Get practical guidance built around your priorities — not a product pitch.

No pressure. No obligation. Just a thoughtful conversation.

Let's Connect

Your details are safe & confidential. We'll contact you only regarding your enquiry.