
Wealth & Covers
Search products, guides, calculators
+919990003062

Loans Against Investments

Borrow without selling

  • Multiple Lenders
  • Eligibility Check
  • Competitive Rates
  • End-to-End Support

What are you looking to fund?

Choose the right loan

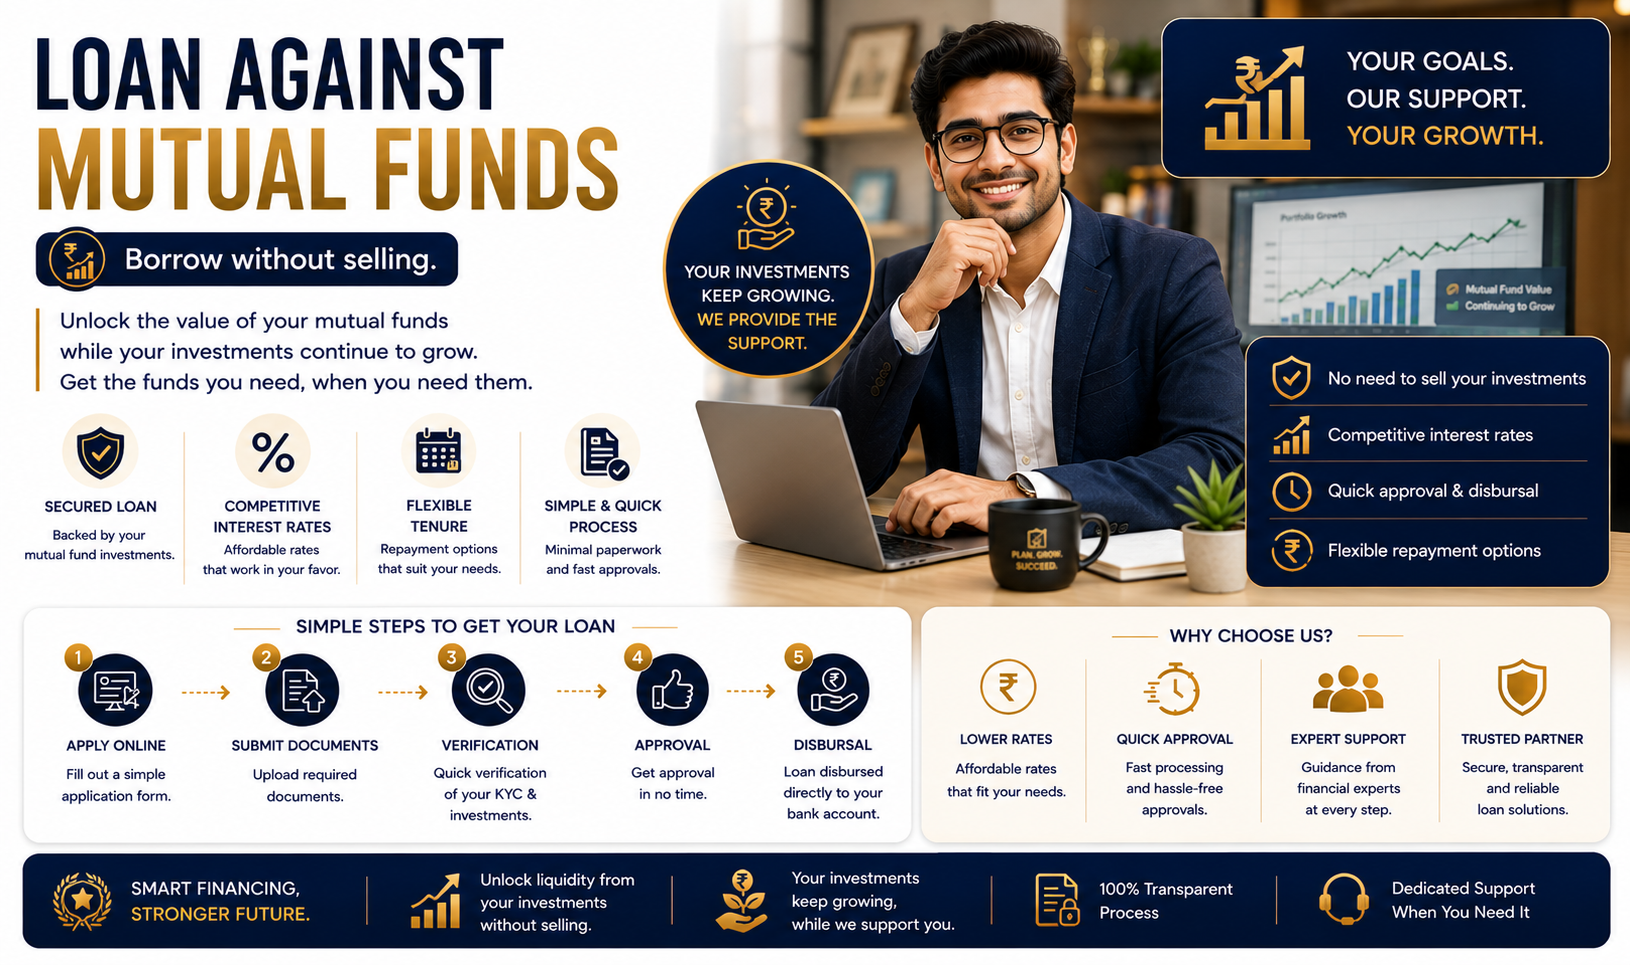
Loan Against Mutual Funds

Most Popular

Borrow against your fund units without redeeming them — no capital gains, no exit from the market.

  • Units stay invested and keep earning while you borrow against them
  • No capital gains tax, because nothing is redeemed
  • Rates far below unsecured personal borrowing
View Details

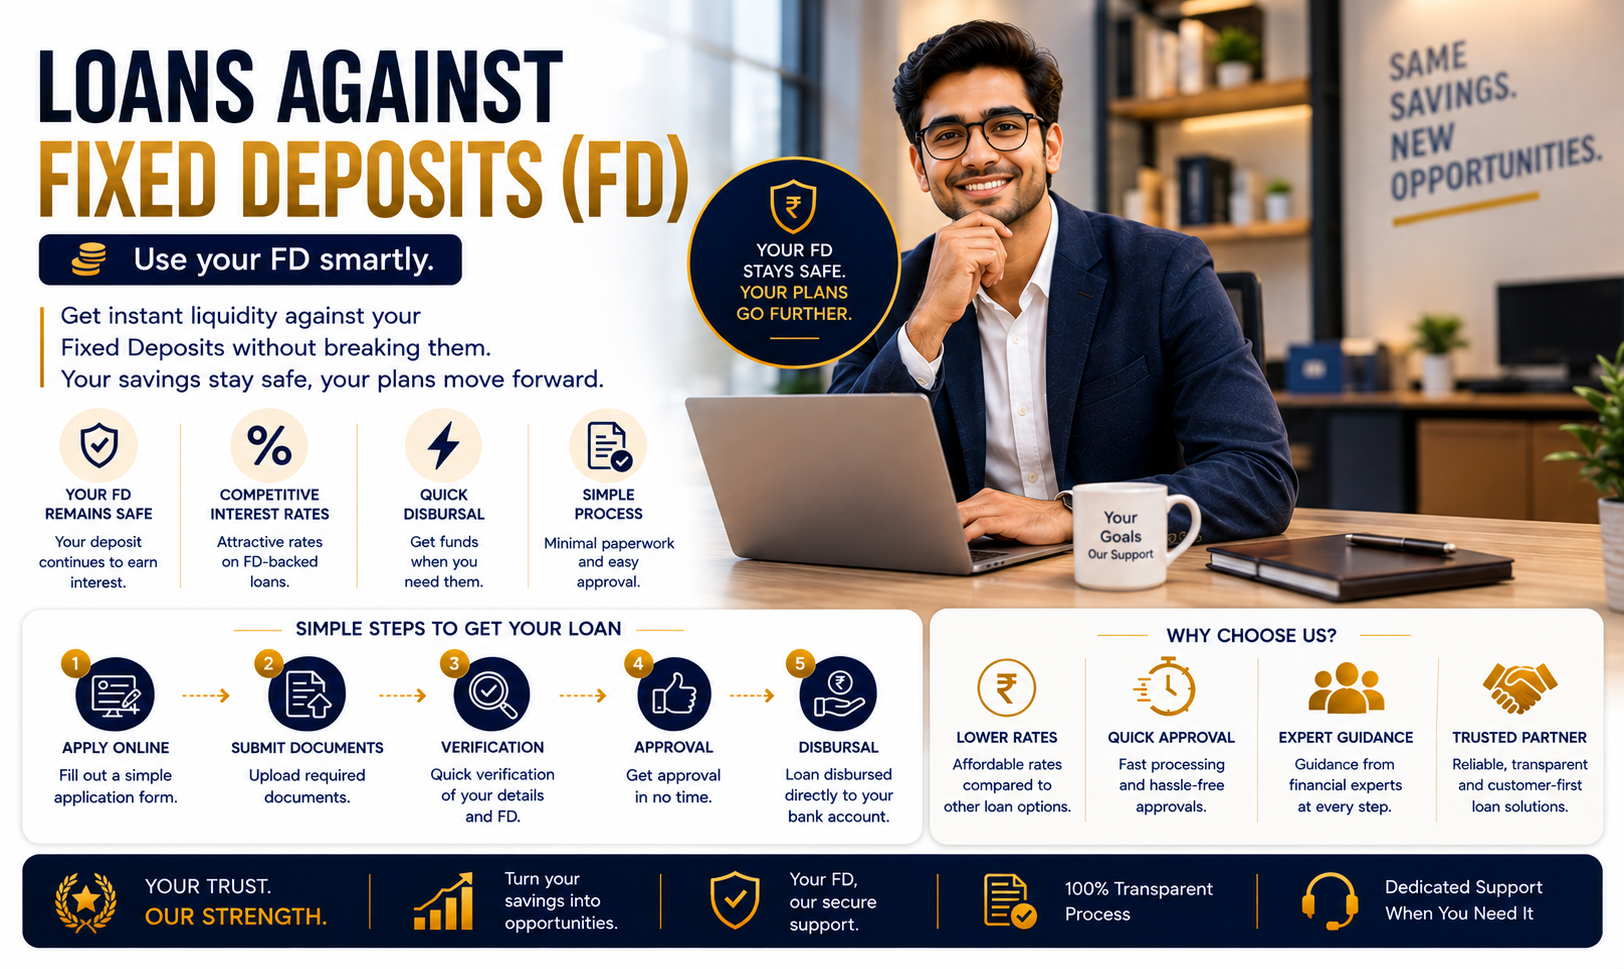
Loan Against Fixed Deposits (FD)

The cheapest borrowing available to most people — your own deposit as security, at a small spread.

  • The lowest rate available on any retail borrowing
  • The deposit continues earning interest throughout
  • Avoids premature withdrawal penalties and lost interest
View Details

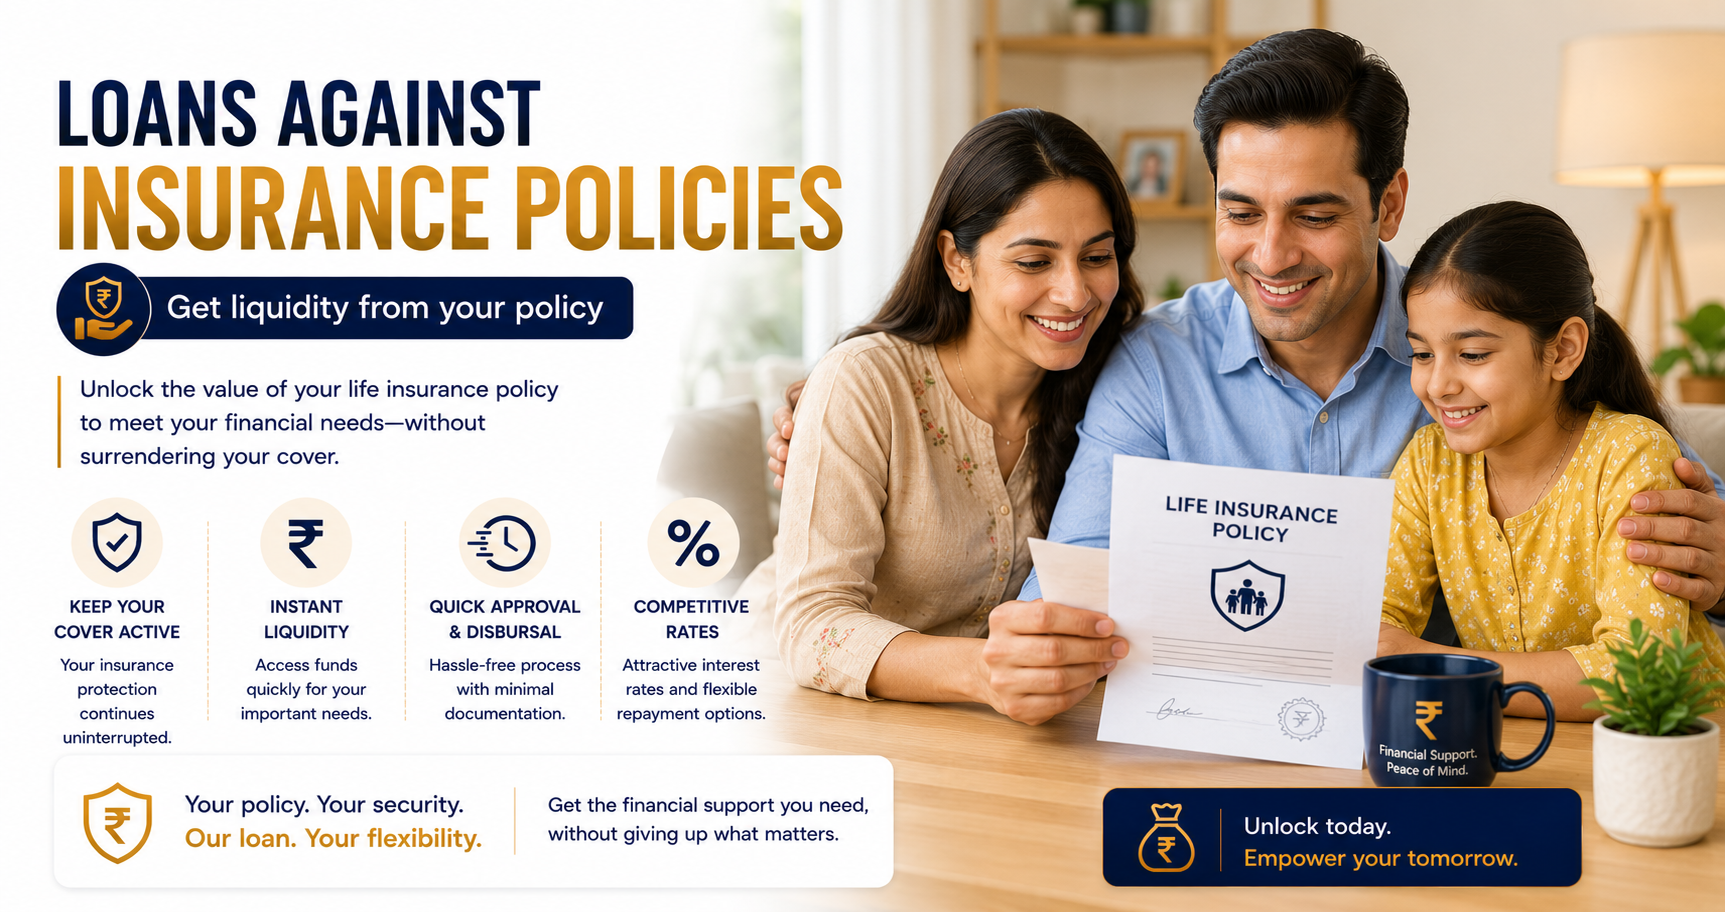
Loan Against Insurance Policies

Borrowing against a policy's surrender value — keeping the cover in force instead of cancelling it.

  • The policy stays in force and the life cover continues
  • Avoids the poor value of an early surrender
  • Rates well below unsecured borrowing
View Details

Plan Today. Own Tomorrow.

Why Loans Against Investments?

  • Units stay invested and keep earning while you borrow against them
  • No capital gains tax, because nothing is redeemed
  • Rates far below unsecured personal borrowing
  • Usually structured as an overdraft, so interest is on what you draw
  • Fast processing — the asset is already visible to the lender

More than Loans A Partner for Life

What's Included?

  • A credit limit against pledged mutual fund units
  • Both equity and debt funds, at differing percentages
  • Overdraft structure with interest on the drawn amount
  • Any lawful end use
  • Continued dividends and returns on the pledged units
View complete coverage

Things to Keep in Mind

  • Funds not on the lender's approved list
  • Units held in a minor's name or under lock-in, such as ELSS within its period
  • Amounts above the funding percentage after haircut
  • Redemption of pledged units while the lien is active
  • Speculative use, which most lenders prohibit
View all details

Compare Popular Loans

Plan Loan Against Mutual Funds Loan Against Fixed Deposits (FD) Loan Against Insurance Policies Loan Against Securities
Best for Borrow without selling Use your FD smartly Get liquidity from your policy Unlock the value of your shares
Interest from* 9.5% 7.5% 9% 9.75%
Rating 4.4 4.6 4.2 4.2
Details View View View View

*Indicative starting figures; the final terms depend on your profile.

Compare Plans

Already have a loan?

Review your existing loans and make sure you're not paying more than you need to.

  • Check for a lower rate
  • Explore a balance transfer
  • Check top-up eligibility
  • Get expert recommendations

Get your current loan reviewed

Share it with an advisor — no cost, no obligation

We're Here Till Your Last EMI.

Frequently Asked Questions

View All FAQs
Do I have to sell my units?

No. A lien is marked on the units and they stay invested in your name, continuing to earn returns. That is the central advantage: you get liquidity without triggering capital gains tax or exiting the market at whatever level it happens to be.

How much can I borrow?

Typically fifty to sixty per cent of the value of equity funds and seventy to eighty per cent of debt funds. The difference reflects volatility — equity collateral can fall in value, so the lender takes a larger haircut.

What is a margin call?

If markets fall enough that your pledged units no longer cover the loan at the required ratio, the lender can ask you to pledge more units or repay part of the balance. It is the main risk of borrowing against equity, and it arrives precisely when markets are already down.

Can I pledge ELSS units?

Not during the three-year statutory lock-in. Once the lock-in has expired they become eligible like any other equity fund. Check which of your holdings are actually pledgeable before planning around a total.

Is this better than a personal loan?

Almost always, for an investor. The rate is roughly half, there is no capital gains event, and your investment keeps compounding throughout. If you hold mutual funds and are considering a personal loan, start here.

Not sure what loans against investments you need?

Tell us about your needs. Our experts will help you find the right loan.

Talk to an Expert

Speak to an advisor

Good decisions begin with clarity.

Tell us where you are today. We’ll help you understand what matters, what may be missing, and what you can do next.

See the full picture
Understand what you already have and where it stands.
Find what's missing
Identify the gaps that could affect your family, wealth or business.
Know what to do next
Get practical guidance built around your priorities — not a product pitch.

No pressure. No obligation. Just a thoughtful conversation.

Let's Connect

Your details are safe & confidential. We'll contact you only regarding your enquiry.