
Check your eligibility
What These Loans Fund
-
Venue
-
Photography
-
Travel and accommodation for guest...
-
Outfits and jewellery purchases
-
Any other wedding-related expense
Who Can Consider This Loan?
- Indian resident, generally aged 21 to 60
- Salaried: minimum monthly income set by the lender and city
- Self-employed: two to three years of business vintage with filed returns
- Credit score is the dominant factor in both approval and rate
- Total EMI obligations usually capped at 50 to 55% of net income
- Employment with a recognised employer improves both terms and speed
What May Not Be Funded?
- Processing fee, usually deducted from disbursal
- Any tax deduction on interest
- Amounts beyond what your income supports
- A special rate — this is priced as an ordinary personal loan
Always check the sanction letter before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading loans companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced loans professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
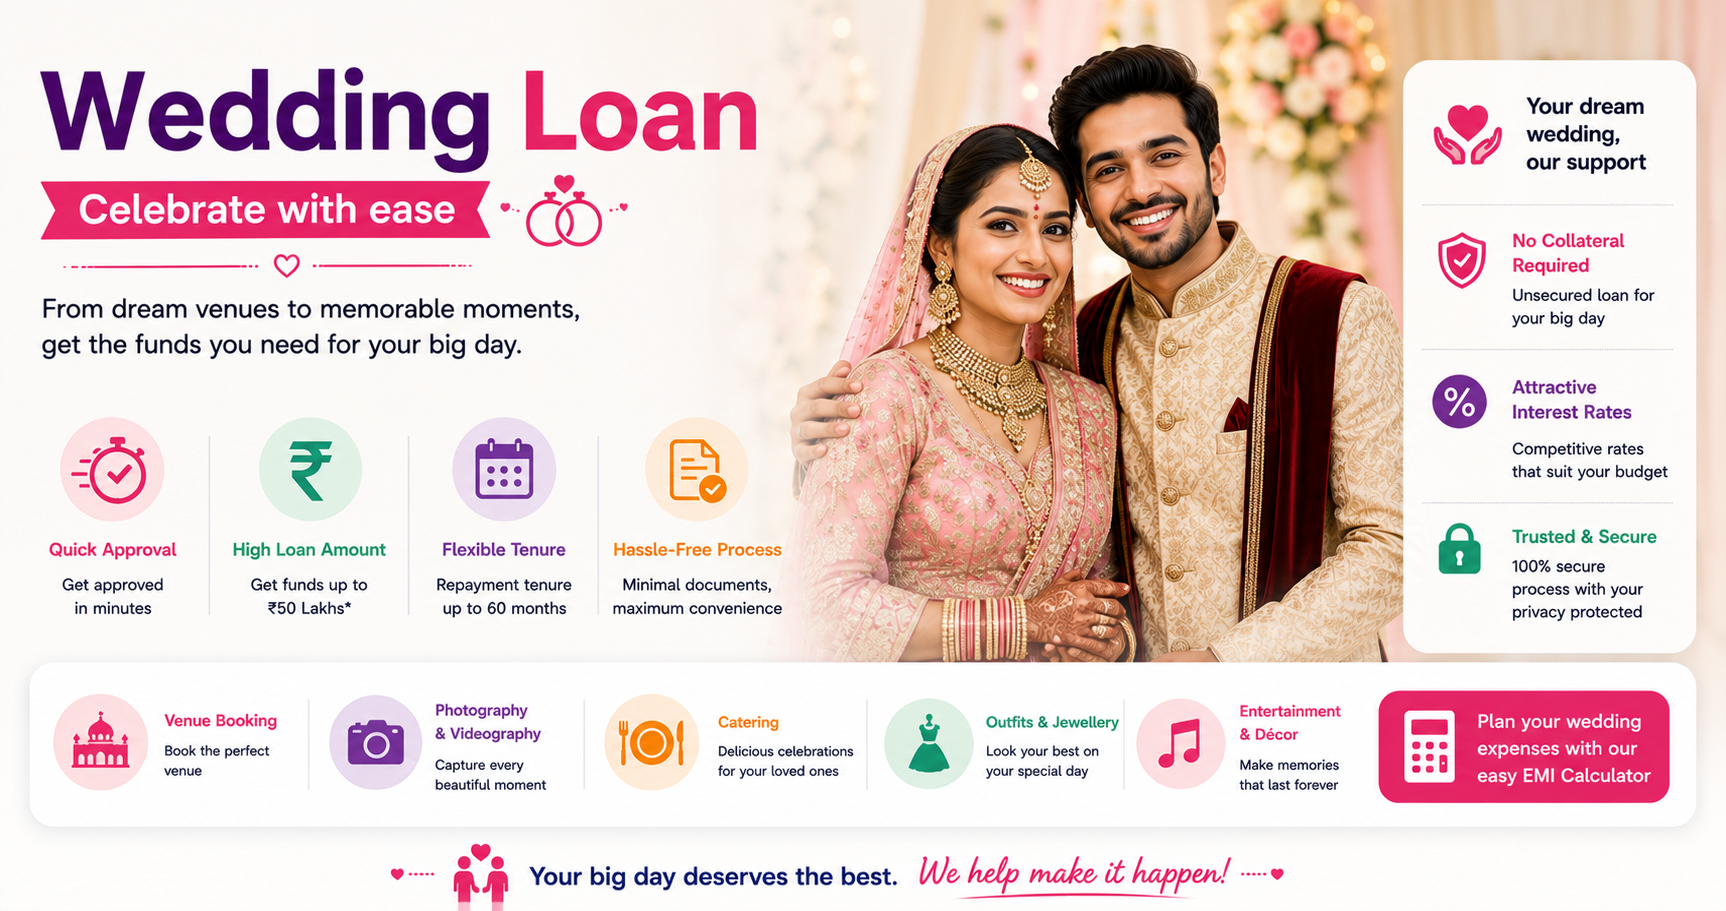
A wedding loan is an ordinary personal loan marketed for a specific purpose. There is no separate product category and no special rate — the underwriting, pricing and terms are identical to any unsecured personal loan.
What is genuinely different is the context. Indian weddings involve large, front-loaded and often non-refundable commitments, and the social pressure to spend beyond a comfortable budget is real. Borrowing to meet that pressure means servicing an EMI for five years for an event that lasted three days.
We will arrange it, and we will also do the arithmetic with you. Ten lakh borrowed over five years costs meaningfully more than ten lakh, and knowing that figure before the bookings are made is more useful than knowing it afterwards.
Who should consider it
Families with a genuine shortfall between committed costs and available funds. Borrowers who have already reduced the budget and still have a gap. Anyone who would otherwise liquidate long-term investments at a bad moment.
Benefits
- Fast disbursal aligned to vendor payment schedules
- No collateral required
- Fixed EMI so the repayment is predictable
- Preserves investments that would otherwise be liquidated
- Cheaper than funding wedding costs on credit cards
- Tenure can be set to clear the loan within a defined period
What the loan funds, and what it does not
Read the right-hand column first. It is the one that decides how much you have to arrange yourself.
Usually funded
- Venue, catering and decoration costs
- Photography, entertainment and production
- Travel and accommodation for guests
- Outfits and jewellery purchases
- Any other wedding-related expense
Usually not funded
- Processing fee, usually deducted from disbursal
- Any tax deduction on interest
- Amounts beyond what your income supports
- A special rate — this is priced as an ordinary personal loan
Funding limits and the treatment of add-ons vary between lenders and move with the borrower profile. The sanction letter you receive is what governs — we will walk you through it before you sign.
How it works with us
- 1 Eligibility checked before any application is filed Each rejected application marks your credit file. We match your profile to lenders who will actually approve it, rather than applying everywhere.
- 2 Compared on total cost, not the advertised rate Processing fee, insurance bundling and prepayment terms often matter more than the headline number.
- 3 We name the cheaper alternative if there is one A top-up on your home loan or a loan against securities is often half the cost. If that applies to you, we will say so.
- 4 One document set, submitted once Prepared properly the first time, which is what makes same-day approval realistic.
- 5 Sanction, disbursal and a repayment plan The sanction states rate, fee and prepayment terms. We set out how prepaying would work before you need it.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Calculate the total repayment before booking, not after. Seeing what ten lakh over five years actually costs changes budget decisions in a way that seeing the EMI does not.
- Consider wedding insurance alongside. It covers the deposits you are borrowing to pay if the event has to be cancelled, and it costs a fraction of the loan interest.
- A shorter tenure costs less overall and clears the obligation before it starts affecting other plans. Two years of discomfort is better than five of drag.
- Where a parent has a home loan, a top-up is usually cheaper than an unsecured wedding loan. Compare before defaulting to the faster option.
- Avoid funding any of it on credit cards. A personal loan at eleven per cent is a considerable improvement on a card at thirty-six.
Documents required
- Identity proof — Aadhaar, PAN or passport
- Address proof
- Salaried: last three months of salary slips and Form 16
- Self-employed: last two years of income tax returns with computation
- Bank statements for the last six months
- Employment proof or business registration
- Recent passport-size photograph
- Existing loan and credit card statements
Frequently Asked Questions
Is there a special rate for wedding loans?
No. It is an ordinary personal loan with a marketing label. The underwriting, pricing and terms are identical, and the rate is driven by your credit profile rather than by the purpose.
How much should I borrow?
The smallest amount that closes a genuine gap after the budget has already been examined. The useful discipline is to calculate the total repayment first — the five-year cost of a large wedding loan is a number that tends to change decisions.
Is there a cheaper way to fund a wedding?
Frequently. A top-up on an existing home loan, a loan against securities, or a loan against a fixed deposit will typically cost around half as much. If any of those are available to you or a parent, they are worth the extra paperwork.
Should I also buy wedding insurance?
It is worth considering, particularly if you are borrowing to pay non-refundable deposits. It covers exactly the money you are financing if the event cannot proceed, and it costs a small fraction of the loan interest.
What tenure should I choose?
The shortest you can comfortably service. A longer tenure makes the EMI smaller and the total cost considerably larger, and it means the wedding is still being paid for when other financial goals arrive.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.