
Get Expert Guidance
What Our Plans Cover
-
Factory building and fixed install...
-
Plant and machinery
-
Raw materials
-
Fire
-
Machinery breakdown
-
Business interruption and increase...
-
Debris removal and firefighting ex...
-
Public liability arising from the...
Who Can Consider This Plan?
- Legal ownership, or an insurable interest such as a lease
- Property of permanent construction, meeting the insurer's standards
- Accurate declaration of occupancy and use
- Sum insured set on a defensible valuation basis
- Compliance with any fire safety requirements applicable to the premises
What May Not Be Covered?
- Gradual wear, corrosion and erosion of plant
- Faulty design and defective materials
- Damage from operating outside manufacturer specifications
- Loss of contracts or market share following an incident
- Pollution and contamination, unless specifically covered
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
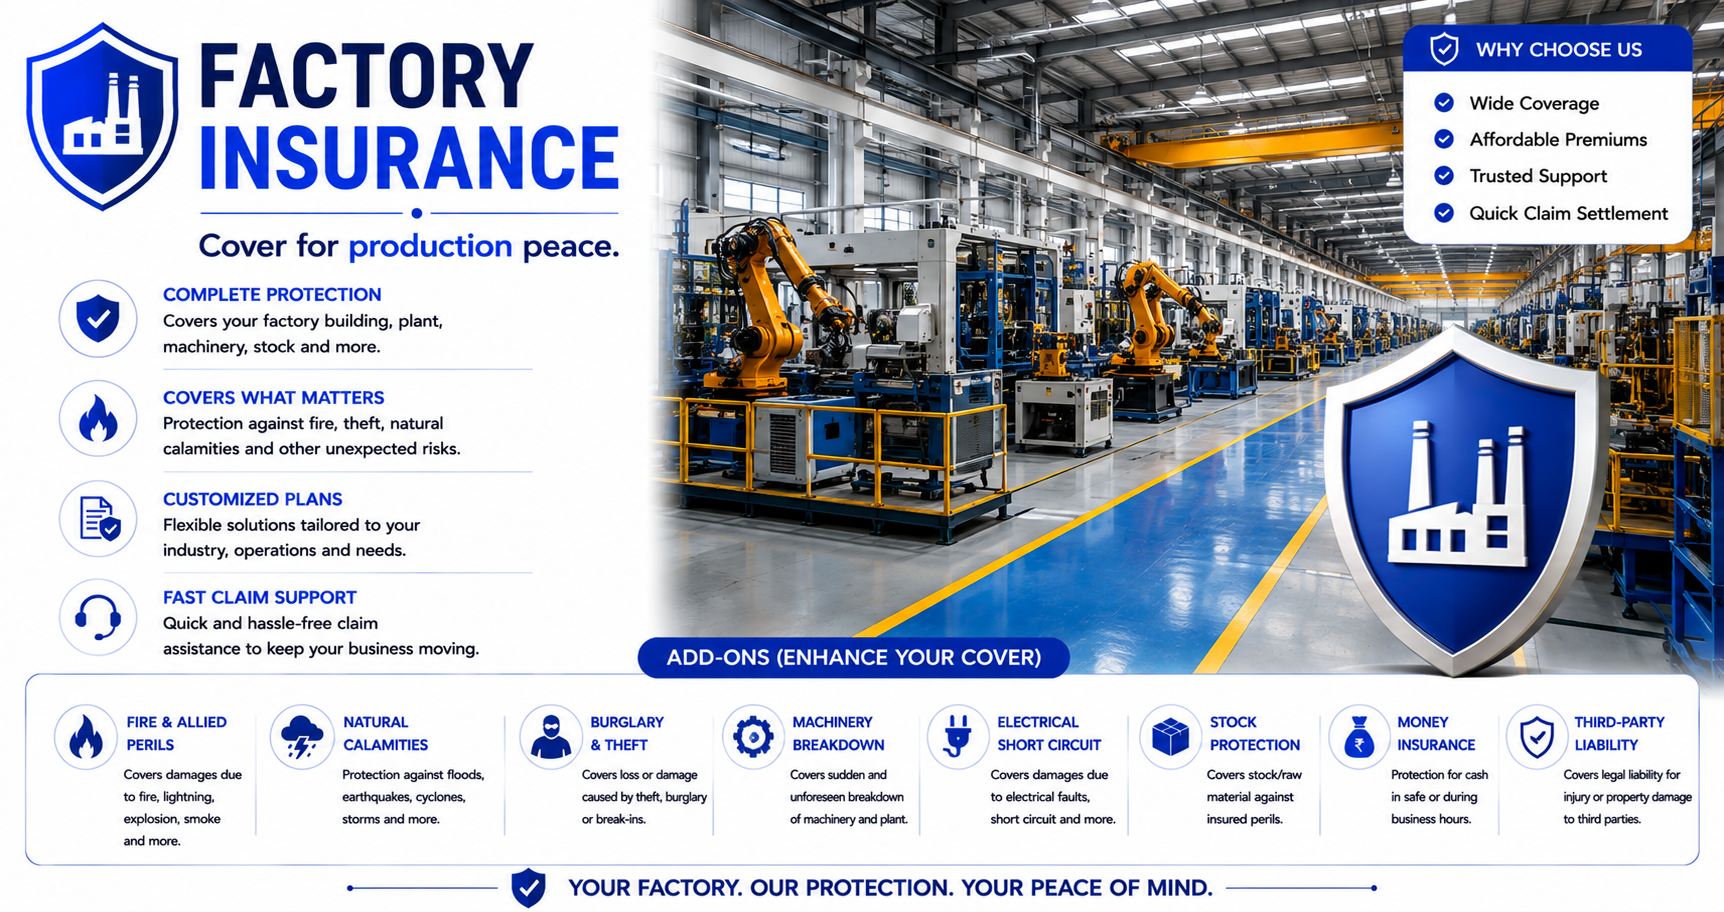
Factory insurance covers the building, the plant and machinery, raw materials, work in progress and finished goods. It is usually written as a package with fire, machinery breakdown and business interruption combined.
In manufacturing, business interruption is generally the largest exposure by a wide margin. A machine can be replaced in weeks; the contracts lost during those weeks may not come back. The indemnity period — how long the interruption cover runs — is therefore the most consequential number in the policy.
Rating depends heavily on the process. What you manufacture, what you store, how you handle heat and chemicals, and what fire protection is installed all move the premium substantially. Improving any of them is usually cheaper than paying the loading.
Who should consider it
Manufacturers of any size. Processing units. Any operation with significant plant, machinery or hazardous processes, and any operation where a shutdown would cost more than the physical damage.
Benefits
- Building, plant, machinery and stock under one programme
- Machinery breakdown cover for the failures fire policies exclude
- Business interruption covering lost gross profit and standing costs
- Cover for stock at all stages, from raw material to finished goods
- Boiler and pressure plant cover where applicable
- Premium responsive to fire protection and risk improvement
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Factory building and fixed installations
- Plant and machinery
- Raw materials, work in progress and finished goods
- Fire, explosion, flood, storm and other natural perils
- Machinery breakdown, where the extension is taken
- Business interruption and increased cost of working
- Debris removal and firefighting expenses
- Public liability arising from the premises
Typically not covered
- Gradual wear, corrosion and erosion of plant
- Faulty design and defective materials
- Damage from operating outside manufacturer specifications
- Loss of contracts or market share following an incident
- Pollution and contamination, unless specifically covered
- Employee injury, which is a workmen's compensation matter
- Product liability, which is a separate class
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 We value the risk before we quote it Reinstatement cost of the structure, current value of the contents, and what a total loss would actually cost to rebuild today.
- 2 Perils matched to the location A coastal warehouse, a basement in a flood-prone city and a first-floor office are three different risks. The policy should reflect which one you are.
- 3 Quotes compared on sum insured basis, not premium Market value against reinstatement value changes what you receive far more than the premium difference between insurers.
- 4 Survey where the value warrants it Larger risks are surveyed before cover. It is also the moment to fix anything that would reduce a claim later.
- 5 Policy issued, and reviewed annually We revisit the sum insured every renewal. Under-insurance is the single most common reason property claims are cut.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Set the indemnity period against realistic recovery, not optimistic recovery. Long-lead machinery, regulatory clearances and rebuilding a customer base all take longer than the repair does.
- Machinery breakdown is not covered by a fire policy. The two address different failures and most factories need both.
- Insure plant on reinstatement value. Depreciated settlements do not buy replacement machinery, particularly imported equipment.
- Fire protection investment usually pays for itself in premium alone. Sprinklers, hydrants, detection and compartmentation are the largest levers you control.
- Product liability and employee injury are separate classes. A factory package covers the property and the interruption, not what happens to your customers or your workers.
Documents required
- Proof of ownership or the lease agreement
- Details of construction — age, materials, number of floors
- Valuation or reinstatement cost estimate of the structure
- Inventory and value of contents, stock or equipment
- Details of fire protection and security arrangements
- Previous policy and claims history, where applicable
- Photographs of the premises, for larger risks
Frequently Asked Questions
What indemnity period should I choose for business interruption?
Long enough to cover realistic full recovery — rebuilding, replacing machinery with genuine lead times, obtaining clearances, and winning back customers. Twelve months is a common default and is frequently too short for anything with imported or custom plant.
Is machinery breakdown included in fire cover?
No. A fire policy responds to fire and named perils; a breakdown policy responds to mechanical and electrical failure of the machine itself. They cover different events, and most manufacturers need both.
How much can fire protection reduce my premium?
Substantially. Process hazard and fire protection are the dominant rating factors on a factory. Sprinklers, hydrants, detection and compartmentation frequently pay for themselves in premium saving alone, before counting the reduction in the loss.
Are my employees covered if injured?
Not under this policy. Employee injury falls under workmen's compensation or an employer's liability policy, which is a separate and statutory requirement.
Is product liability included?
No. Harm caused by your products to customers is product liability, a distinct class. A factory package covers your premises and your production, not the consequences of what leaves the gate.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.