
Wealth & Covers
Search products, guides, calculators
+919990003062

Vehicle Insurance

Cover for every drive

  • Unbiased Advice
  • Claims Assistance
  • Competitive Premiums
  • End-to-End Support
Vehicle Insurance

What are you looking to insure?

Choose the right cover

Private Car

Most Popular

Comprehensive car cover — where the add-ons, not the base policy, decide what you actually receive.

  • Unlimited third-party injury liability, as the statute requires
  • Own damage covered for collision, fire, theft and natural calamity
  • Zero depreciation removes the deduction that shrinks most claims
View Details

Zero Dep Plan

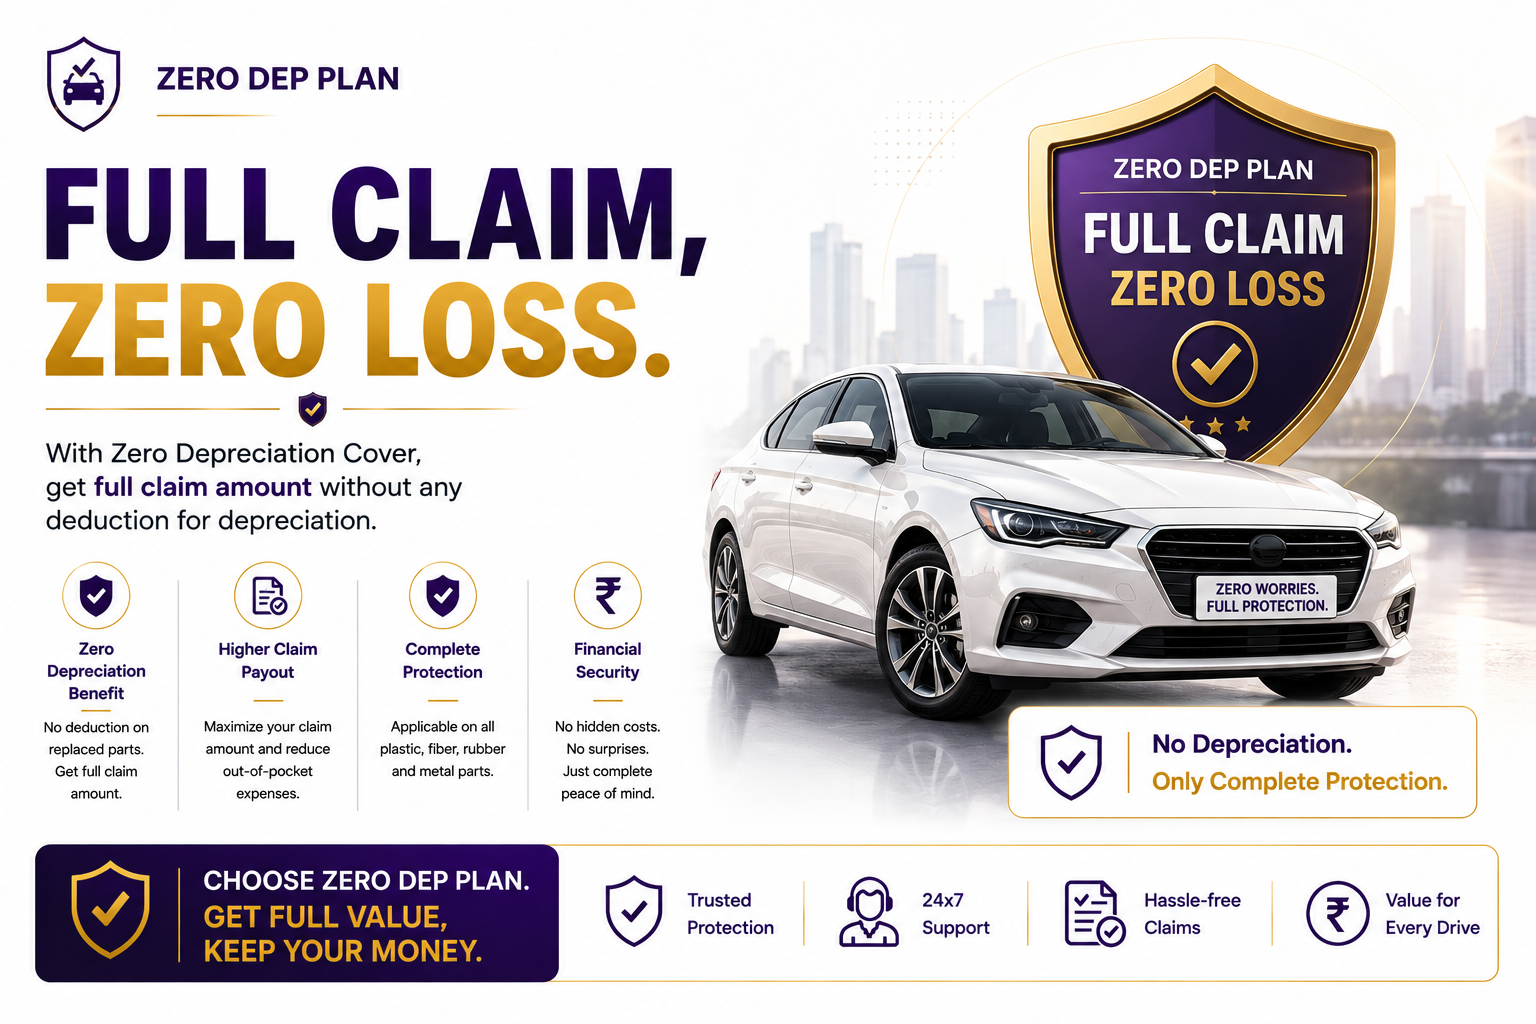
Comprehensive cover without the depreciation deduction — the add-on that changes what a claim actually pays.

  • Replacement parts settled at full value with no depreciation deducted
  • Materially higher settlements on plastic, rubber and fibre components
  • Predictable outcomes — you pay the excess and little else
View Details

2 Wheeler

Cover for a bike or scooter — where third-party is compulsory and own-damage is what actually pays you.

  • Third-party liability is covered without limit for injury and death claims
  • Own-damage cover pays for accident repair, fire and theft of your own bike
  • Long-term policies of two or three years lock the premium and remove renewal lapses
View Details

Today Protected. Tomorrow Stronger.

Why Vehicle Insurance?

  • Unlimited third-party injury liability, as the statute requires
  • Own damage covered for collision, fire, theft and natural calamity
  • Zero depreciation removes the deduction that shrinks most claims
  • Cashless repair across a network of garages, with the insurer paying directly
  • No-claim bonus reaching 50% of the own-damage premium after five clear years

More than Policies A Partner for Life

What's Covered?

  • Third-party death and injury — unlimited by statute
  • Third-party property damage up to the statutory limit
  • Accidental damage to your own car
  • Fire, explosion, self-ignition and lightning
  • Theft, including break-in damage
  • Flood, storm, earthquake, landslide and other natural calamities
View complete coverage

What's Not Covered?

  • Depreciation on replaced parts, unless zero depreciation is added
  • Engine damage from water ingress or oil leakage, unless engine protection is added
  • Consumables and non-standard fittings not declared
  • Mechanical and electrical breakdown, and normal wear
  • Driving without a valid licence or under the influence
  • Use for hire or reward on a private-use policy — including commercial ride-hailing
View all details

Compare Popular Plans

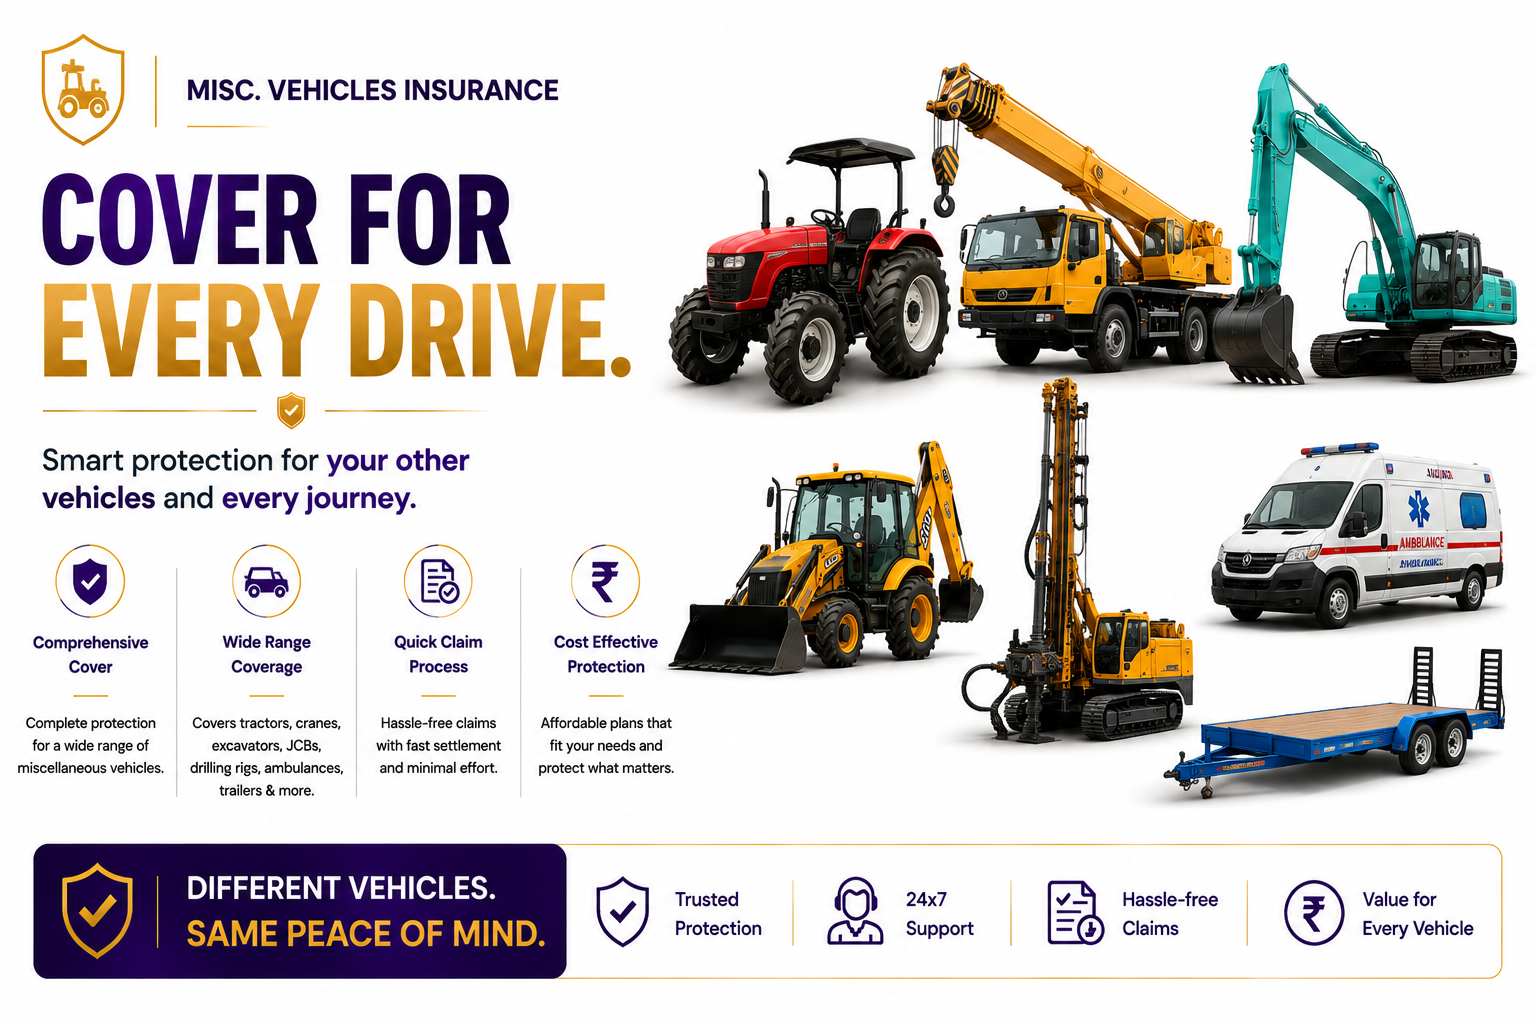
Plan Private Car Zero Dep Plan 2 Wheeler Misc. Vehicles
Best for Drive worry-free Full claim, zero loss Ride safe Cover for every drive
Premium from* ₹6,500 ₹8,500 ₹1,100 ₹9,000
Rating 4.6 4.7 4.4 4.1
Details View View View View

*Indicative starting figures; the final terms depend on your profile.

Compare Plans

Already have insurance?

Review your existing policies and ensure you're truly protected.

  • Find coverage gaps
  • Avoid duplications
  • Check renewal dates
  • Get expert recommendations

Get your current cover reviewed

Share it with an advisor — no cost, no obligation

We're Here After You Buy Too.

Frequently Asked Questions

View All FAQs
What does zero depreciation actually change?

Without it, the insurer deducts depreciation on every replaced part — up to 50% on plastic and rubber, which is most of a modern bumper assembly. With it, those parts are settled at full value. On a car under five years old it usually pays for itself in a single claim.

Is engine damage covered by a comprehensive policy?

Not if it results from water ingress or from continuing to run the engine after a leak. Both are standard exclusions, and both are common in monsoon flooding. Engine protection is the add-on that covers them, and in a flood-prone city it is close to essential.

How is IDV decided and can I change it?

It starts from the manufacturer's listed price less a depreciation scale based on the vehicle's age. Insurers allow some movement around that figure. A lower IDV reduces the premium and reduces the theft or total-loss settlement by the same logic, so set it close to real market value.

Should I claim for a small dent?

Often not. A claim resets your no-claim bonus, which can be worth half the own-damage premium after five clear years, and you still pay the compulsory excess. For minor damage, compare the repair cost with the bonus you would give up before deciding.

Does my policy cover me if I use the car for ride-hailing?

Not under a private-use policy. Carrying passengers for hire or reward requires commercial cover. Insurers do check the vehicle's use at claim stage, and an undeclared commercial use is a clean basis for repudiation.

Not sure what vehicle insurance you need?

Tell us about your needs. Our experts will help you find the right cover.

Talk to an Expert

Speak to an advisor

Good decisions begin with clarity.

Tell us where you are today. We’ll help you understand what matters, what may be missing, and what you can do next.

See the full picture
Understand what you already have and where it stands.
Find what's missing
Identify the gaps that could affect your family, wealth or business.
Know what to do next
Get practical guidance built around your priorities — not a product pitch.

No pressure. No obligation. Just a thoughtful conversation.

Let's Connect

Your details are safe & confidential. We'll contact you only regarding your enquiry.