
Get Expert Guidance
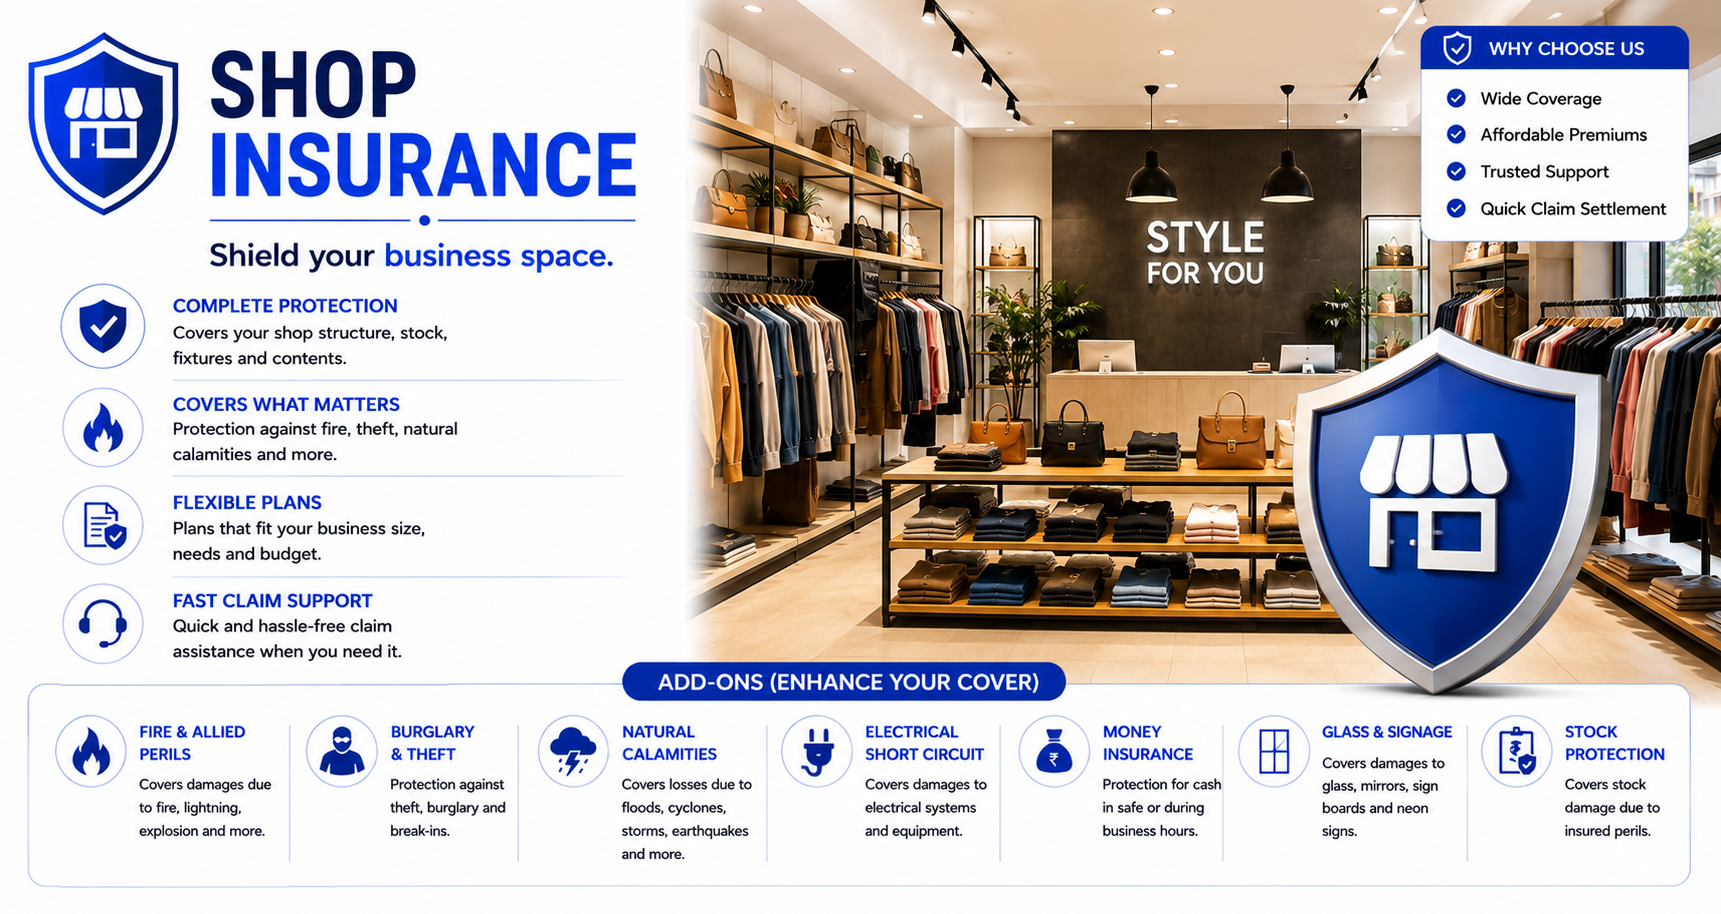
What Our Plans Cover
-
Building and fit-out
-
Stock in trade
-
Furniture
-
Fire
-
Burglary and housebreaking
-
Plate glass and signage
-
Money in the till and in transit
-
Public liability to customers and...
Who Can Consider This Plan?
- Legal ownership, or an insurable interest such as a lease
- Property of permanent construction, meeting the insurer's standards
- Accurate declaration of occupancy and use
- Sum insured set on a defensible valuation basis
- Compliance with any fire safety requirements applicable to the premises
What May Not Be Covered?
- Stock above the declared sum insured — the seasonal trap
- Shoplifting and theft without forcible entry
- Employee dishonesty, unless a fidelity cover is taken
- Money left in unsecured premises overnight beyond the limit
- Wear, tear and gradual deterioration
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
A shop policy covers the premises, the fit-out, the stock and the equipment, along with the liabilities that come from having the public on your floor. It is usually written as a package, because a shopkeeper needs four or five covers and does not want four or five policies.
Stock is the component that causes most difficulty. It fluctuates — sharply, around festivals — and a policy insured at average stock will under-pay a loss occurring at peak. A declaration policy, which adjusts premium against declared monthly stock, is the correct answer for a business with seasonal swings.
Business interruption is the cover most shops omit and most need. A fire that closes a shop for three months destroys three months of income as well as the stock, and only interruption cover replaces it.
Who should consider it
Retailers of every size, from a single counter to a chain of outlets. Shops in malls, where the landlord frequently requires cover contractually. Any shop holding significant stock or expensive fit-out.
Benefits
- One package covering premises, fit-out, stock and liability
- Burglary cover for stock and cash
- Public liability for customers on the premises
- Business interruption to replace lost income after a closure
- Plate glass cover, a frequent and irritating retail loss
- Declaration basis available for stock that fluctuates seasonally
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Building and fit-out, where you own or have improved them
- Stock in trade
- Furniture, fixtures and equipment
- Fire, flood, storm and other natural perils
- Burglary and housebreaking
- Plate glass and signage
- Money in the till and in transit, up to stated limits
- Public liability to customers and visitors
Typically not covered
- Stock above the declared sum insured — the seasonal trap
- Shoplifting and theft without forcible entry
- Employee dishonesty, unless a fidelity cover is taken
- Money left in unsecured premises overnight beyond the limit
- Wear, tear and gradual deterioration
- Consequential loss without business interruption cover
- Goods held on behalf of others, unless declared
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 We value the risk before we quote it Reinstatement cost of the structure, current value of the contents, and what a total loss would actually cost to rebuild today.
- 2 Perils matched to the location A coastal warehouse, a basement in a flood-prone city and a first-floor office are three different risks. The policy should reflect which one you are.
- 3 Quotes compared on sum insured basis, not premium Market value against reinstatement value changes what you receive far more than the premium difference between insurers.
- 4 Survey where the value warrants it Larger risks are surveyed before cover. It is also the moment to fix anything that would reduce a claim later.
- 5 Policy issued, and reviewed annually We revisit the sum insured every renewal. Under-insurance is the single most common reason property claims are cut.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Set the stock sum insured against your peak, not your average. A shop that triples stock before a festival and insures at its annual average is heavily under-insured for the highest-risk weeks of the year.
- Take business interruption. Replacing stock does not replace the three months of trading you lose while the shop is rebuilt, and that is usually the larger number.
- Burglary cover generally requires forcible entry. Shoplifting is not burglary, and employee theft needs a separate fidelity cover.
- If you hold goods on consignment or on behalf of customers, declare them. They are not automatically covered by a stock sum insured.
- Where the shop is in a mall, read the lease. Landlords frequently specify minimum liability limits, and non-compliance is a lease breach as well as an exposure.
Documents required
- Proof of ownership or the lease agreement
- Details of construction — age, materials, number of floors
- Valuation or reinstatement cost estimate of the structure
- Inventory and value of contents, stock or equipment
- Details of fire protection and security arrangements
- Previous policy and claims history, where applicable
- Photographs of the premises, for larger risks
Frequently Asked Questions
My stock triples before Diwali. How should I insure it?
On a declaration basis, where you declare stock monthly and premium adjusts to match. A fixed sum insured set at your annual average leaves you badly under-insured during exactly the weeks when the stock is highest and the risk greatest.
Is shoplifting covered?
No. Burglary cover requires evidence of forcible entry. Shoplifting is a trading loss, and employee theft needs a separate fidelity guarantee cover.
What does business interruption actually pay?
Your lost gross profit and continuing fixed costs while the shop cannot trade, for the indemnity period you choose. It is the difference between recovering your stock and recovering your business, and it is the cover shops most often skip.
Am I liable if a customer slips in my shop?
Potentially yes, and public liability cover responds to exactly that. It is included in most shop packages, though the limit is often set too low relative to the exposure — check it rather than accepting the default.
Does it cover the fit-out if I am a tenant?
Yes, where you paid for the improvements. The landlord insures the structure; your fit-out, fixtures and equipment are yours to insure, and on a well-finished retail unit they are worth a great deal.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.