
Plan your investment
What Our Plans Cover
-
Units in a trust holding mortgages...
-
Distributions from interest income
-
Exposure to residential or commerc...
-
Listed trading where available
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, subject to the applicable investment routes
- A demat account and a trading account
- PAN and completed KYC
- Minimum investment as per the exchange lot size
What May Not Be Covered?
- Ownership of physical property
- Rental income and its inflation linkage
- Protection against interest rate movements
- Protection against borrower defaults
- An established Indian retail market for this structure
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
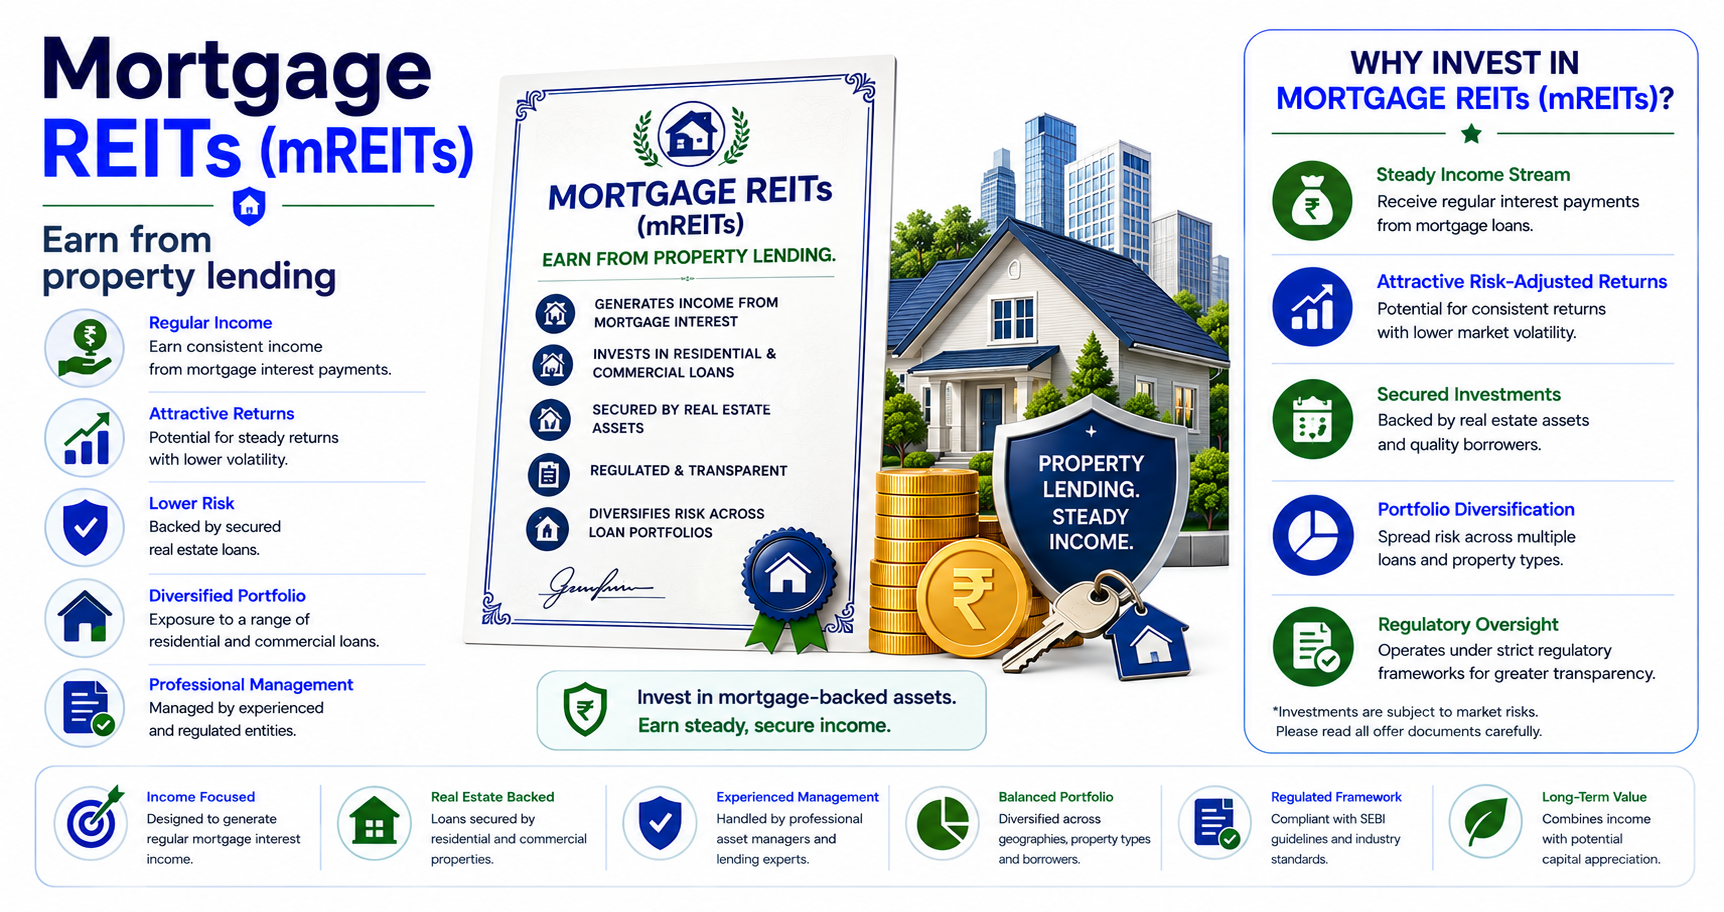
A mortgage REIT holds property loans and mortgage-backed securities rather than buildings. Its income comes from the interest on those loans, and its profit from the spread between what it earns on assets and what it pays to fund them.
That structure makes it behave quite differently from an equity REIT. There is no rent, no occupancy and no building — the drivers are interest rates, credit quality of the borrowers, and the cost and availability of the trust's own funding.
Mortgage REITs are a developed feature of the US market and are not an established retail category in India. Indian investors encountering them are generally doing so through international exposure, and the structure carries leverage risk that is easy to underestimate.
Who should consider it
Sophisticated investors familiar with mortgage credit and interest rate risk. Investors with international exposure who understand the specific structure. Anyone allocating a small satellite position with a genuine view on rate direction.
It is not appropriate for an investor seeking straightforward property exposure — an equity REIT does that job.
Benefits
- Income from interest on property loans rather than rent
- Yields that can exceed equity REITs in favourable rate conditions
- Exposure to property finance without property ownership
- Liquidity through listed units
- Diversification from direct rental income exposure
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Units in a trust holding mortgages and mortgage-backed securities
- Distributions from interest income
- Exposure to residential or commercial mortgage credit
- Listed trading where available
Not included
- Ownership of physical property
- Rental income and its inflation linkage
- Protection against interest rate movements
- Protection against borrower defaults
- An established Indian retail market for this structure
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 We explain what a REIT actually is first Not a property purchase and not a fixed deposit. A listed security whose income comes from rent, and whose price moves with markets.
- 2 Distribution yield examined properly Yield alone is not the answer. The mix of rent, occupancy, lease expiries and debt is what tells you whether it is sustainable.
- 3 Allocation sized against your existing property exposure Most Indian households already hold a great deal of real estate. A REIT should complement that, not concentrate it further.
- 4 Purchase through the exchange REIT units trade like shares and settle into your demat account. The mechanics are simple; the analysis is where the work is.
- 5 Distributions tracked and taxed correctly REIT distributions have several components with different tax treatments. We make sure they are reported properly.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- This is a leveraged spread business, not a property investment. The economics depend on borrowing cheaply and lending dearer, and that spread can compress quickly.
- Rate movements affect these trusts sharply in both directions. A view on rates is effectively required, which is a different exercise from assessing a building.
- Credit quality of the underlying borrowers matters as much as rates. A rising default rate damages the trust regardless of what rates do.
- This is not an established Indian retail category. Exposure typically comes through international routes, with the currency and disclosure considerations that implies.
- If your objective is property exposure, an equity REIT does that directly. This is a financial exposure that happens to reference property.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Demat account details
- Bank account proof for distribution credit
- Completed KYC with the broker
Frequently Asked Questions
How is this different from an ordinary REIT?
An equity REIT owns buildings and collects rent. A mortgage REIT holds property loans and collects interest, profiting from the spread between what it earns and what it pays to fund itself. There is no rent, no occupancy and no building — the drivers are rates and credit.
Why are they so sensitive to interest rates?
Because the business is a spread between borrowing and lending, usually with leverage. When funding costs rise faster than asset yields, the spread compresses and the economics deteriorate quickly. That sensitivity works in both directions.
Are these available in India?
Not as an established retail category. Indian REIT regulations have focused on equity REITs holding income-producing property. Investors encountering mortgage REITs are generally doing so through international exposure.
What is the main risk?
Leverage combined with rate and credit risk. Each is manageable individually; together, in a leveraged structure, they can produce outcomes considerably worse than the underlying loan book would suggest.
Is this a good way to get property exposure?
No. If you want property exposure, an equity REIT owning buildings and collecting rent does that directly. A mortgage REIT is a financial exposure that references property, and it behaves like credit rather than like real estate.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.