
Plan your investment
What Our Plans Cover
-
Investment in overseas equity and...
-
Fund-of-fund structures feeding in...
-
Country
-
SIP and lumpsum options
-
Growth and income distribution opt...
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, subject to the fund house accepting the country of residence
- Completed KYC with a registered KYC registration agency
- PAN, which is mandatory for all mutual fund investments
- A bank account in the investor's own name for transactions
What May Not Be Covered?
- Any protection against currency movement
- Any guarantee of return
- Investment beyond the industry-wide overseas limits, when those are reached
- Equity taxation treatment, on many global funds
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
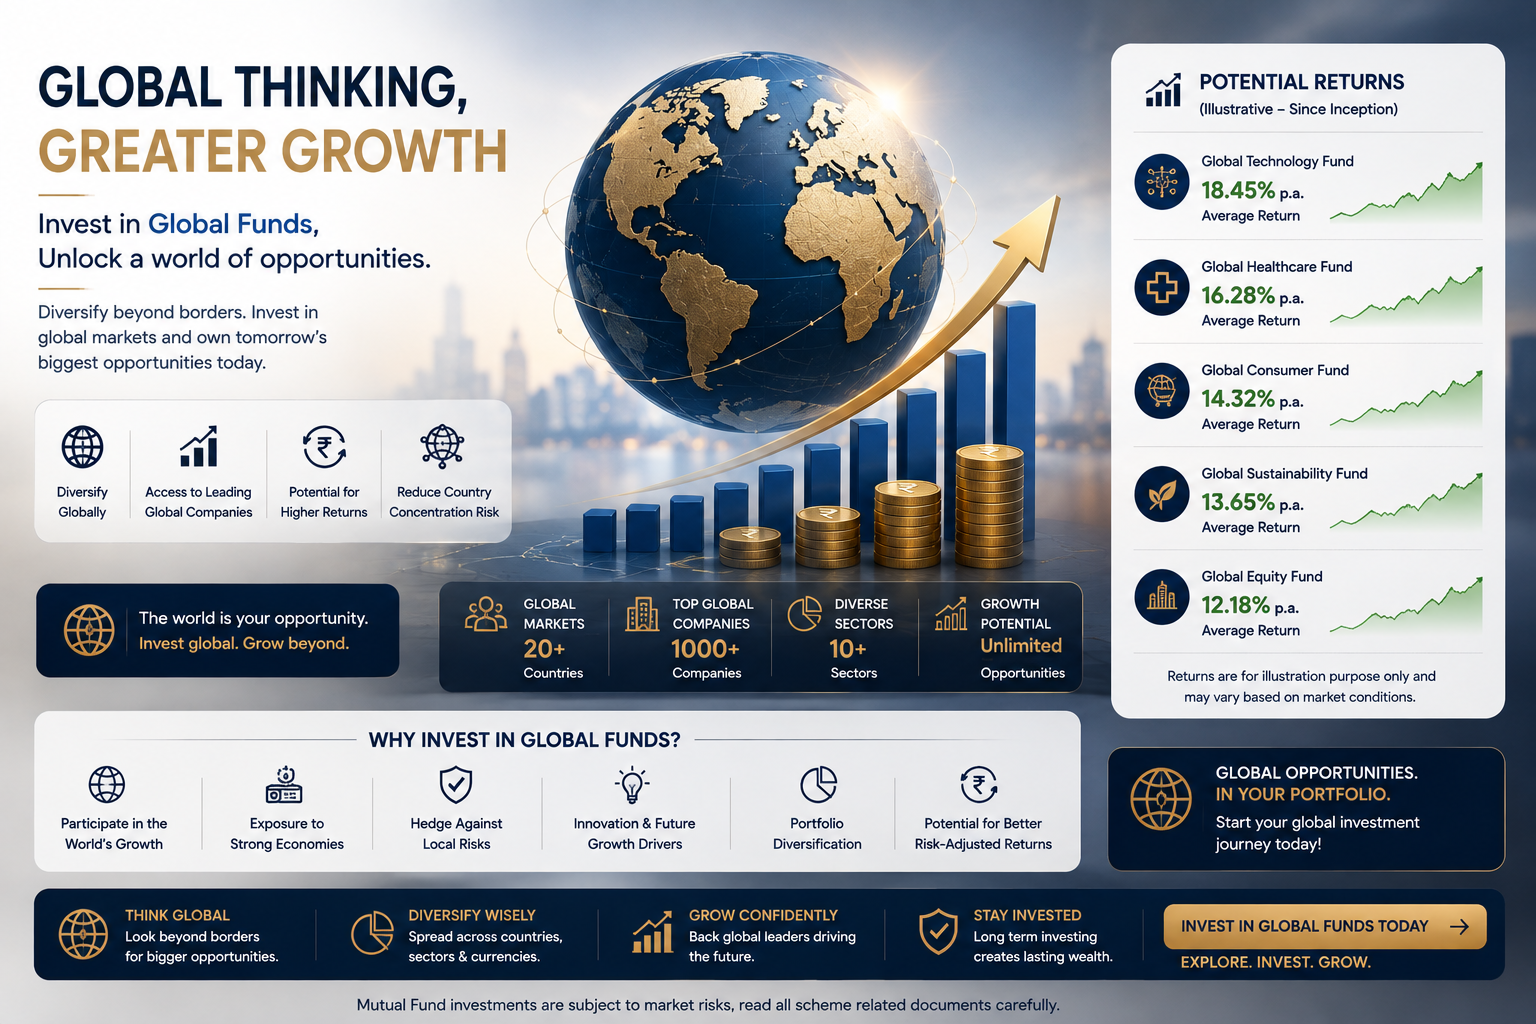
Global and offshore funds invest in securities outside India, either directly or by feeding into an overseas fund. They give an Indian investor exposure to companies, sectors and economies not available on domestic exchanges.
The case for them is diversification. An entirely domestic portfolio is a concentrated bet on one economy, one currency and one policy environment. Adding international exposure reduces that concentration, and the technology and healthcare sectors in particular have very limited domestic equivalents.
Currency is a second, independent source of return and risk. Returns come in foreign currency and are converted to rupees, so a depreciating rupee adds to your return and an appreciating one subtracts from it — regardless of how the underlying investments performed.
Who should consider it
Investors with an established domestic portfolio adding geographic diversification. Investors with future foreign currency liabilities — a child's overseas education, planned travel or migration. Anyone seeking exposure to sectors with no meaningful Indian equivalent.
Benefits
- Diversification away from a single-economy portfolio
- Access to companies and sectors without domestic equivalents
- Currency exposure that can add to rupee returns
- A natural hedge against future foreign currency expenses
- Professional management of international portfolios
- Available through ordinary SIP and lumpsum routes
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Investment in overseas equity and debt securities
- Fund-of-fund structures feeding into overseas schemes
- Country, regional and global mandates
- SIP and lumpsum options
- Growth and income distribution options
Not included
- Any protection against currency movement
- Any guarantee of return
- Investment beyond the industry-wide overseas limits, when those are reached
- Equity taxation treatment, on many global funds
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 Goal and horizon before fund selection What the money is for and when you need it decides the asset class. The fund name is the last decision, not the first.
- 2 Risk profiling that is honest rather than flattering Capacity to take risk and willingness to sit through a fall are different things. We assess both, because the second is what breaks plans.
- 3 Shortlist built on process, not last year's return Mandate, expense ratio, fund manager tenure and how the fund behaved in a bad year. Past performance is not a forecast.
- 4 KYC, onboarding and the first investment One-time KYC, then the folio and the mandate. We set up the SIP so it runs without depending on you remembering.
- 5 Review annually, rebalance deliberately A yearly review against the goal, not a monthly reaction to markets. Most damage in investing is self-inflicted.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Currency is a second source of return and risk. A fund can perform well in dollar terms and disappoint in rupee terms if the rupee strengthens, and the reverse also applies.
- Check the tax treatment of your specific scheme. Many global funds are taxed as non-equity schemes, which materially changes after-tax returns.
- Regulatory limits on overseas investment apply industry-wide and have periodically caused fund houses to suspend fresh subscriptions. It is a real constraint, not a theoretical one.
- If you have a future foreign currency liability — overseas education is the common one — this exposure is a genuine hedge rather than just diversification.
- Mutual fund investments are subject to market risk. Global funds add currency risk to that.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Cancelled cheque or bank account details
- Recent passport-size photograph
- Completed KYC, or KYC documents to complete it
- FATCA and nominee declaration
Frequently Asked Questions
Why invest outside India at all?
Because an entirely domestic portfolio is a concentrated bet on one economy, one currency and one policy environment. International exposure reduces that concentration, and it provides access to technology and healthcare businesses with very limited Indian equivalents.
How does the currency affect my return?
Directly and independently of the underlying investments. Returns are earned in foreign currency and converted to rupees, so a depreciating rupee adds to your return and an appreciating one subtracts from it. A fund can do well in dollar terms and disappoint in rupee terms.
How are global funds taxed?
Many are treated as non-equity schemes for tax purposes even though they hold equities, which changes the holding period and rate that apply. Check the classification of your specific scheme, because it materially affects after-tax returns.
Why do some global funds stop accepting money?
Regulatory limits on total overseas investment by Indian mutual funds apply industry-wide. When those limits are approached, fund houses suspend fresh subscriptions. It has happened before and is a genuine practical constraint on this category.
How much should I allocate internationally?
A meaningful but minority portion of the portfolio, sized against your horizon and any future foreign currency needs. Investors funding an overseas education have a specific reason to hold more, since the exposure hedges the liability directly. Market risk and currency risk both apply.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.