
Get Expert Guidance
What Our Plans Cover
-
Accidental damage to goods during...
-
Overturning
-
Fire
-
Theft and non-delivery of the whol...
-
Damage during loading and unloadin...
-
Natural calamities affecting the t...
-
Riot
-
Transhipment between vehicles or m...
Who Can Consider This Plan?
- Insurable interest in the goods at the time of loss
- Cover arranged before the transit begins
- Goods packed appropriately for the mode of transport
- Accurate declaration of the nature and value of the cargo
- Voyage within the territorial limits stated in the policy
What May Not Be Covered?
- Inherent vice and the ordinary nature of the goods
- Insufficient or unsuitable packing
- Ordinary leakage, loss in weight and wear
- Delay, and any loss arising from it
- Wilful misconduct of the insured
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
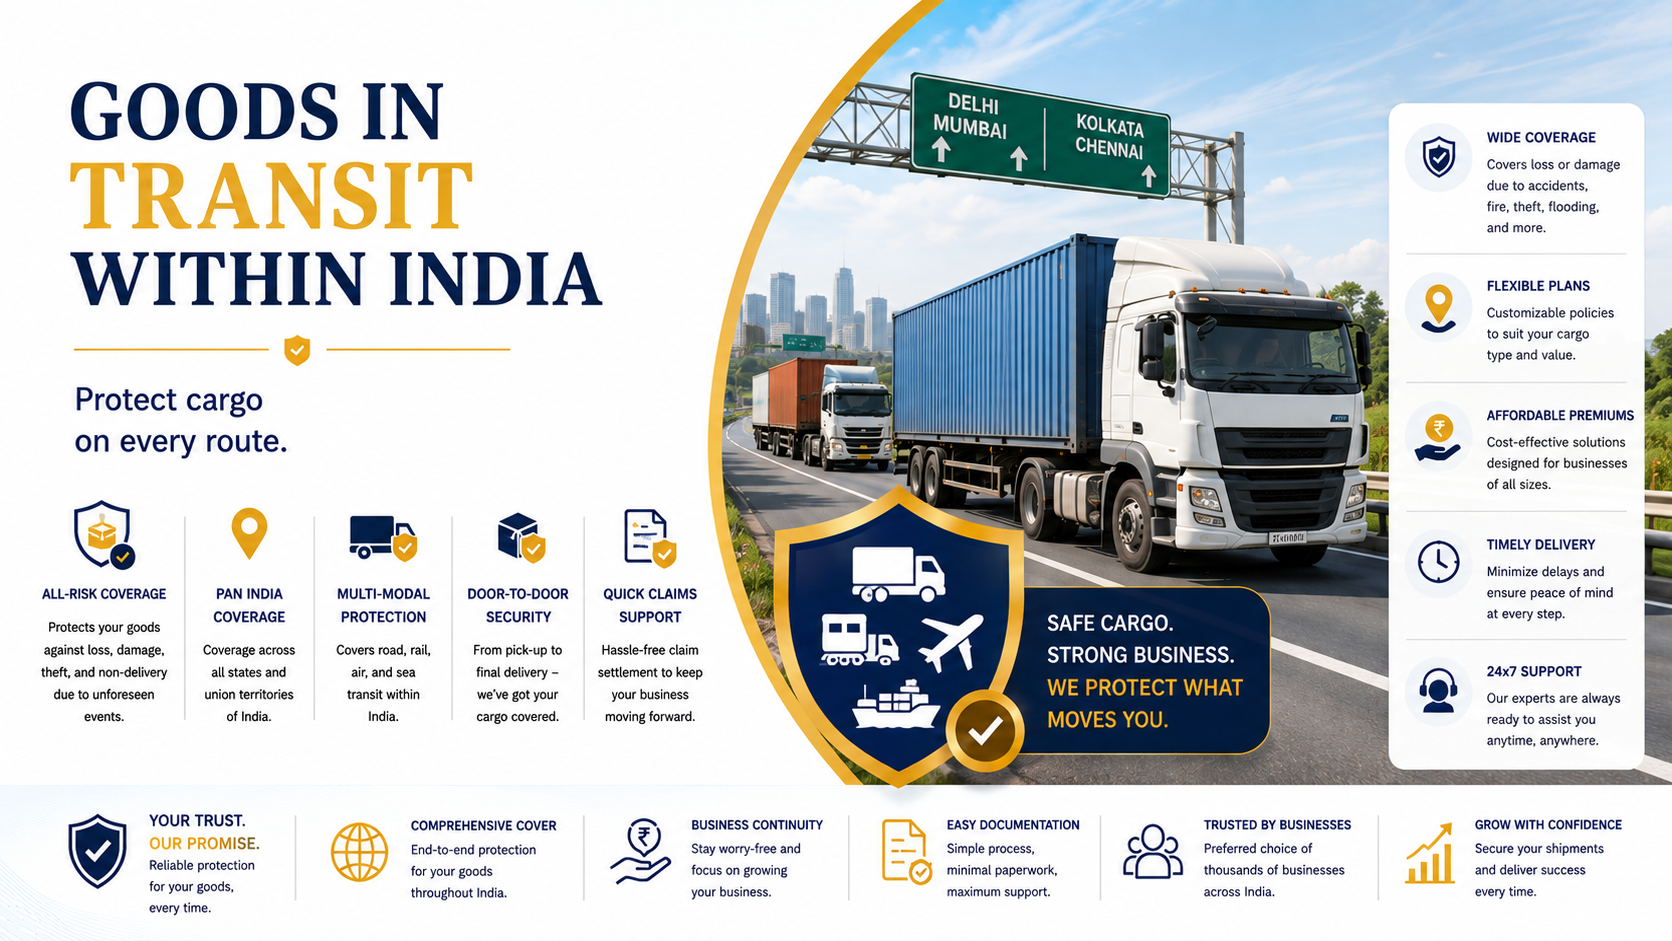
Inland transit insurance covers goods moving within India by road, rail or inland waterway. It is separate from the motor policy on the vehicle, which insures the truck and never the load — a distinction that costs Indian businesses a great deal every year.
The exposure is real and routine. Road transit in India involves multiple handling points, variable packing standards, and a carrier whose liability is limited by contract to a small fraction of the goods' value. Recovering a full loss from a transporter is rarely realistic.
For a business moving goods regularly, an annual open cover is the right structure: every despatch is covered automatically, declarations are made monthly, and no consignment travels uninsured because someone forgot.
Who should consider it
Manufacturers moving raw materials in and finished goods out. Distributors and wholesalers. E-commerce sellers despatching stock. Anyone whose goods travel by road between locations, whether in their own vehicles or a transporter's.
Benefits
- Covers the goods, which no motor policy does
- Annual open cover means no consignment travels uninsured
- Pays the full insured value rather than a carrier's limited liability
- Covers loading and unloading, where most handling damage occurs
- Cover for own-vehicle movements as well as transporter movements
- Recovery pursued against the carrier by the insurer, not by you
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Accidental damage to goods during transit
- Overturning, collision and derailment
- Fire, explosion and lightning during transit
- Theft and non-delivery of the whole consignment
- Damage during loading and unloading
- Natural calamities affecting the transit
- Riot, strike and malicious damage, where covered
- Transhipment between vehicles or modes
Typically not covered
- Inherent vice and the ordinary nature of the goods
- Insufficient or unsuitable packing
- Ordinary leakage, loss in weight and wear
- Delay, and any loss arising from it
- Wilful misconduct of the insured
- Goods carried in an unroadworthy or overloaded vehicle
- Consequential loss, including lost sales
- Pilferage of part of a consignment, unless specifically covered
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 We map the movement, not just the goods Origin, destination, mode, transhipment points and who bears risk at each stage. The Incoterm decides who should be insuring at all.
- 2 Single transit or annual open cover A one-off shipment takes a specific policy. Regular movement takes an open cover with monthly declarations, which is cheaper and never forgotten.
- 3 Clauses chosen deliberately Institute Cargo Clauses A, B or C decide what is actually covered. Most disputes trace back to a C policy where A was needed.
- 4 Cover in force before despatch Marine cover must attach before the goods move. A policy arranged after loading is a policy with a gap at the start.
- 5 Survey and claim handled for you We appoint the surveyor, assemble the documents and pursue recovery against the carrier where one exists.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Your motor policy does not cover the load. This is the most common uninsured exposure in Indian transport, and it is entirely avoidable.
- Carrier liability is limited by the lorry receipt to a fraction of the goods' value. Do not treat the transporter's liability as your insurance.
- Take an annual open cover if you despatch regularly. Single policies get forgotten, and the consignment that travels uninsured is the one that overturns.
- Packing is a condition, not a detail. Losses traced to insufficient packing are excluded, and the surveyor will examine it.
- Insure on invoice value plus freight plus a margin. Insuring at cost leaves you short of what the loss actually costs you.
Documents required
- Commercial invoice and packing list
- Bill of lading, airway bill or lorry receipt
- Details of the goods — nature, packing and value
- Voyage details — origin, destination, mode and transhipment
- Incoterm agreed with the counterparty
- Letter of credit terms, where the shipment is under one
- Previous claims history, for annual covers
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.