
Plan your investment
What Our Plans Cover
-
Units in an InvIT holding road and...
-
Distributions from toll or annuity...
-
Exposure across multiple assets an...
-
Traffic and collection data in per...
-
Holding in your demat account
Who Can Consider This Plan?
- Indian resident individual, HUF, trust or company
- NRIs, subject to the applicable investment routes
- A demat account and a trading account
- PAN and completed KYC
- Minimum investment as per the exchange lot size
What May Not Be Covered?
- Protection against traffic volumes falling on toll assets
- Protection against concession authority payment delays
- Perpetual asset life; concessions expire
- Any guarantee of distribution
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading investments companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced investments professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
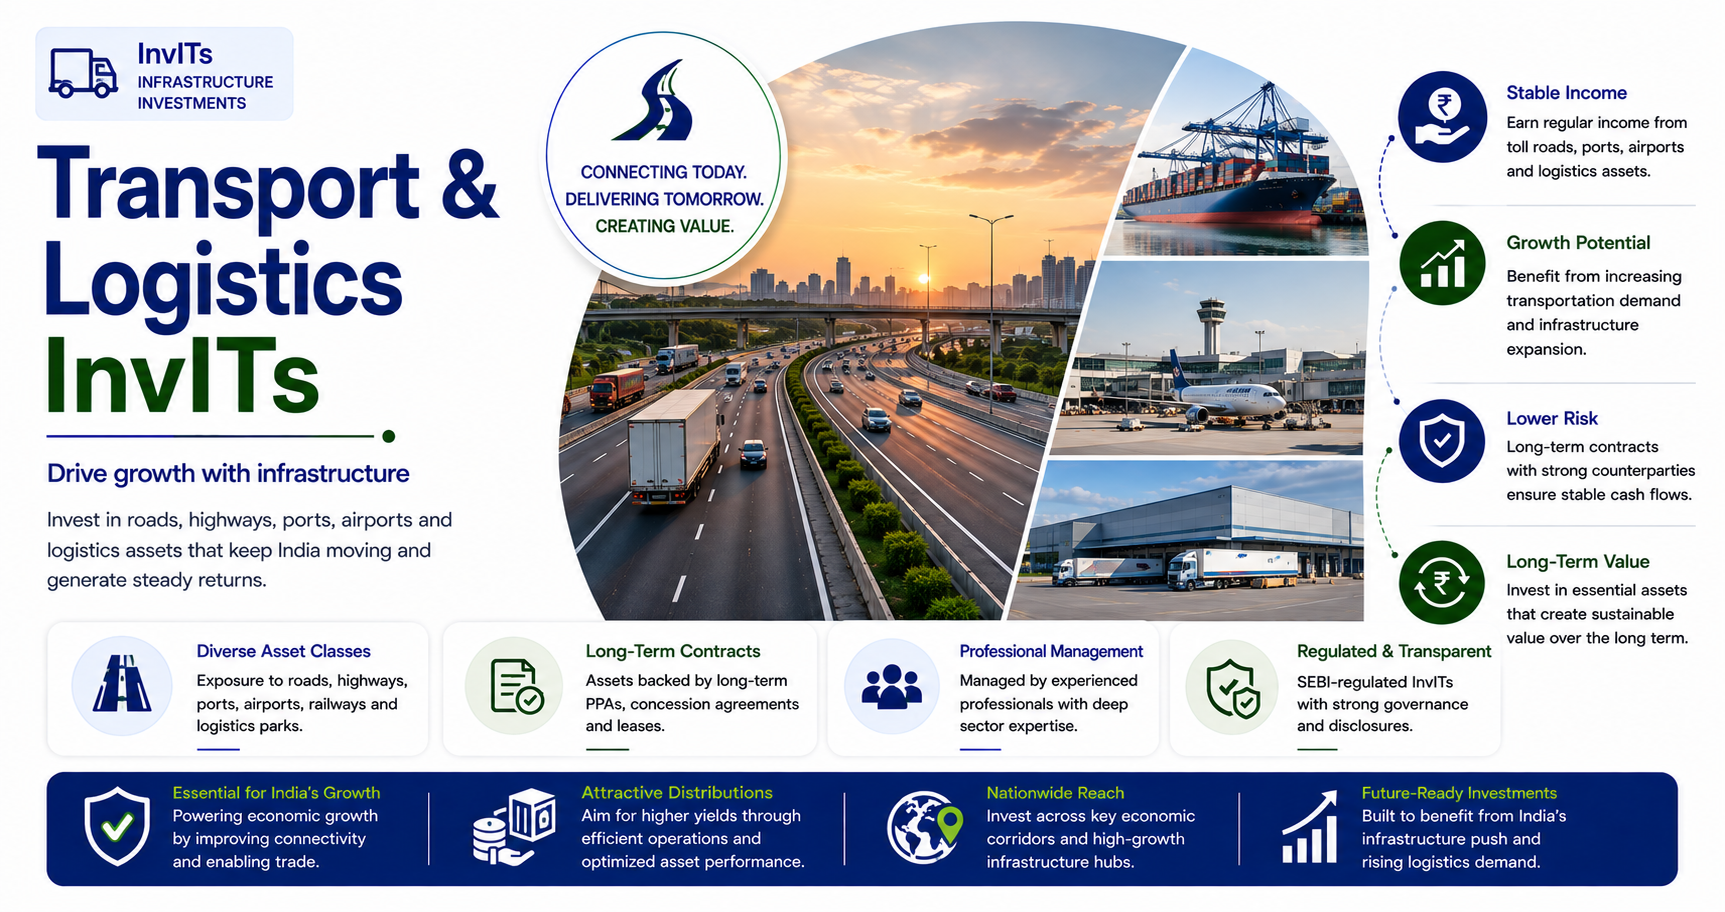
Transport InvITs hold roads, highways and related transport infrastructure. Revenue comes either from toll collection, which varies with traffic, or from annuity payments under a concession, which do not.
The distinction between those two matters enormously. A toll road's revenue depends on how many vehicles use it, which is affected by economic activity, competing routes and fuel prices. An annuity road receives fixed payments from the concession authority for making the road available, regardless of traffic.
Both operate under concessions with defined end dates, after which the road reverts to the authority. Major periodic maintenance obligations also fall due at intervals, and a trust that has not provided for them adequately will find distributions squeezed when they arrive.
Who should consider it
Income-focused investors comfortable with traffic or concession-authority exposure. Investors who understand the difference between toll and annuity revenue. Anyone diversifying infrastructure exposure beyond energy assets.
Benefits
- Exposure to operating road and transport infrastructure
- Annuity assets provide revenue independent of traffic volumes
- Toll assets participate in traffic growth over time
- Long concession periods providing visibility
- Regulated distribution of the majority of cash flows
- Listed liquidity
What is included, and what is not
Read the right-hand column first. It is the one that tends to surprise people later.
Included
- Units in an InvIT holding road and transport assets
- Distributions from toll or annuity revenue
- Exposure across multiple assets and corridors
- Traffic and collection data in periodic disclosure
- Holding in your demat account
Not included
- Protection against traffic volumes falling on toll assets
- Protection against concession authority payment delays
- Perpetual asset life; concessions expire
- Any guarantee of distribution
Terms vary between providers and between plans from the same provider. The offer document you receive is what governs — we will walk you through it before you commit.
How it works with us
- 1 We explain the finite-life point first Most InvIT assets have a concession period. Part of the yield is your own capital returning, and that changes how to read it.
- 2 Distribution quality examined, not just the number How much is genuinely surplus cash and how much is capital return, and what happens to it as the concession runs down.
- 3 Counterparty and concession terms read carefully Who pays the revenue, under what contract, and for how long. That is where the real risk in an InvIT sits.
- 4 Purchase through the exchange Listed InvIT units trade like shares and settle into your demat account.
- 5 Distributions tracked and taxed by component Interest, dividend and return of capital are taxed differently. Reporting them correctly is part of holding these.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Establish the split between toll and annuity assets. They carry fundamentally different risks and a portfolio weighted to one behaves quite differently from the other.
- For toll assets, look at actual traffic history rather than projections. Traffic forecasts in Indian road projects have a long record of optimism.
- Competing routes matter. A new parallel highway can materially reduce traffic on an existing toll road for the remainder of its concession.
- Major maintenance obligations fall due at intervals and are substantial. Check that the trust has provided for them.
- Weighted average remaining concession life tells you how much of the portfolio's earning period is left.
Documents required
- PAN card
- Aadhaar or other identity proof
- Address proof
- Demat account details
- Bank account proof for distribution credit
- Completed KYC with the broker
Frequently Asked Questions
What is the difference between toll and annuity roads?
A toll road earns from vehicles using it, so revenue varies with traffic. An annuity road receives fixed payments from the concession authority for keeping the road available, regardless of how many vehicles use it. They are genuinely different risk profiles, and knowing the split in a portfolio is essential.
How reliable are traffic projections?
Historically, not very. Traffic forecasts in Indian road projects have a long record of optimism, which is why actual operating history matters far more than a projection. For an operating asset that history is available — use it.
What happens if a competing highway opens?
Traffic on the existing route can fall materially for the remainder of the concession, with no compensation in most structures. Checking the corridor for planned parallel capacity is a genuinely useful piece of diligence.
What about maintenance costs?
Roads carry major periodic maintenance obligations that fall due at intervals and are substantial. A trust that has not provided for them adequately will find distributions squeezed when they arrive, so look for how these are funded.
What happens at the end of the concession?
The road reverts to the concession authority and stops generating revenue for the trust. Weighted average remaining concession life across the portfolio tells you how much earning period is left, and what the trust is acquiring to replace it.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.