
Check your eligibility
What These Loans Fund
-
The outstanding principal on the e...
-
A top-up amount
-
A fresh tenure
-
Consolidation of more than one loa...
Who Can Consider This Loan?
- Indian resident, generally aged 21 to 60
- Salaried: minimum monthly income set by the lender and city
- Self-employed: two to three years of business vintage with filed returns
- Credit score is the dominant factor in both approval and rate
- Total EMI obligations usually capped at 50 to 55% of net income
- Employment with a recognised employer improves both terms and speed
What May Not Be Funded?
- Foreclosure charges on the existing loan
- Processing fee on the new loan
- Interest already paid
- Transfers where the remaining tenure is too short to justify the costs
Always check the sanction letter before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading loans companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
- Expert Guidance Personalised advice from experienced loans professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
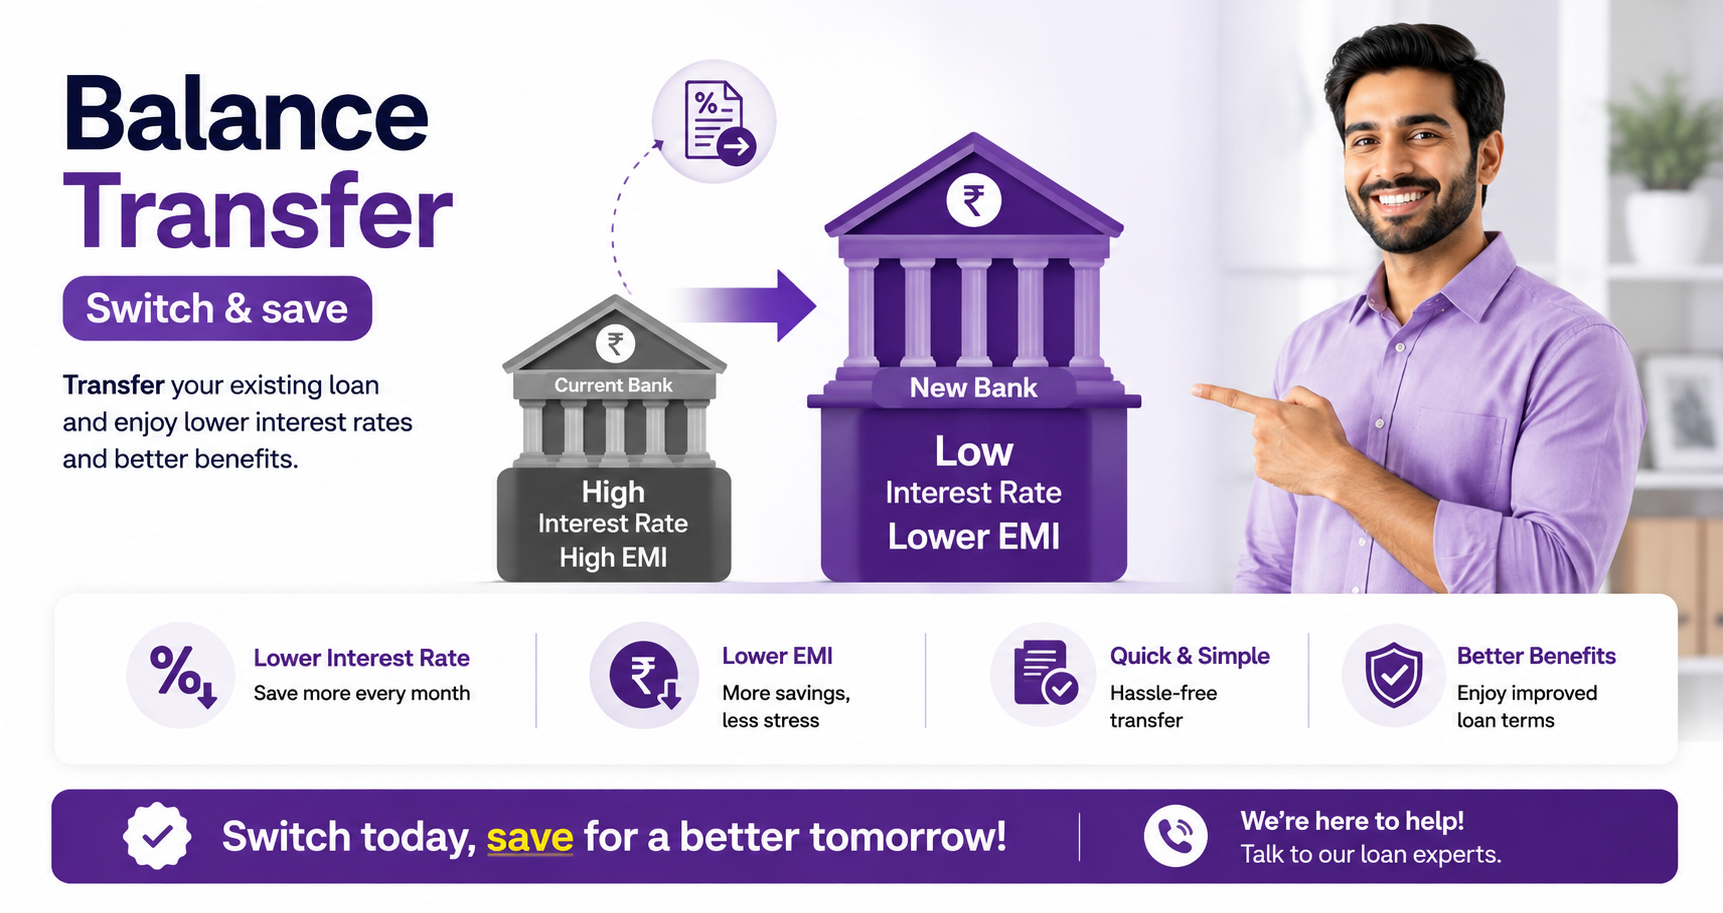
A personal loan balance transfer moves your outstanding balance to a new lender at a lower rate. The new lender clears the existing loan and you continue with a fresh EMI at the better rate.
It is most worthwhile where your credit profile has improved since the original loan. A borrower who took a loan at eighteen per cent with a thin credit history, and has since built two years of clean repayment, may be eligible for materially better pricing.
The arithmetic depends on remaining tenure. With four years left on a substantial balance, a three-point rate reduction is a meaningful saving. With eighteen months left, the foreclosure charge and fresh processing fee will usually consume the benefit entirely.
Who should consider it
Borrowers whose credit score has improved materially since the original loan. Borrowers with a substantial balance and at least two years remaining. Anyone who took a loan at a high rate during a period of thin credit history.
Benefits
- A lower rate reduces both EMI and total interest
- An improved credit profile since sanction can be monetised
- Tenure can be restructured at the same time
- A top-up is often available alongside
- Opportunity to move to a lender with better service
- Multiple loans can sometimes be consolidated in the transfer
What the loan funds, and what it does not
Read the right-hand column first. It is the one that decides how much you have to arrange yourself.
Usually funded
- The outstanding principal on the existing loan
- A top-up amount, where eligibility supports it
- A fresh tenure, which can be shorter or longer
- Consolidation of more than one loan, at some lenders
Usually not funded
- Foreclosure charges on the existing loan
- Processing fee on the new loan
- Interest already paid
- Transfers where the remaining tenure is too short to justify the costs
Funding limits and the treatment of add-ons vary between lenders and move with the borrower profile. The sanction letter you receive is what governs — we will walk you through it before you sign.
How it works with us
- 1 Eligibility checked before any application is filed Each rejected application marks your credit file. We match your profile to lenders who will actually approve it, rather than applying everywhere.
- 2 Compared on total cost, not the advertised rate Processing fee, insurance bundling and prepayment terms often matter more than the headline number.
- 3 We name the cheaper alternative if there is one A top-up on your home loan or a loan against securities is often half the cost. If that applies to you, we will say so.
- 4 One document set, submitted once Prepared properly the first time, which is what makes same-day approval realistic.
- 5 Sanction, disbursal and a repayment plan The sanction states rate, fee and prepayment terms. We set out how prepaying would work before you need it.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Do the arithmetic first. Foreclosure charge plus new processing fee against interest saved over the remaining tenure. Under about two years remaining, it usually does not clear.
- Ask your existing lender to reprice before moving. Some will, particularly where your score has improved, and it costs you nothing to ask.
- Do not extend the tenure to reduce the EMI. That reverses the saving you transferred for.
- If you have several loans, ask whether they can be consolidated in the transfer. One EMI at a better rate is usually the stronger outcome.
- Check for a lock-in on the existing loan. Many personal loans prohibit foreclosure in the first six or twelve months entirely.
Documents required
- Identity proof — Aadhaar, PAN or passport
- Address proof
- Salaried: last three months of salary slips and Form 16
- Self-employed: last two years of income tax returns with computation
- Bank statements for the last six months
- Employment proof or business registration
- Recent passport-size photograph
- Existing loan and credit card statements
Frequently Asked Questions
When is a personal loan transfer worth doing?
When the rate gap is wide and at least two years of tenure remain on a substantial balance. Below that, the foreclosure charge and fresh processing fee usually consume the saving. Personal loans are short, so the window in which a transfer pays is narrower than on a home loan.
What makes me eligible for a better rate now?
Most often an improved credit score. A borrower who took a loan at eighteen per cent with thin credit history and has since built two years of clean repayment can frequently access materially better pricing.
Should I ask my current lender first?
Yes, always. Some will reprice to retain you, particularly where your profile has improved. It costs nothing to ask and can achieve the same saving without any paperwork.
What will it cost to move?
A foreclosure charge on the existing loan, which most personal loans apply, plus a processing fee on the new one. Total both before comparing against the interest you would save.
Can I consolidate several loans in the transfer?
Some lenders will combine multiple existing loans into a single new facility, subject to your eligibility. Where you are servicing several EMIs, that is usually a better outcome than transferring one.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.