
Get Expert Guidance
What Our Plans Cover
-
Cancellation or postponement for c...
-
Non-refundable venue
-
Jewellery in transit between locat...
-
Wedding outfits and accessories
-
Gifts and cash received
-
Damage to hired property at the ve...
-
Public liability for injury to gue...
-
Photography and videography failur...
Who Can Consider This Plan?
- Insurable interest in the property or activity being covered
- Accurate declaration of value and, where relevant, provenance
- Security and storage arrangements meeting the insurer's requirements
- Full disclosure of prior losses and claims
- Activity or property within the classes the insurer writes
What May Not Be Covered?
- A change of mind by either party
- Cancellation for reasons known when the policy was bought
- Jewellery left unattended or in an unsecured room
- Jewellery not declared or valued where the policy requires it
- Cash above the stated limit
Always check the policy wording before you commit.
Why Choose Wealth & Covers?
- Expert advice to choose the right plan
- Plans from leading insurance companies
- Hassle-free process and documentation
- End-to-end support, including claim assistance
- Dedicated relationship manager
Our Insurance Partners
- Star Health Insurance
- Care Health Insurance
- Niva Bupa Health Insurance
- HDFC ERGO
- ICICI Lombard
- Bajaj Allianz
We represent multiple providers to help you find the most suitable option at the best price.
- Expert Guidance Personalised advice from experienced insurance professionals.
- End-to-End Support From choosing the right plan to claim assistance, we are with you always.
- Claims Assistance Hassle-free claim support to ensure you get what you deserve.
- Transparent Process Clear information, easy documentation and a hassle-free experience.
Overview
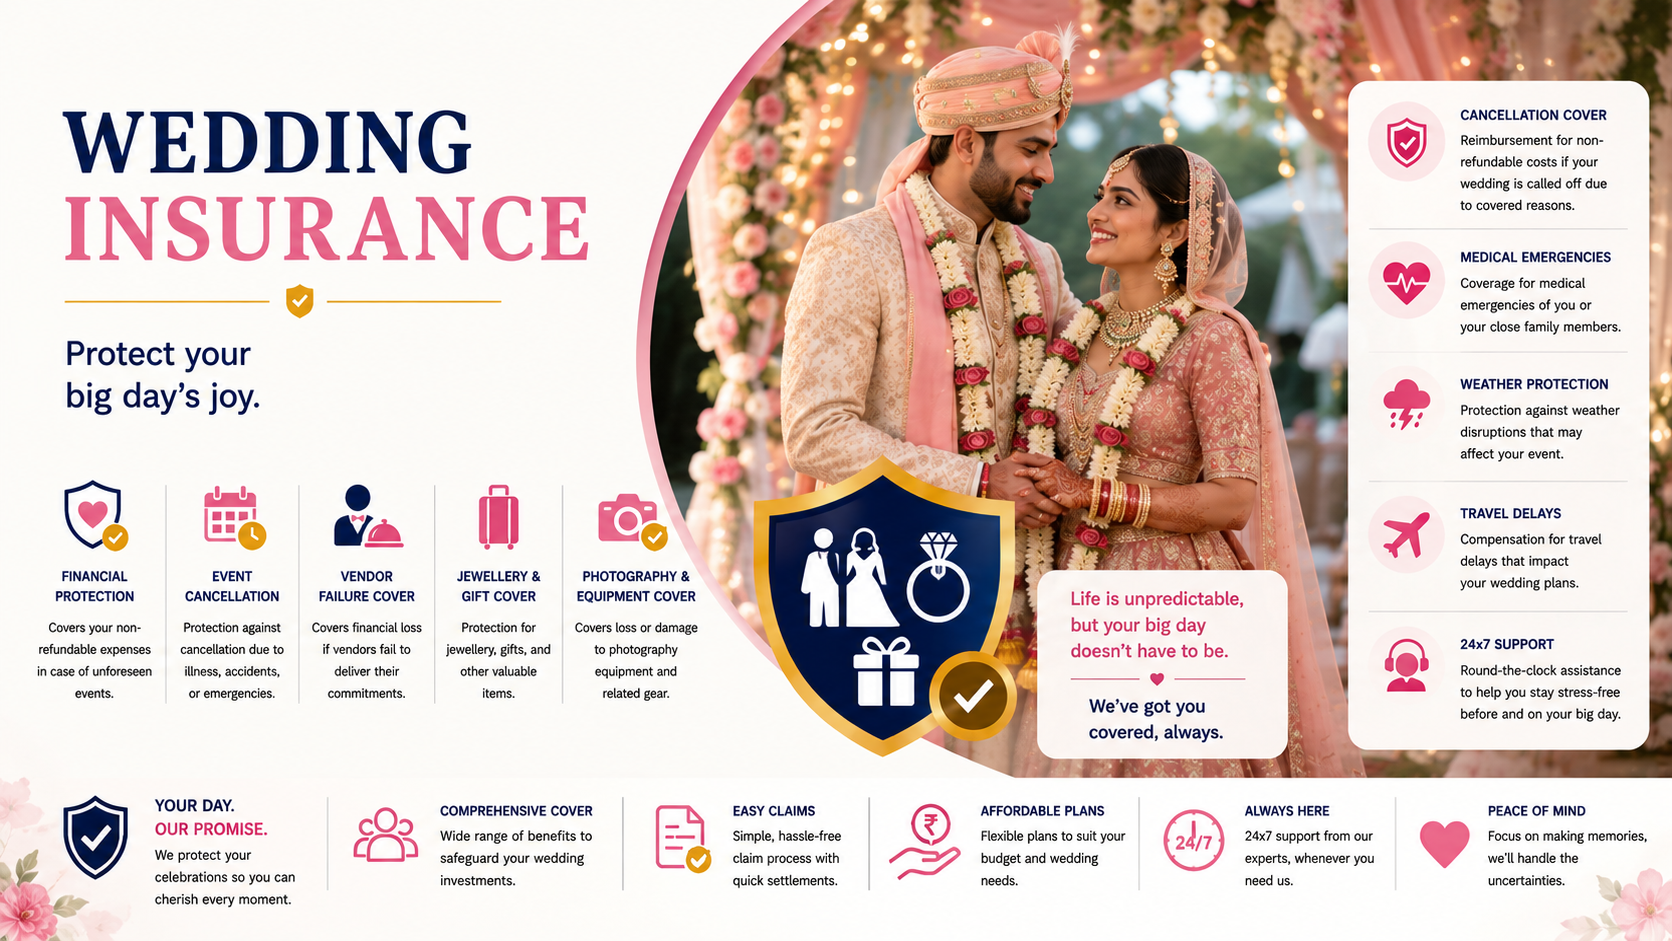
Wedding insurance covers the financial loss if a wedding has to be cancelled or postponed, along with the property risks specific to an Indian wedding: jewellery in transit and on display, outfits, gifts and cash.
Indian weddings involve unusually large committed costs and unusually large concentrations of portable valuables. Venue and catering deposits run to lakhs and are non-refundable. Jewellery moves between homes, hotels and venues over several days, frequently in the care of people who are not thinking about security.
The property side is often the more useful half. Cancellation claims are rare; jewellery going missing during a three-day function is considerably less so.
Who should consider it
Families organising a wedding with substantial committed costs. Anyone whose function involves significant jewellery moving between locations. Destination weddings, where travel and accommodation deposits add materially to the exposure.
Benefits
- Recovers non-refundable deposits if the wedding cannot proceed
- Covers jewellery in transit and on display during the functions
- Covers outfits, gifts and cash within stated limits
- Public liability at the venue for guest injury
- Postponement costs where the event has to be rescheduled
- Cover for the whole sequence of functions, not just the main day
What is covered, and what is not
Read the right-hand column first. It is the one that decides whether a claim is paid.
Typically covered
- Cancellation or postponement for covered reasons
- Non-refundable venue, catering and vendor deposits
- Jewellery in transit between locations and while worn
- Wedding outfits and accessories
- Gifts and cash received, within stated limits
- Damage to hired property at the venue
- Public liability for injury to guests
- Photography and videography failure, on some plans
Typically not covered
- A change of mind by either party
- Cancellation for reasons known when the policy was bought
- Jewellery left unattended or in an unsecured room
- Jewellery not declared or valued where the policy requires it
- Cash above the stated limit
- Losses without a police report, where one is required
- Disputes between families
- Weather, unless the extension is purchased
Inclusions and exclusions vary between providers and between plans from the same provider. The wording in your own policy document is what governs — we will walk you through it before you buy.
How it works with us
- 1 We establish whether you actually need it Specialist covers are easy to sell and easy to over-sell. If your existing policy already responds, we will say so.
- 2 Valuation and documentation first These covers turn on what you can prove you owned and what it was worth. Getting that right before cover is the whole job.
- 3 Two or three quotes, compared on wording Specialist policies vary far more between insurers than mainstream ones. The exclusions are where they differ.
- 4 Underwriting, and a survey where the value warrants it Higher-value risks are inspected. It is also the moment to fix anything that would reduce a claim.
- 5 Policy issued, with the schedule checked line by line On a scheduled policy, an item not on the list is an item not insured. We check it with you before it goes on cover.
Important considerations
The things a brochure tends to leave out. Read these before you decide.
- Declare jewellery properly and keep valuations. A jewellery claim without documentation of what was owned and what it was worth is very difficult to settle.
- Buy when the first deposits are paid. The cancellation section is worth nothing if it is arranged after most of the money is already committed.
- Check the unattended property clause. Jewellery in a hotel room or a car is where most wedding losses actually happen, and where cover is most restricted.
- A change of mind is never covered. The cancellation section responds to circumstances outside the families' control, not to a decision not to proceed.
- Make sure the policy period covers every function. Multi-day weddings with events at different venues need the whole sequence named.
Documents required
- Identity and address proof
- Proof of ownership — invoices, receipts or certificates
- Valuation report, where the item value requires one
- Photographs of the insured items
- Details of storage and security arrangements
- Previous policy and claims history, where applicable
Frequently Asked Questions
Does it cover the wedding being called off?
Only for reasons outside the families' control — serious illness, an accident, a venue becoming unavailable, or in some cases severe weather. A change of mind by either party is not covered by any policy, and it is the most common reason weddings are called off.
Is jewellery covered while guests are wearing it?
Generally yes, subject to declaration and limits, and this is often the most useful part of the cover. What is heavily restricted is jewellery left unattended — in a hotel room, a car, or an unlocked space — which is unfortunately where most losses occur.
When should I buy it?
When the first substantial deposits are paid, typically several months ahead. Buying close to the date leaves the earliest and largest non-refundable commitments unprotected.
Does it cover all the functions or just the main day?
It should cover the whole sequence, but the policy period has to be set to include them. Multi-day weddings across different venues need each named, and this is a common gap.
What documentation do I need for a jewellery claim?
Purchase invoices, valuation certificates and photographs, plus a police report for theft. Assemble these before the wedding rather than trying to reconstruct ownership afterwards — it is the single thing that determines whether a claim is straightforward or not.
Want a shortlist instead of a catalogue?
Tell us the situation and an advisor comes back with two or three options that actually fit — and names what each one gives up.