
Wealth & Covers
Search products, guides, calculators
+919990003062

Vehicle Loan

Drive it home sooner

  • Multiple Lenders
  • Eligibility Check
  • Competitive Rates
  • End-to-End Support
Vehicle Loan

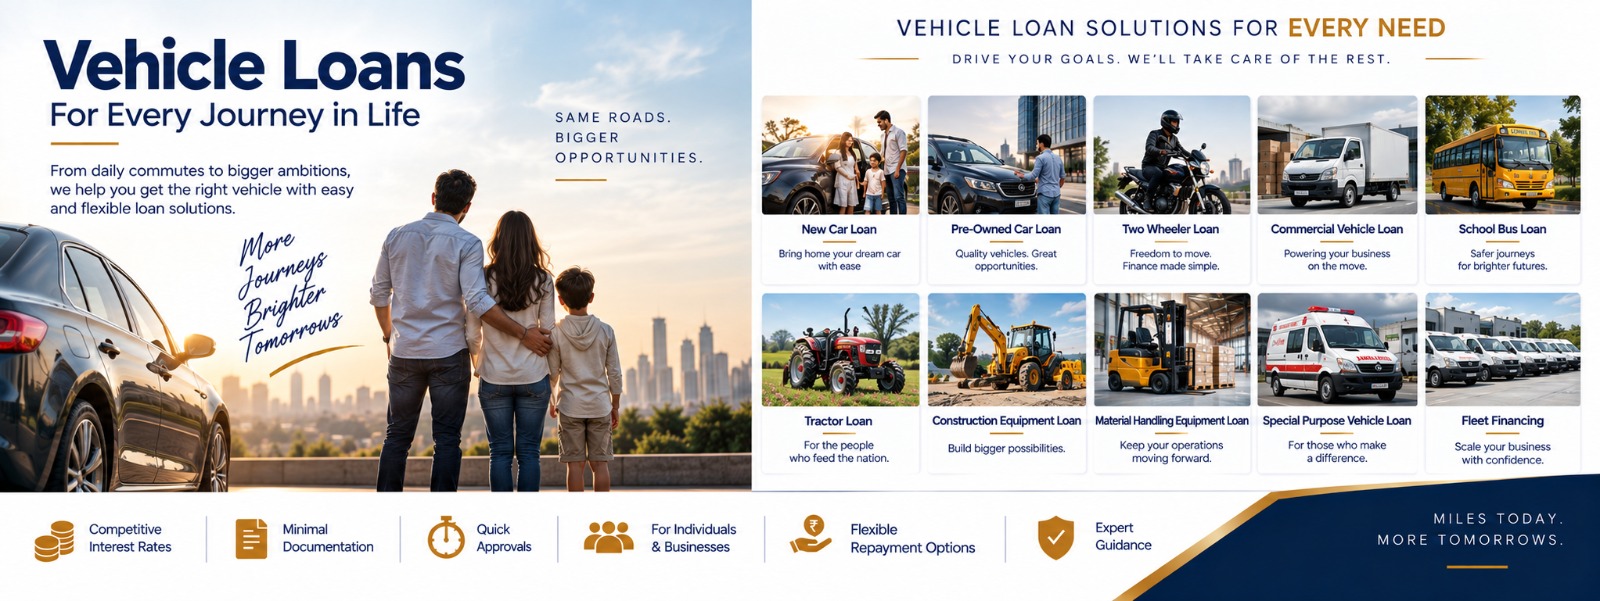
What are you looking to fund?

Choose the right loan

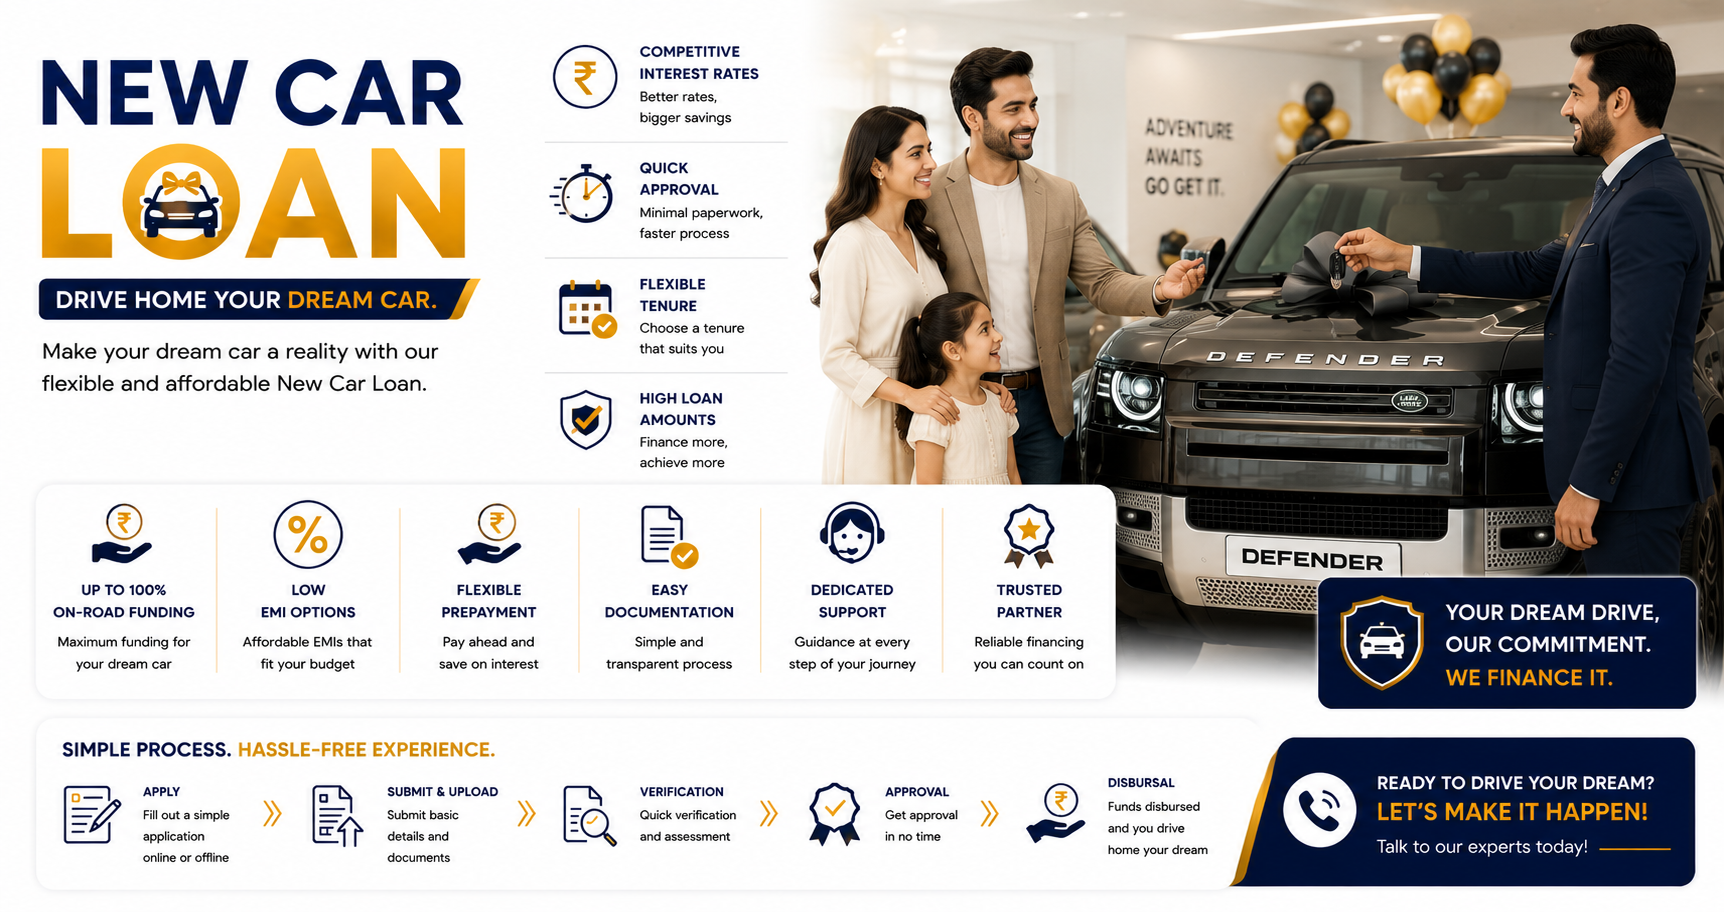
New Car Loan

Most Popular

Finance for a brand-new car, structured around what you can comfortably service rather than the maximum a lender will sanction.

  • Secured against the vehicle, so rates sit well below unsecured borrowing
  • Up to 80–90% of on-road price funded, and sometimes more for strong profiles
  • Tenures from one to seven years, letting you tune the EMI to your cash flow
View Details

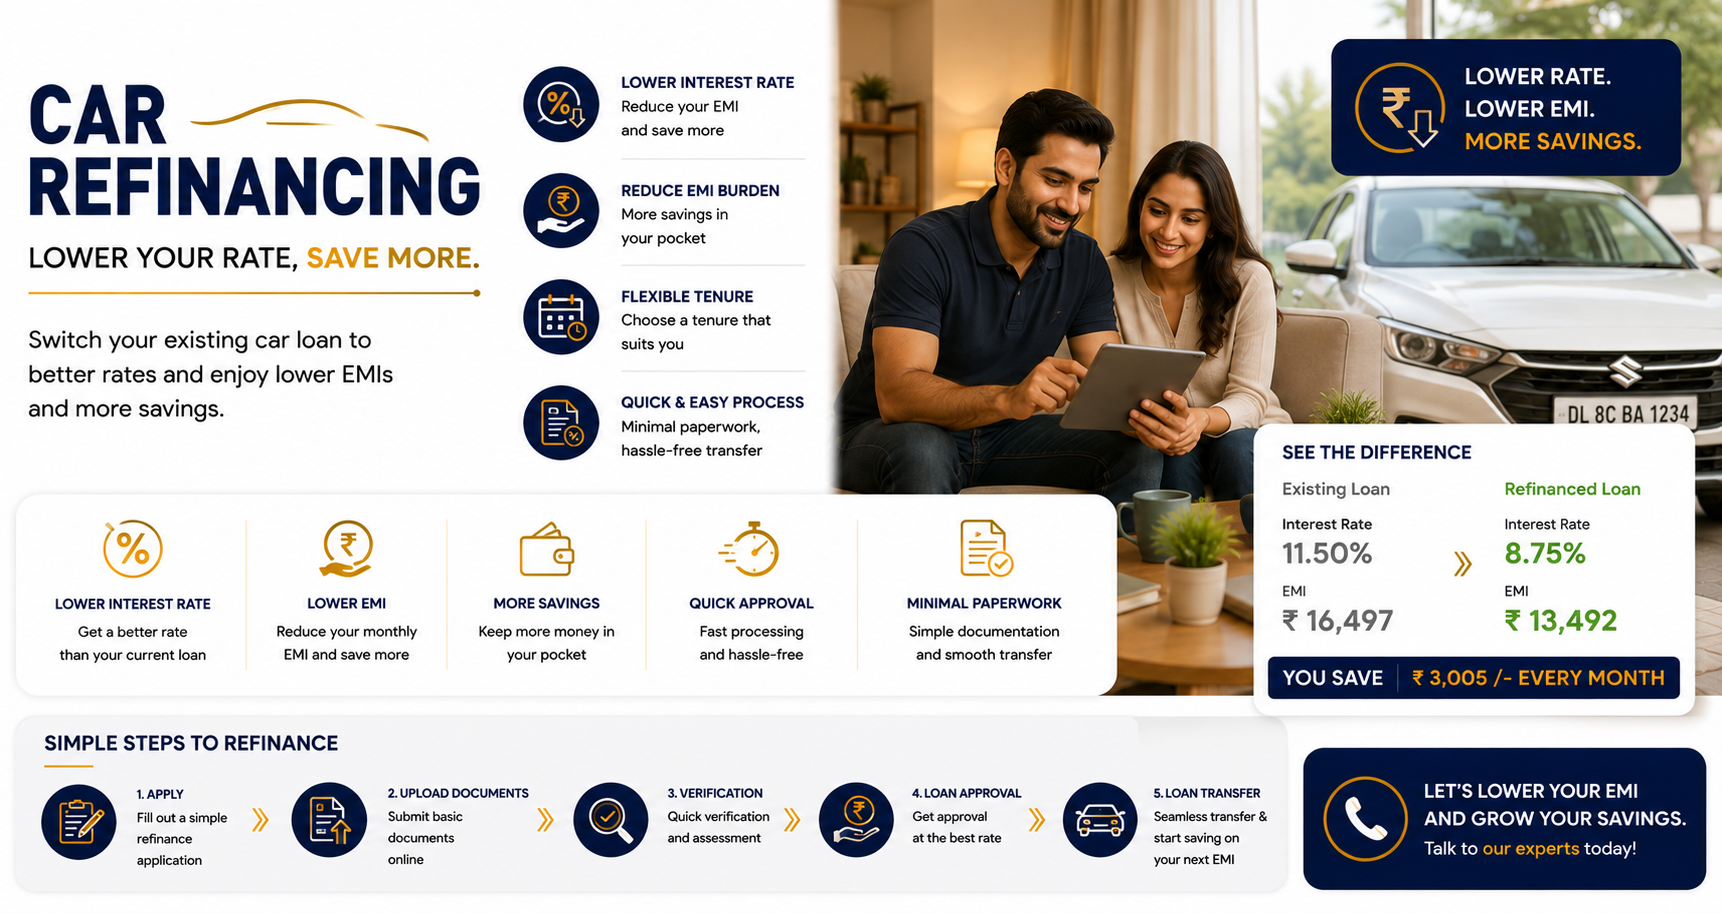
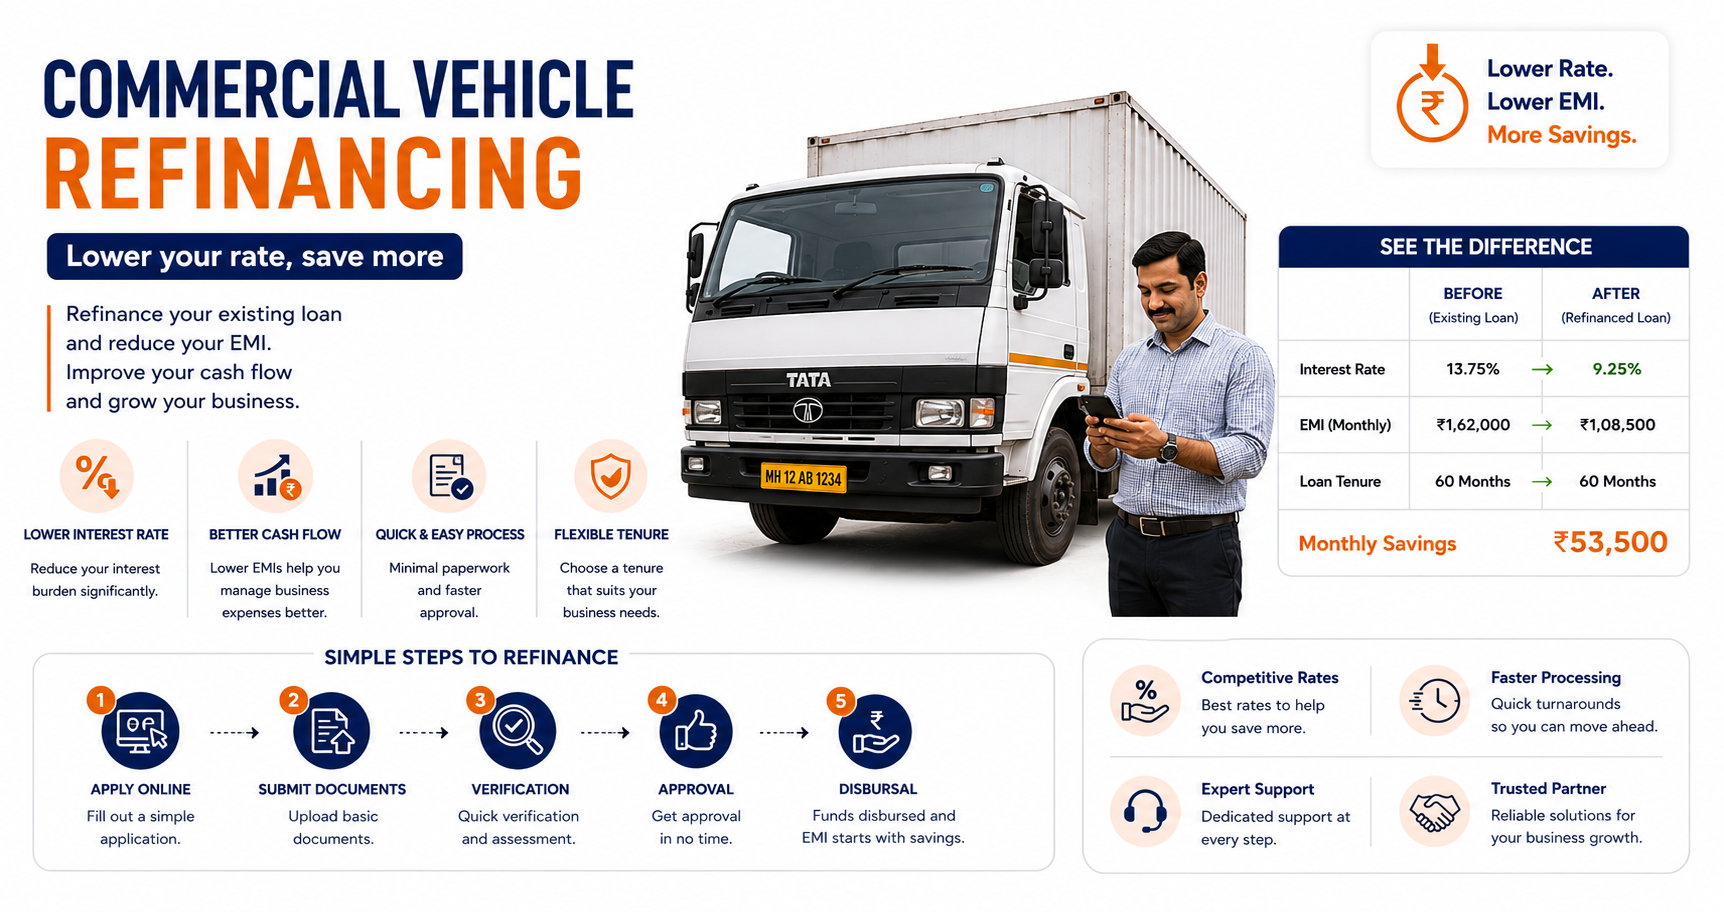
Car Refinancing

Borrowing against a car you already own — releasing cash from an asset without selling it.

  • Cheaper than an unsecured personal loan for the same amount
  • Funds released without selling the vehicle
  • You continue using the car throughout the loan
View Details

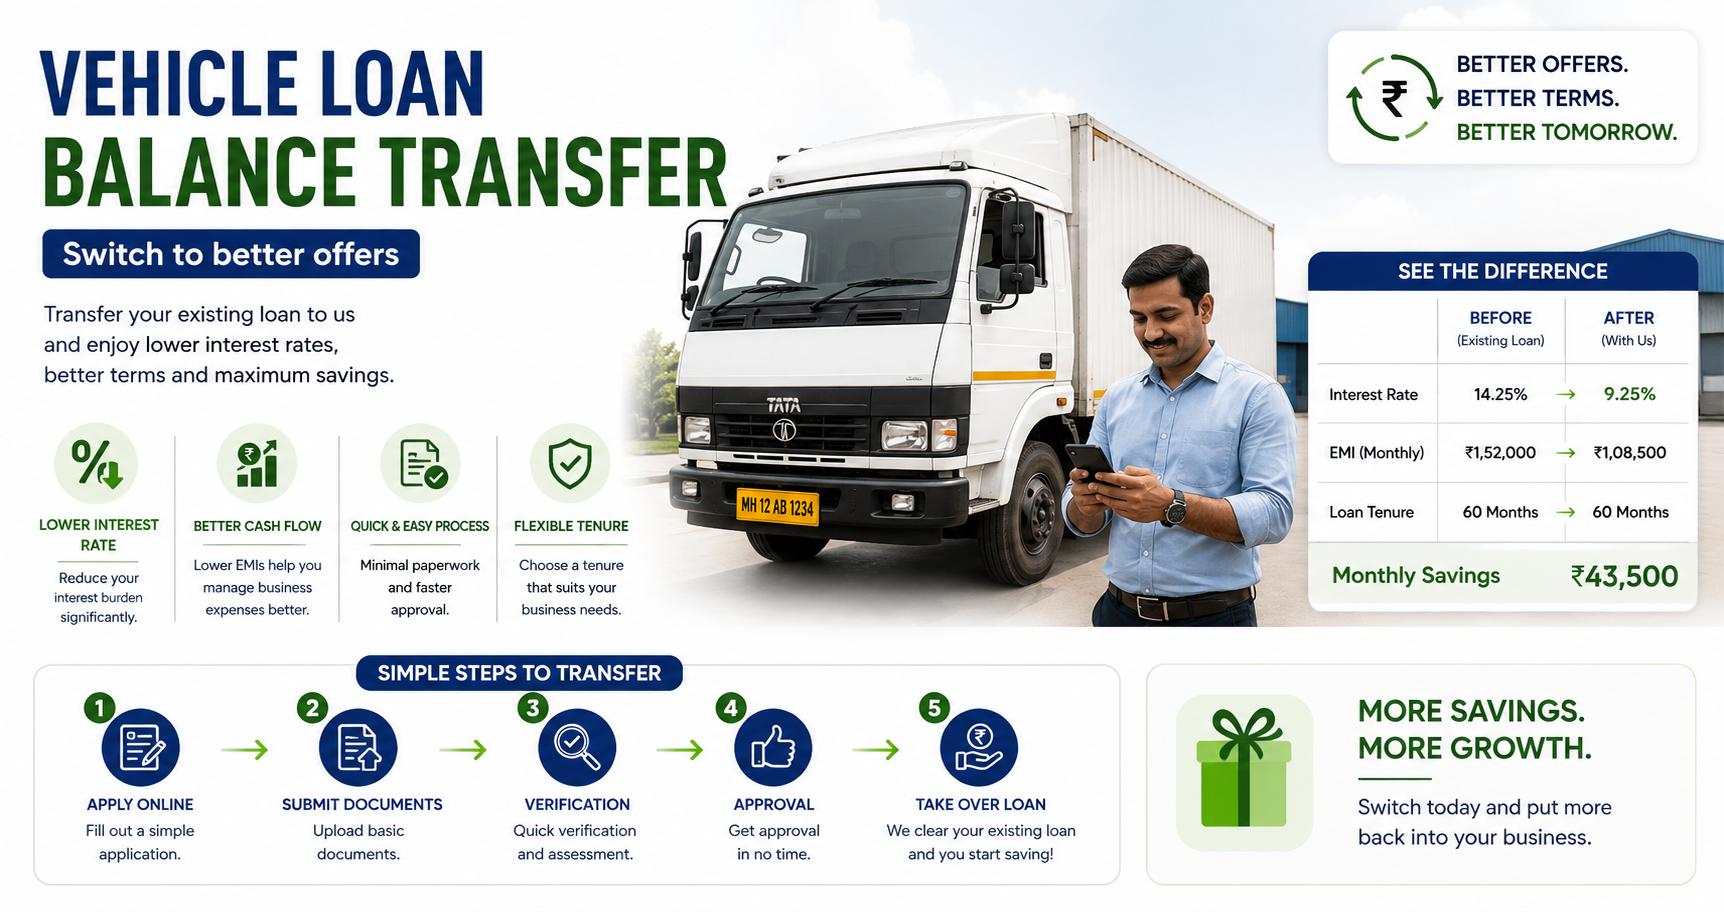
Vehicle Loan Balance Transfer

Moving an existing vehicle loan to a cheaper lender — worth doing only when the arithmetic clears the costs.

  • A lower rate reduces both the EMI and the total interest
  • Tenure can be restructured at the same time
  • A top-up may be available alongside the transfer
View Details

Plan Today. Own Tomorrow.

Why Vehicle Loan?

  • Secured against the vehicle, so rates sit well below unsecured borrowing
  • Up to 80–90% of on-road price funded, and sometimes more for strong profiles
  • Tenures from one to seven years, letting you tune the EMI to your cash flow
  • No prepayment penalty on floating-rate loans to individuals, under RBI rules
  • Manufacturer and dealer subvention schemes can undercut standard bank rates

More than Loans A Partner for Life

What's Included?

  • Ex-showroom price of the vehicle
  • Road tax and registration charges, at most lenders
  • Insurance for the first year, where the lender permits it to be funded
  • Manufacturer-fitted accessories included in the invoice
  • Extended warranty, at some lenders, where invoiced with the vehicle
View complete coverage

Things to Keep in Mind

  • Down payment — the margin you contribute, typically 10 to 20 per cent
  • Aftermarket accessories not on the vehicle invoice
  • Processing fee, documentation and stamping charges
  • Ongoing running costs, servicing and annual insurance renewals
  • Any shortfall between the loan outstanding and an insurance settlement after a total loss
View all details

Compare Popular Loans

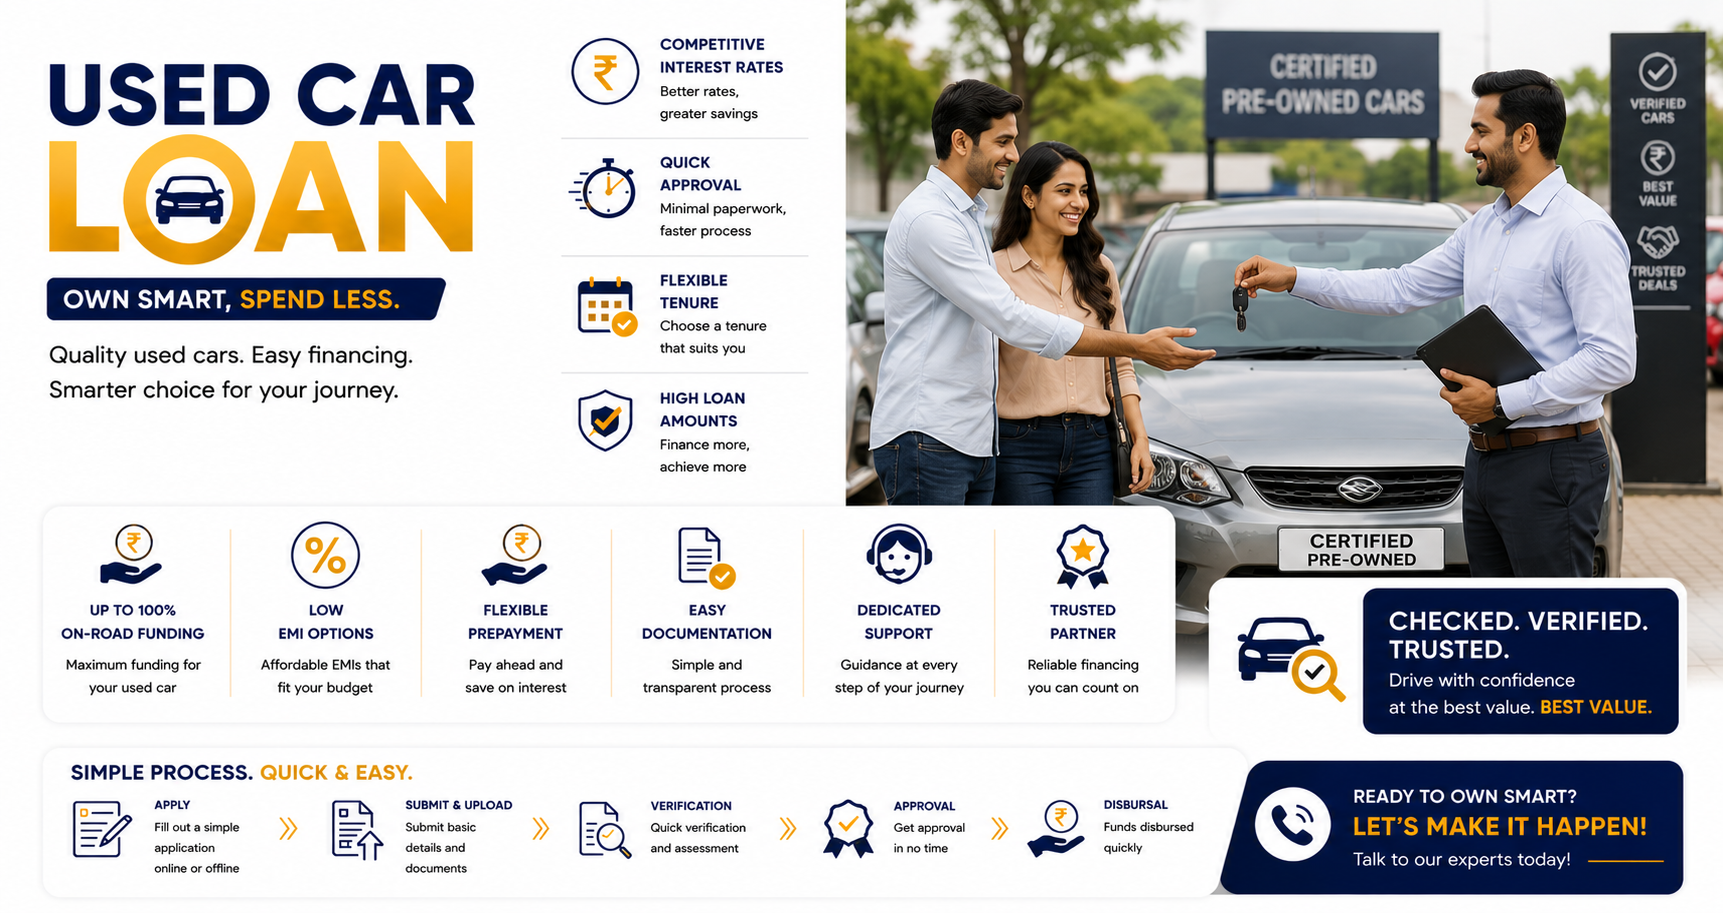
Plan New Car Loan Car Refinancing Vehicle Loan Balance Transfer Used Car Loan
Best for Drive home your dream car Lower your rate, save more Switch to better offers Own smart, spend less
Interest from* 9% 13% 9.5% 12.5%
Rating 4.5 4.0 4.1 4.3
Details View View View View

*Indicative starting figures; the final terms depend on your profile.

Compare Plans

Already have a loan?

Review your existing loans and make sure you're not paying more than you need to.

  • Check for a lower rate
  • Explore a balance transfer
  • Check top-up eligibility
  • Get expert recommendations

Get your current loan reviewed

Share it with an advisor — no cost, no obligation

We're Here Till Your Last EMI.

Frequently Asked Questions

View All FAQs
How much of the car's price will a lender actually fund?

Most lenders fund 80 to 90 per cent of the on-road price, and strong profiles are sometimes offered more. Funding the maximum is not always wise: a car depreciates from the day it is registered, and a small down payment over a long tenure leaves you owing more than the vehicle is worth for a significant part of the term.

Which tenure should I choose?

The shortest one whose EMI you can service comfortably alongside your existing obligations. Extending the term reduces the monthly figure and increases the total interest meaningfully. Run both through the EMI calculator on this page and compare the total repayment, not just the instalment.

Is dealership finance a good deal?

Sometimes — manufacturer-subvented schemes can genuinely undercut a bank. Often it is simply the offer that was nearest to hand. Ask for the rate, the processing fee and the total repayment in writing and compare it against a direct offer before you commit. The comparison takes an hour and is usually worth more than anything negotiated on accessories.

Can I prepay or foreclose the loan early?

Floating-rate loans to individual borrowers cannot carry prepayment or foreclosure charges under RBI rules. Fixed-rate loans can, and many do. Establish which type you are signing before you plan around prepaying.

What credit score do I need?

There is no single threshold, and lenders differ. A stronger score improves both the likelihood of approval and the rate you are offered, and the rate difference across score bands is large enough to be worth attending to. We check your profile against lender criteria before submitting, so applications are not scattered across lenders who were never going to approve.

Not sure what vehicle loan you need?

Tell us about your needs. Our experts will help you find the right loan.

Talk to an Expert

Speak to an advisor

Good decisions begin with clarity.

Tell us where you are today. We’ll help you understand what matters, what may be missing, and what you can do next.

See the full picture
Understand what you already have and where it stands.
Find what's missing
Identify the gaps that could affect your family, wealth or business.
Know what to do next
Get practical guidance built around your priorities — not a product pitch.

No pressure. No obligation. Just a thoughtful conversation.

Let's Connect

Your details are safe & confidential. We'll contact you only regarding your enquiry.